

Disclaimer: The information provided in this publication is for educational and informational purposes only and does not constitute financial advice. The content is solely reflective of my personal views and opinions based on my research and is not intended to be used as a basis for investment decisions. While every effort is made to ensure that the information is accurate and up-to-date, the writer makes no representations as to the accuracy, completeness, suitability, or validity of any information in this post and will not be liable for any errors, omissions, or delays in this information or any losses, injuries, or damages arising from its display or use. All readers are advised to conduct their own independent research or consult a professional financial advisor before making any investment decisions. The author is not invested in the mentioned stock.
E-Book and Paperback “Investing in Small-Caps - The ultimate Guide”

Introduction
Argan, Inc. is one of those companies that looks boring from the outside — a construction holding company building power plants — yet the deeper you dig, the more impressive it becomes. While most EPC contractors struggle with debt, low margins, and volatile results, Argan has quietly built a track record of strong execution, a fortress balance sheet, and powerful cash generation.
And in 2025, the market finally noticed: the stock has gone vertical, backlog hit record levels, and Argan is suddenly valued like a premium infrastructure compounder rather than a cyclical contractor.
In this post, we break down what’s really behind Argan’s rise — the business model, the financial engine, the strengths, the risks, and whether the current valuation still leaves room for long-term upside.
Company Overview
Argan, Inc. (NYSE:AGX) may sound low-key, but it’s actually a powerhouse behind… well, actual powerhouses. It’s a holding company built around big-league construction and engineering, especially in energy infrastructure. Argan runs four main subsidiaries — each doing something very different, but all feeding the same industrial machine:
• Gemma Power Systems (GPS) – Argan’s star player and major revenue engine. GPS is a top EPC contractor that designs and builds large-scale power plants (mostly natural gas, some renewables), with 16,000+ MW installed. They run full turnkey projects from blueprint to final switch-on, making up ~79% of Argan’s revenue.
• Atlantic Projects Company (APC) – Argan’s international arm, based in Ireland. APC handles turbine/boiler installation and commissioning for utilities, independent power producers, and even huge data centers across Ireland and the U.K.
• The Roberts Company (TRC) – An industrial construction and fabrication specialist in North Carolina. TRC builds piping systems, pressure vessels, and handles maintenance for major industrial clients, growing fast with “blue chip” manufacturers in the U.S. Southeast.
• SMC Infrastructure Solutions (SMC) – The smallest unit but a smart diversifier. SMC installs fiber-optic networks, data wiring, and utility infrastructure under recurring service agreements — tapping into ongoing telecom buildouts.
Argan runs all this through a decentralized structure: each subsidiary operates independently while the parent company focuses on strategy and capital allocation. Its acquisition strategy targets niche, high-skill industrial and construction firms — a playbook used successfully since buying GPS in 2006.
In short, Argan has carved out a role as a go-to builder of critical infrastructure — from natural-gas power plants to industrial facilities to the data networks powering the digital world.
Latest Financials
Argan’s recent financial performance has been impressive. In the fiscal year ended January 31, 2025 (Fiscal 2025), revenue surged to $874 million, a 52% jump from the prior year’s ~$573 million, driven by strong progress on several large power plant projects. This sharp increase in activity translated into significantly higher profitability: Argan reported $85.5 million in net income (or $6.15 per share), nearly tripling the previous year’s result. Margins expanded meaningfully as well, with gross margin rising to 16.1% (from ~14.1%), yielding approximately $141 million in gross profit.
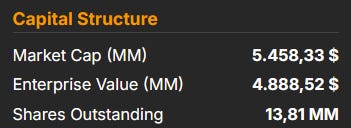
A key indicator for any construction contractor—backlog—told an even stronger story. By year-end, Argan’s backlog had grown to over $1.3 billion, more than double the ~$0.6 billion posted a year earlier. This enormous pipeline provides excellent revenue visibility for the coming years and confirms that Argan secured multiple major new projects. All of this was supported by a rock-solid balance sheet: zero debt, $145 million in cash, and an additional $227 million invested in U.S. Treasuries, giving the company exceptional financial flexibility.
The momentum carried straight into Fiscal 2026. In Q2 FY2026 (ended July 31, 2025), Argan generated $237.7 million in revenue, a modest 4.7% year-over-year increase, while profitability accelerated sharply. Gross margin improved to 18.6%, lifting gross profit to $44.3 million. Net income nearly doubled to $35.3 million (or $2.50 per share), and EBITDA reached $36.2 million with a 15.2% margin. The company also reported a record ~$2.0 billion backlog, underscoring continued strong demand across its project portfolio.
Balance sheet strength remained a standout feature: Argan ended the quarter with $572 million in cash and investments and roughly $344 million in net liquidity, all while maintaining zero debt. Reflecting this financial health, the quarterly dividend was increased to $0.375 per share.
Across the first half of Fiscal 2026, revenue totaled $431 million, up about 12% from the prior year, while net income surged to $57.8 million (or $4.09 per share)—more than double the prior-year period. First-half gross margin averaged an impressive ~18.8%, highlighting continued operational strength. Although quarterly revenue growth was somewhat modest, Argan’s rapidly expanding margins, soaring backlog, and exceptional liquidity position place the company in an enviable competitive and financial position heading into the remainder of FY2026 and beyond.
Key financials
While Argan often flies under the radar, its financial performance over the last several years tells the story of a company that quietly operates with the discipline, balance sheet strength, and cash-flow power that many larger engineering firms envy. The four charts reveal the same core truth again and again: Argan does not behave like a typical cyclical contractor. It behaves like a company that knows exactly when to take risk — and when not to.
Zero Debt, Always: Net Debt/EBITDA as a Strategic Choice
The first chart — Net Debt to EBITDA — reads almost like a philosophical statement. Argan has consistently maintained net cash, not net debt, across nearly every year shown. Even during weaker operating periods (like FY2020), the company never leaned on leverage to cushion itself. Instead, it preserved its balance sheet and waited for better project timing.
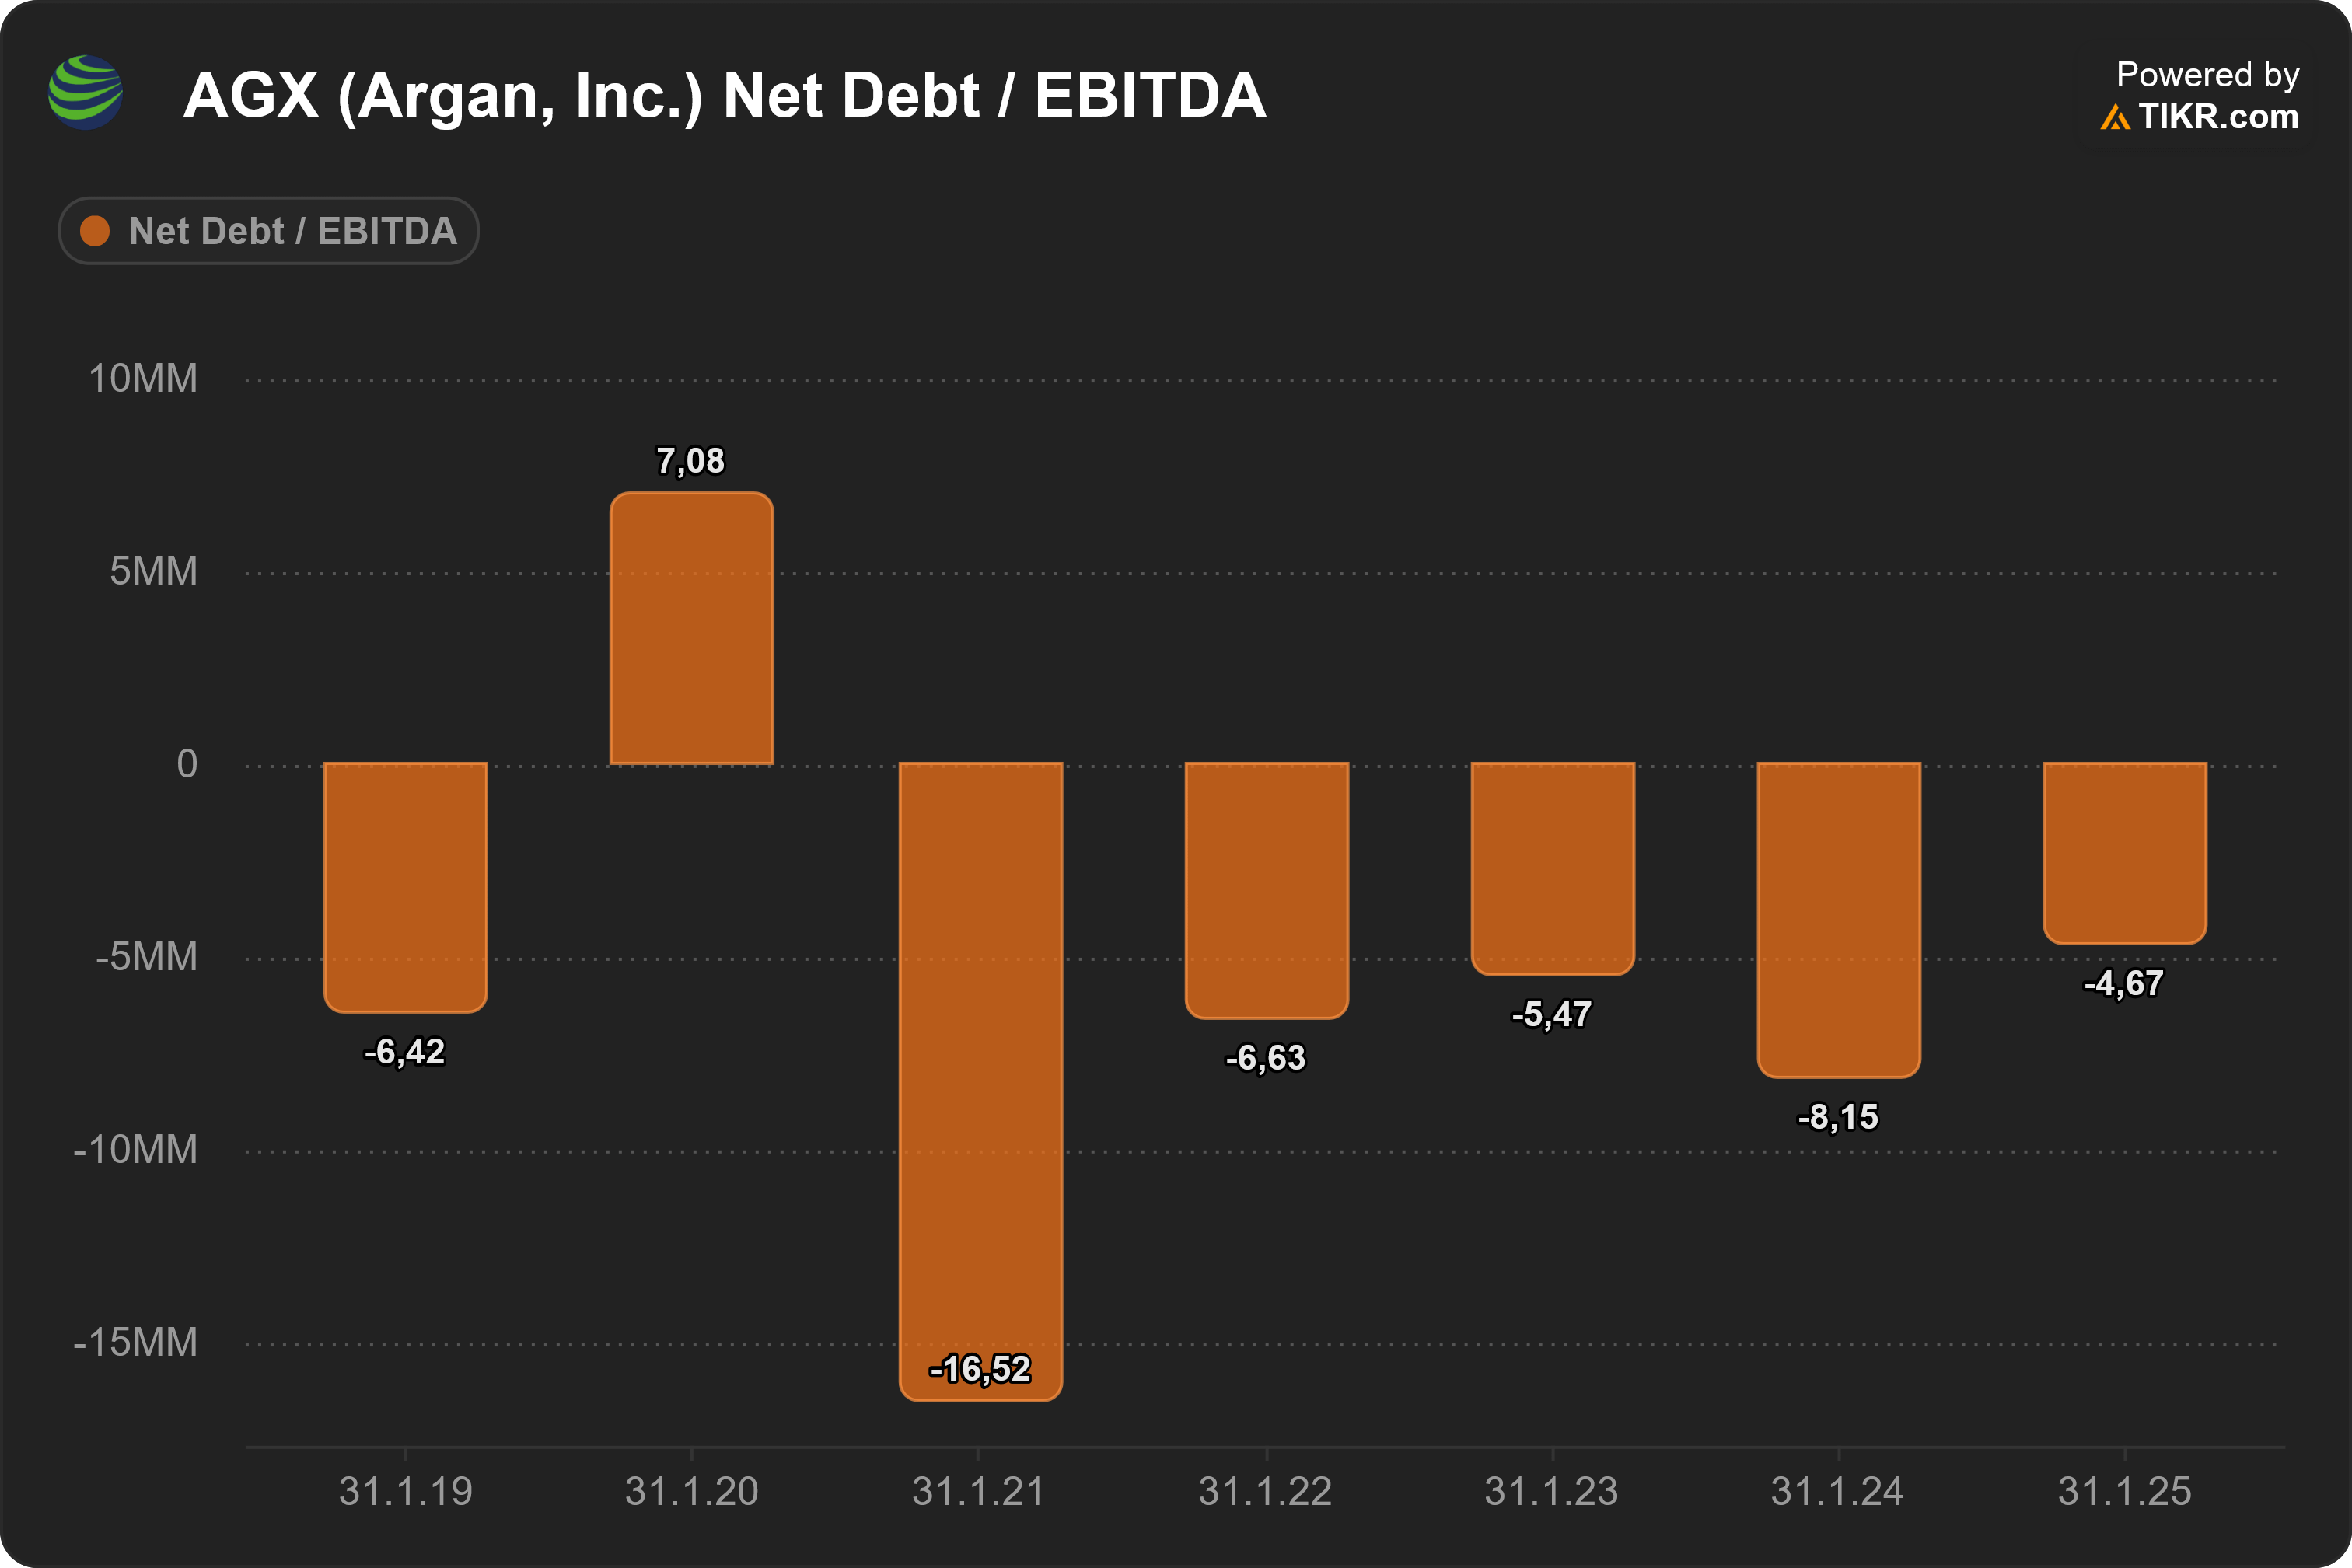
You see deep negative values (like –16.5x EBITDA in FY2021) because Argan held so much cash relative to its earnings base in those years. This isn’t financial engineering — it’s operational discipline. Argan takes up-front customer deposits, manages working capital tightly, and refuses to overextend itself. The result: a balance sheet that removes existential risk from the business and gives management the flexibility to pounce when major EPC opportunities arise.
In an industry where many peers carry debt because they must, Argan carries cash because it chooses to.
A Cash Machine — When the Project Cycle Aligns
The second chart tells the real story of Argan’s operational engine: free cash flow. The volatility is unmistakable — dramatic swings from deep negative FCF (–$121M) to sky-high positive years like $174M (44% margin!).
This is the nature of fixed-price EPC:
when large projects ramp → Argan invests in working capital → FCF dips
when milestones are met and customer payments flow → FCF surges
The important part is not the volatility itself, but the pattern: when Argan executes well on large projects, cash flow becomes exceptionally strong, far beyond what investors typically expect from a contractor.
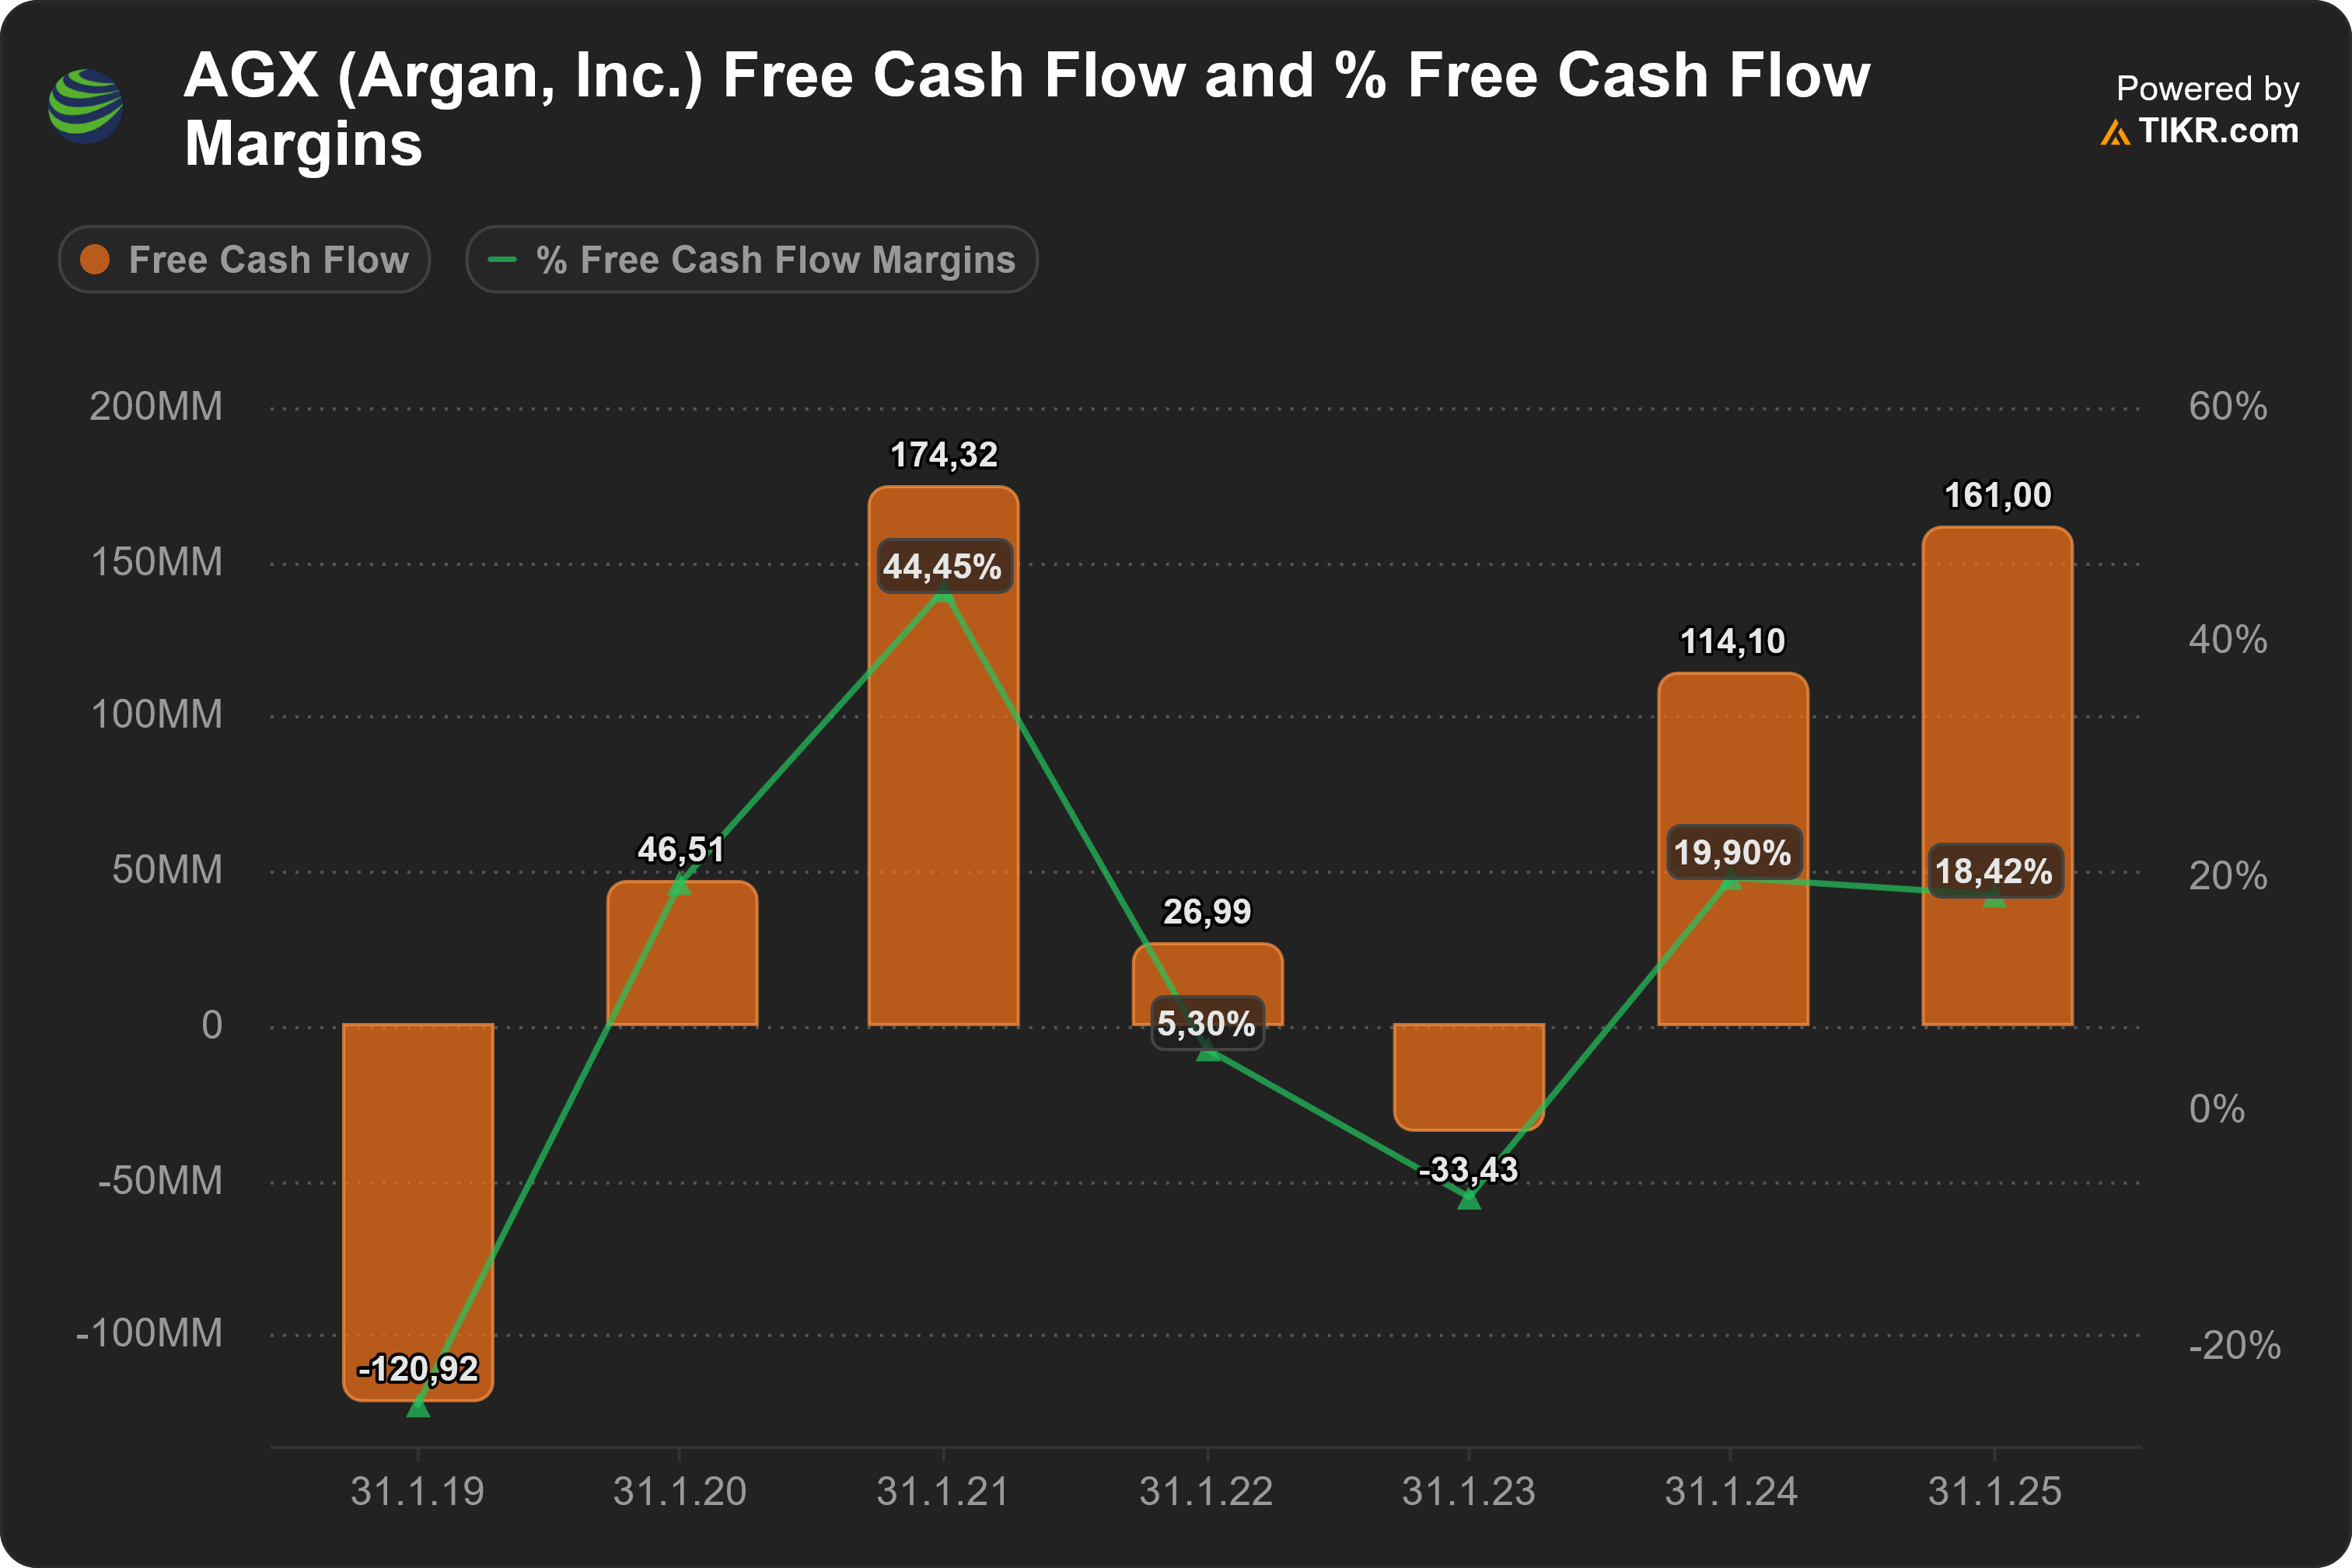
The recent climb — $114M in FY2024 and $161M in FY2025 — confirms what the income statement also reflects: Argan is in a strong upcycle, converting backlog into cash at increasingly attractive margins. This is happening precisely because the company is securing and executing projects that competitors abandoned due to risk — and getting paid well for doing so.
Margins and Returns Rebound Sharply — A Testament to Execution
Chart three tracks EBIT margins, net margins, and return on capital, and it captures the heart of Argan’s cyclical-but-controlled business model.
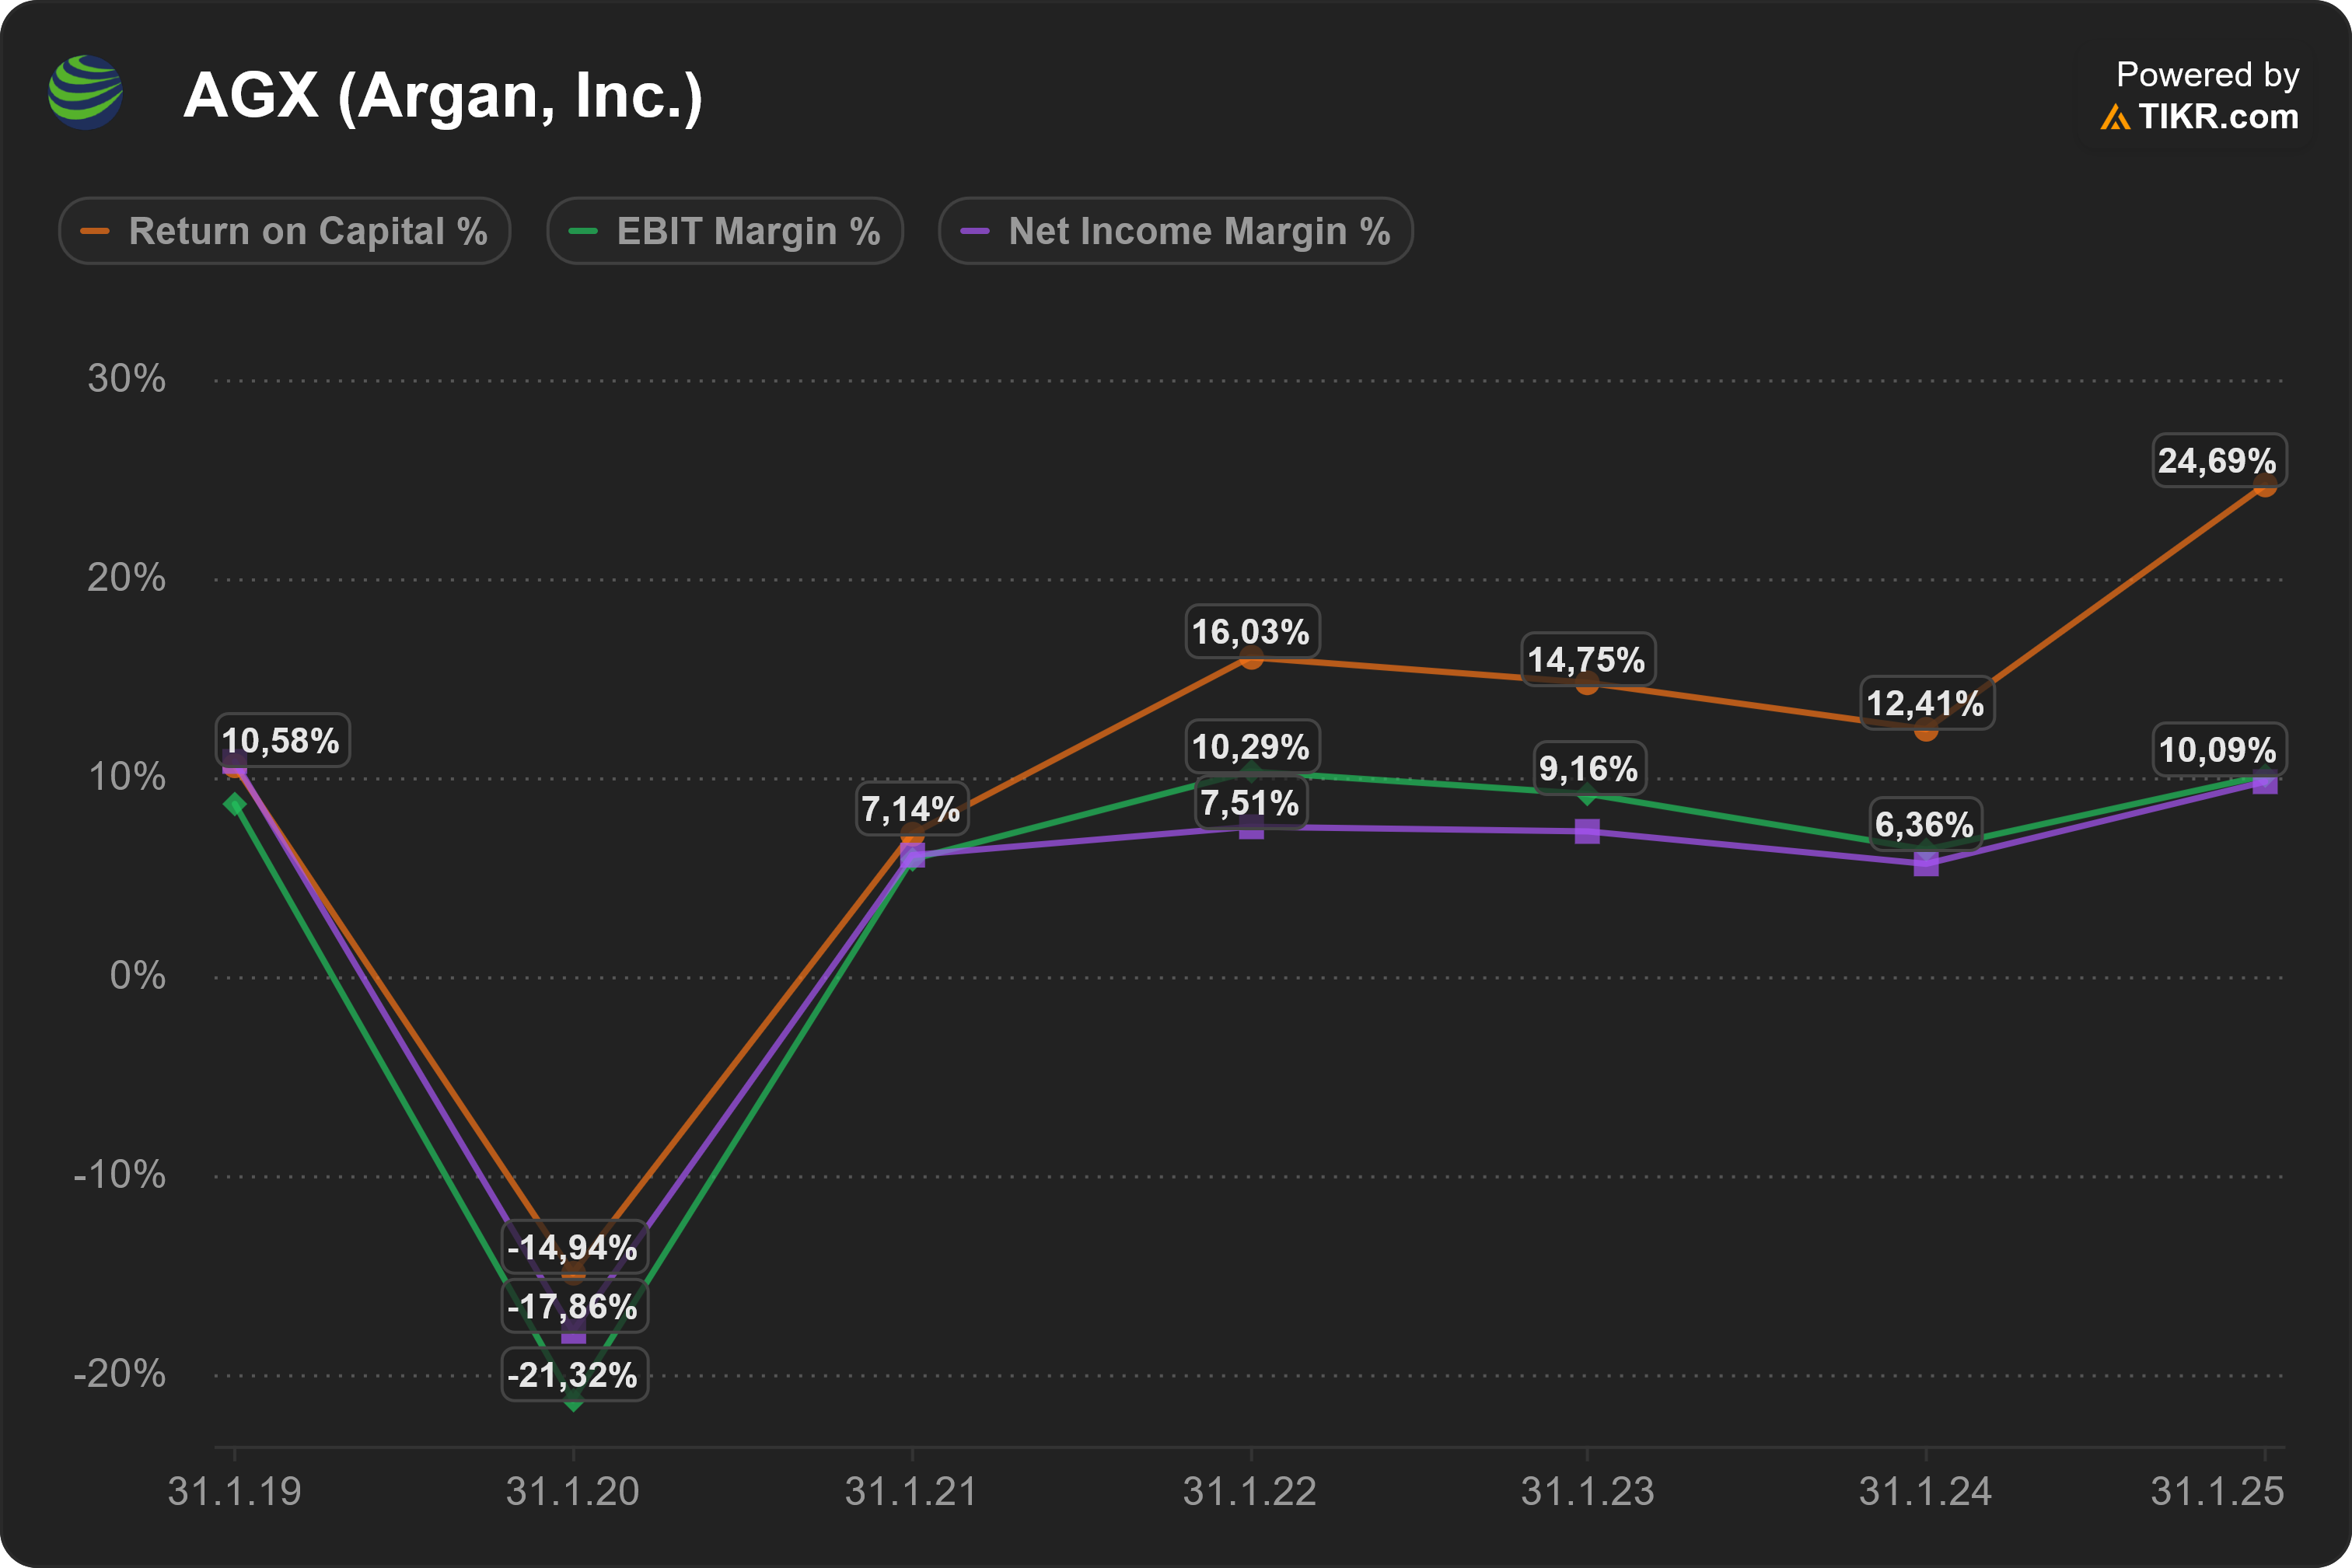
FY2020 sticks out like a bruise: margins collapsed, returns went deeply negative, and earnings evaporated. But what happened next is the real takeaway — Argan bounced back fast and clean.
EBIT margin rose from –17.9% (FY2020) to 10.3% (FY2022)
Net income margin followed suit, climbing from –21% to 7.5%
Return on capital surged to 16% in FY2022
By FY2025, ROC jumped again to 24.7%, demonstrating that Argan is not just earning more — it is earning extremely well on the capital employed.
This is the return profile of a company that:
controls costs aggressively
bids only on projects where it has real edge
delivers consistently on fixed-price contracts
In contrast, many global EPC firms have tolerated sloppy contracts or volatile returns. Argan’s margin arc tells a radically different story: the company tightens, chooses, and executes its way to sustainable high returns.
Revenue Explodes as Backlog Converts — But Profitability Steps Up, Too
The final chart — revenue, operating income, and net income — pulls everything together.
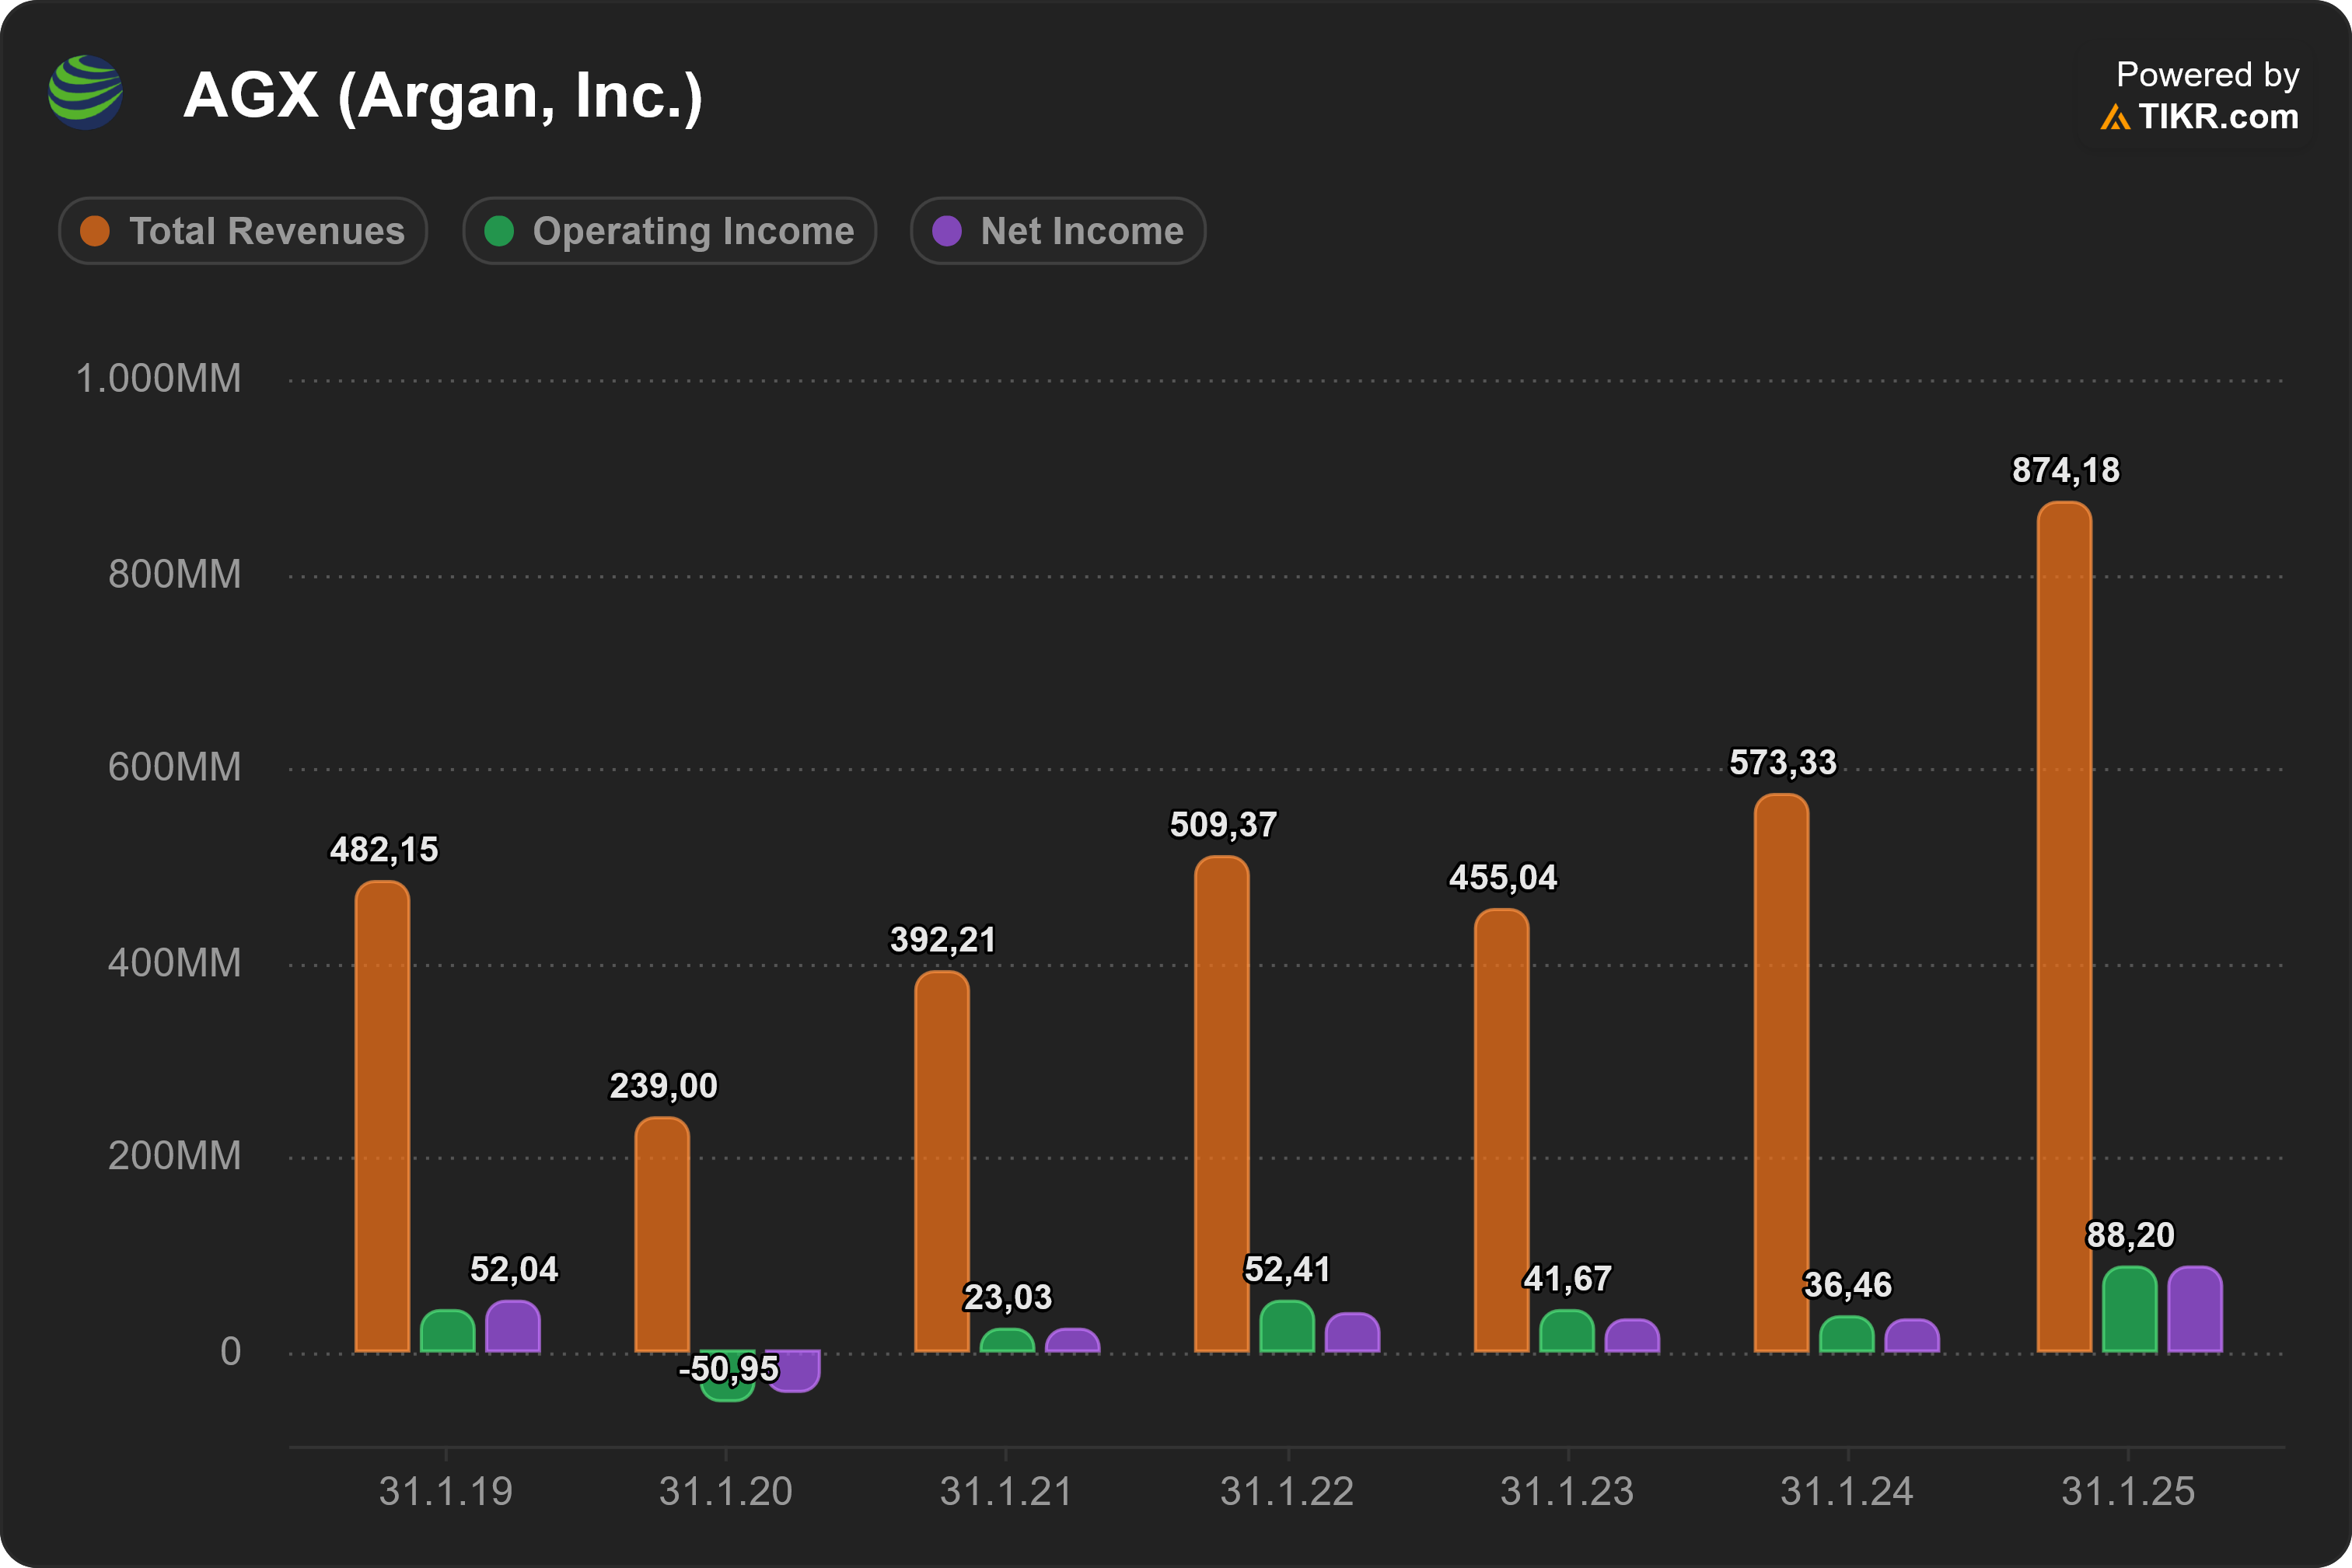
Revenues grew from $455M (FY2023) to $573M (FY2024) and then blew past expectations to reach $874M in FY2025. But revenue growth is only half the story. Operating income and net income both surged, with FY2025 net income jumping to $88M, the highest in Argan’s history.
This confirms that Argan isn’t merely taking on more work — it’s taking on profitable work.
The EPS expansion comes from three flywheels working together:
Backlog growth: more long-duration, high-value EPC projects
Margin expansion: thanks to execution and favorable contract selection
Share count reduction: from years of buybacks
Where many EPC firms chase revenue at any cost, Argan does the opposite: it waits for the right projects and then delivers them with tight discipline.
The Big Picture
Seen together, the charts paint the portrait of a company that behaves far more like a high-quality compounder than a traditional contractor:
Balance sheet: perpetually in net cash → strategic optionality + low risk
Cash flow: volatile but explosively positive in upcycles
Margins & Returns: consistently improving → now top-tier in the EPC industry
Revenue & earnings: entering a multi-year growth phase driven by mega-projects
This is exactly the financial profile you would expect from a company that:
dominates a niche abandoned by competitors
wins contracts because of execution, not lowball pricing
gets paid up-front by customers
runs a conservative, shareholder-aligned capital structure
Argan’s charts show a business that doesn’t need leverage, doesn’t burn cash over the cycle, and doesn’t depend on heroic turnaround plans. Instead, it thrives on reliability, discipline, and selective aggression when the right EPC opportunities appear.
Business Model
So how does Argan actually make money? On paper, it’s simple: they build very big, very complicated stuff. But the way they operate — and where the real upside and risks lie — is a lot more interesting.
Most of Argan’s revenue comes from fixed-price EPC projects (engineering, procurement, construction) for huge power plants. Through Gemma and APC, Argan designs the plant, buys the turbines and generators, builds the whole facility, and hands over a fully operational power plant. These are multi-year, hundreds-of-millions-of-dollars projects, ranging from combined-cycle gas plants to solar farms, wind installations, and battery storage. This is the “big leagues” of construction — long timelines, huge teams, and tight technical requirements.
The Roberts Company plays in a different arena: industrial construction. TRC sends skilled crews into factories and refineries for upgrades, maintenance, and expansions. These jobs are often shorter but steady — and sometimes billed time-and-materials, which keeps risk low. TRC has been on a tear, nearly doubling revenue in two years by winning larger field-service projects for blue-chip manufacturers.
SMC, the telecom unit, is smaller but steady. It works under master service agreements, installing fiber-optic lines and secure data wiring — occasionally in government facilities that require high-level security clearances. Not glamorous, but reliable.
A key feature of Argan’s model is contract concentration: a handful of giant projects often drive most of the revenue. In some years, one or two clients can represent a big chunk of sales. That means Argan’s results can get lumpy — revenue jumps when big projects ramp up and dips when they finish. If you’re an investor, you simply have to accept the quarterly roller coaster.
Then there’s the big twist: many of Argan’s projects are fixed-price. The client pays one number, period — even if costs blow up. This can be a disaster for undisciplined contractors. But Argan has made it a strength. The company avoids “high-risk” deals, bids carefully, and relies on Gemma’s excellent execution track record. While many competitors have abandoned fixed-price power-plant work entirely, Argan has stayed in the game, largely because they know how not to lose money on these projects.
Profitability in construction is usually thin, yet Argan consistently posts healthy margins. Bonus incentives help: if Gemma delivers ahead of schedule or under budget, they can earn extra fees. Given Argan’s results, it’s safe to say there have been more bonuses than penalties.
Cash flow is another hidden strength. Many clients pay progress payments upfront, meaning Argan often uses customer money to fund the work — a beautiful dynamic for any contractor. In FY2025, contract liabilities jumped by $118 million, boosting cash flow without Argan lifting a finger. Combine that with zero debt, and you get a business that quietly builds a massive cash pile while executing giant projects.
In short, Argan’s model is all about landing big, complex contracts and then executing them with ruthless discipline. When done right, a single project can throw off enormous profit — and Argan has built a reputation for doing it right. That’s how the company has grown, stayed profitable through cycle after cycle, and amassed a balance sheet most competitors would envy.
Strengths and Competitive Advantages
Argan has a surprisingly strong competitive moat for a company that literally builds giant metal boxes that generate electricity. Here are the big advantages that make the story compelling:
• Proven EPC Expertise (aka: They actually finish projects on time)
Gemma is widely viewed as one of the best builders of natural-gas power plants in the U.S. While other large contractors have crashed and burned on fixed-price EPC work — some even quit the market entirely — Gemma kept delivering projects on time and on budget. That leaves Argan with fewer real competitors, better odds of winning contracts, and the ability to bid selectively instead of racing to the bottom. In an industry where execution is everything, this is a massive advantage.
• A Monster Backlog + Loyal Clients
Argan’s $1.3 billion backlog gives it a multiyear runway of revenue and puts it in a rare position of visibility for a contractor. Utilities, independent power producers, and industrial giants keep coming back to Gemma and TRC because they trust the delivery. TRC’s roster even includes blue-chip manufacturers — the kind who do not tolerate sloppy work. Repeat customers in construction are the ultimate vote of confidence.
• Fortress Balance Sheet (Truly debt-free, not “adjusted” debt-free)
Argan has zero debt, piles of cash, and enough investments to ride out nearly any downturn. This matters a lot: construction projects require bonds, guarantees, and sometimes upfront working capital. Argan can self-finance all of it, while weaker competitors have to beg lenders for support. Management openly says they have more liquidity than they will need for years — a luxury in this industry.
• Shareholder-Friendly Capital Allocation
Argan doesn’t hoard cash; it returns it. The dividend has been raised twice since 2022, currently sitting at $0.375 per share, and the company has repurchased over $100 million of stock through a $125 million buyback program. Management only does this when they believe shares are cheap — a shareholder-friendly signal and a meaningful boost to long-term returns.
• Niche Diversification That Actually Helps
While big EPC power projects are the main show, Argan has smart side businesses:
– TRC brings in steadier industrial maintenance and fabrication work.
– SMC taps into telecom and secure data-infrastructure jobs.
– APC gives them international exposure.
These aren’t huge segments yet, but TRC’s growth from under $100M to $168M in two years shows the potential. Together, they smooth out the volatility of Argan’s big-ticket project cycle.
• Positioned for the Energy Transition (without pretending to be a solar startup)
Despite being known for gas plants, Argan is aggressively leaning into renewables, battery storage, hydrogen-ready facilities, and carbon-capture projects. The massive Texas plant Gemma just won even includes optional carbon-capture capability — a sign the company is evolving with the market rather than resisting it. Argan’s engineering know-how in large-scale power systems gives it a natural edge in building the next generation of energy infrastructure.
Weaknesses and Risk Factors
No company is perfect — and Argan is no exception. Here are the key risks worth keeping on your radar:
• Revenue Concentration & “Project Lumpiness”
Argan lives and dies by a handful of mega-projects. When they win big, revenue skyrockets. When projects finish and nothing new starts immediately, results can fall off a cliff. It’s completely normal for Argan to swing from record highs to slower years simply based on the timing of two or three major contracts. Great for long-term investors, not always great for anyone obsessively refreshing quarterly numbers.
• Fixed-Price Contracts (High Skill, High Stakes)
Fixed-price EPC deals are a double-edged sword. If Argan executes perfectly, margins shine. But if costs blow out — weather issues, labor shortages, supply-chain surprises — Argan eats the loss. The company is extremely disciplined in bidding and has an enviable track record, but one bad project can still dent a quarter or even a full year. This is the nature of the business: high reward, very real risk.
• Cyclical Demand + Macro Sensitivity
You don’t build a power plant unless you’re confident in the economy, electricity demand, and financing conditions. If growth slows or interest rates stay restrictive, developers may delay or cancel projects. TRC’s industrial work is also tied to corporate expansion cycles. In short, Argan’s revenue pipeline can be influenced by GDP swings, rates, and energy-market sentiment.
• Energy Transition & Policy Shifts
Natural gas plants are Argan’s bread-and-butter — but over the next 10–20 years, the world is pushing harder toward zero-carbon energy. If utilities pivot heavily to wind, solar, and storage (and avoid new gas turbines), Argan must win enough renewable, battery, hydrogen, or carbon-capture projects to replace lost volume. They’re making progress, but the long-term trend still matters. Today gas plants are thriving; in 2050, who knows?
• Competition Could Heat Up Again
Right now Argan enjoys a field with fewer serious competitors, thanks to rivals exiting after disastrous EPC losses. But success attracts attention. Giants like Bechtel or Fluor could decide to re-enter the market, foreign EPCs could show up, and local firms could grow more aggressive. More competition could pressure margins or reduce Argan’s win rate — especially if others upgrade talent or adopt better tech.
• Execution & Labor Constraints
A $1.3B+ backlog sounds fantastic… until you remember that it requires thousands of workers, tons of materials, and flawless coordination. The industry faces skilled labor shortages, aging trades, and volatile supply chains. If Argan can’t staff up or a key supplier falters, timelines slip — and profits follow. Managing multiple giant projects at once is a “good problem,” but still a risk.
• Contract Cancellation or Delays
Backlog is not guaranteed revenue. Projects can be paused, re-scoped, or even canceled (sometimes with termination fees, sometimes not enough to cover lost profit). Regulatory issues, financing hiccups, permitting delays — all can slow or shrink the backlog. It’s rare but real, and it’s happened before.
Bottom line: Argan’s risks mostly come from the nature of the EPC world — big projects, big stakes, big swings — plus the long-term shift toward cleaner energy. None of these are deal breakers, and Argan historically manages them extremely well. But they’re essential to understand if you want a balanced view of the investment case.
🔒 The rest of this article is for paid subscribers
If you choose to upgrade, you’ll get access to the full deep dive – including the companies dividend policy and buyback activity, valuation breakdowns, and both the bullish and bearish investment case. In every paid section, I go beyond the headlines and share detailed numbers, scenarios, and outlooks that long-term investors can actually use. It’s where I connect the dots between financial performance, strategy, and what it means for your portfolio.
