

Disclaimer: The information provided in this publication is for educational and informational purposes only and does not constitute financial advice. The content is solely reflective of my personal views and opinions based on my research and is not intended to be used as a basis for investment decisions. While every effort is made to ensure that the information is accurate and up-to-date, the writer makes no representations as to the accuracy, completeness, suitability, or validity of any information in this post and will not be liable for any errors, omissions, or delays in this information or any losses, injuries, or damages arising from its display or use. All readers are advised to conduct their own independent research or consult a professional financial advisor before making any investment decisions. The author is not invested in the mentioned stock.
E-Book and Paperback “Investing in Small-Caps - The ultimate Guide”

Friedrich Vorwerk SE
Europe’s energy transition is often discussed in abstract terms—targets, gigawatts, hydrogen strategies, policy roadmaps. But behind all of that sit very real, very physical assets: pipelines, power cables, converter stations, drilling rigs, and construction crews. None of the transition happens without them.
Friedrich Vorwerk Group SE operates exactly at that interface between policy ambition and physical reality. It’s not a household name, not a tech darling, and not a company that usually trends on social media. Yet over the past two years, it has quietly transformed from a struggling mid-sized contractor into one of the most profitable and fastest-growing energy infrastructure players in Germany—and the stock market has taken notice.
After a difficult 2022–2023 marked by margin pressure and execution issues, Vorwerk delivered a sharp operational turnaround in 2024, followed by explosive growth in 2025. Revenues surged, margins rebounded, cash flows swung dramatically positive, and the balance sheet emerged stronger than ever. The share price followed—rising several hundred percent off its lows and firmly re-rating the company in investors’ minds.
This post takes a deep dive into what’s really going on beneath the surface. We’ll look at how Vorwerk makes money, how its financials evolved through the cycle, what the numbers say about execution quality and cash generation, and whether today’s valuation reflects sober reality—or rising expectations. Along the way, we’ll examine both the bullish and bearish cases, and place Vorwerk in the broader context of Europe’s massive energy infrastructure build-out.
The goal is not to pitch a stock, but to understand a business that sits at the engine room of the energy transition—and to assess whether Friedrich Vorwerk is merely enjoying a cyclical upswing, or genuinely maturing into a long-term compounder.
General Description
Friedrich Vorwerk Group SE is a German engineering specialist at the heart of Europe’s energy transition. Simply put, Vorwerk designs, builds, and maintains the infrastructure that moves energy—pipelines, underground power cables, and complex systems that transport gas, electricity, and hydrogen from producers to consumers.
The company operates across three critical markets:
Natural gas infrastructure, from LNG import pipelines and compressor stations to local distribution networks
Electricity grids, including high-voltage underground cables and converter stations that connect renewable power
Clean hydrogen, with electrolyzer installations and the conversion of existing gas pipelines
With over 60 years of experience in infrastructure construction, Vorwerk delivers turnkey solutions across the full project lifecycle—from engineering and construction to long-term maintenance. Its deep in-house expertise and proprietary pipeline technologies have made it a trusted contractor for complex, mission-critical energy projects.
Headquartered in Tostedt, Germany, and listed on the Frankfurt Stock Exchange (Xetra: VH2), Vorwerk punches above its weight. Despite its modest size, it plays a central role in Germany’s energy modernization—from new gas pipelines and electricity “power highways” like SuedLink to future hydrogen networks.
The result: a classic “hidden champion”—low profile, highly specialized, and positioned right at the intersection of some of the biggest structural trends in energy today.
Latest Financials (2024 & YTD 2025)
After a rough patch in 2022–2023, Friedrich Vorwerk’s financials came roaring back in 2024—and the momentum only strengthened in 2025. Revenue surged 33% in 2024 to €498.3 million, marking a clear return to growth and unlocking a sharp jump in profitability.
The real headline: net income more than tripled to €35.8 million, driven by higher project volumes and much stronger execution margins. And then things really took off. In the first nine months of 2025, revenue climbed 49% year-on-year, while EBITDA more than doubled.
Q3 2025 was a blowout quarter: revenue topped €200 million for the first time, EBITDA margins hit an eye-catching 25.4%, and management responded by raising full-year guidance. Vorwerk now expects €650–680 million in 2025 revenue and an EBITDA margin of 20–22%—implying around €140 million in EBITDA, a ~75% increase vs. 2024 and by far the strongest result in the company’s history.
Visibility remains high thanks to a €1.1 billion order backlog, even though new order intake dipped temporarily in early 2025 due to timing effects. Importantly, the balance sheet is rock-solid: €111 million in net cash gives Vorwerk ample firepower to fund future growth.
Bottom line: accelerating growth, expanding margins, and a fortress balance sheet. The numbers paint a picture of a company firing on all cylinders—and investors have clearly started to notice.
Key financials
Friedrich Vorwerk’s recent business performance tells a story of cyclicality, execution stress, and then a very sharp operational recovery. When you line up the income statement, profitability ratios, cash flows, and balance sheet metrics, a clear pattern emerges: 2022–2023 were the digestion years, and 2024 marks a decisive inflection point.
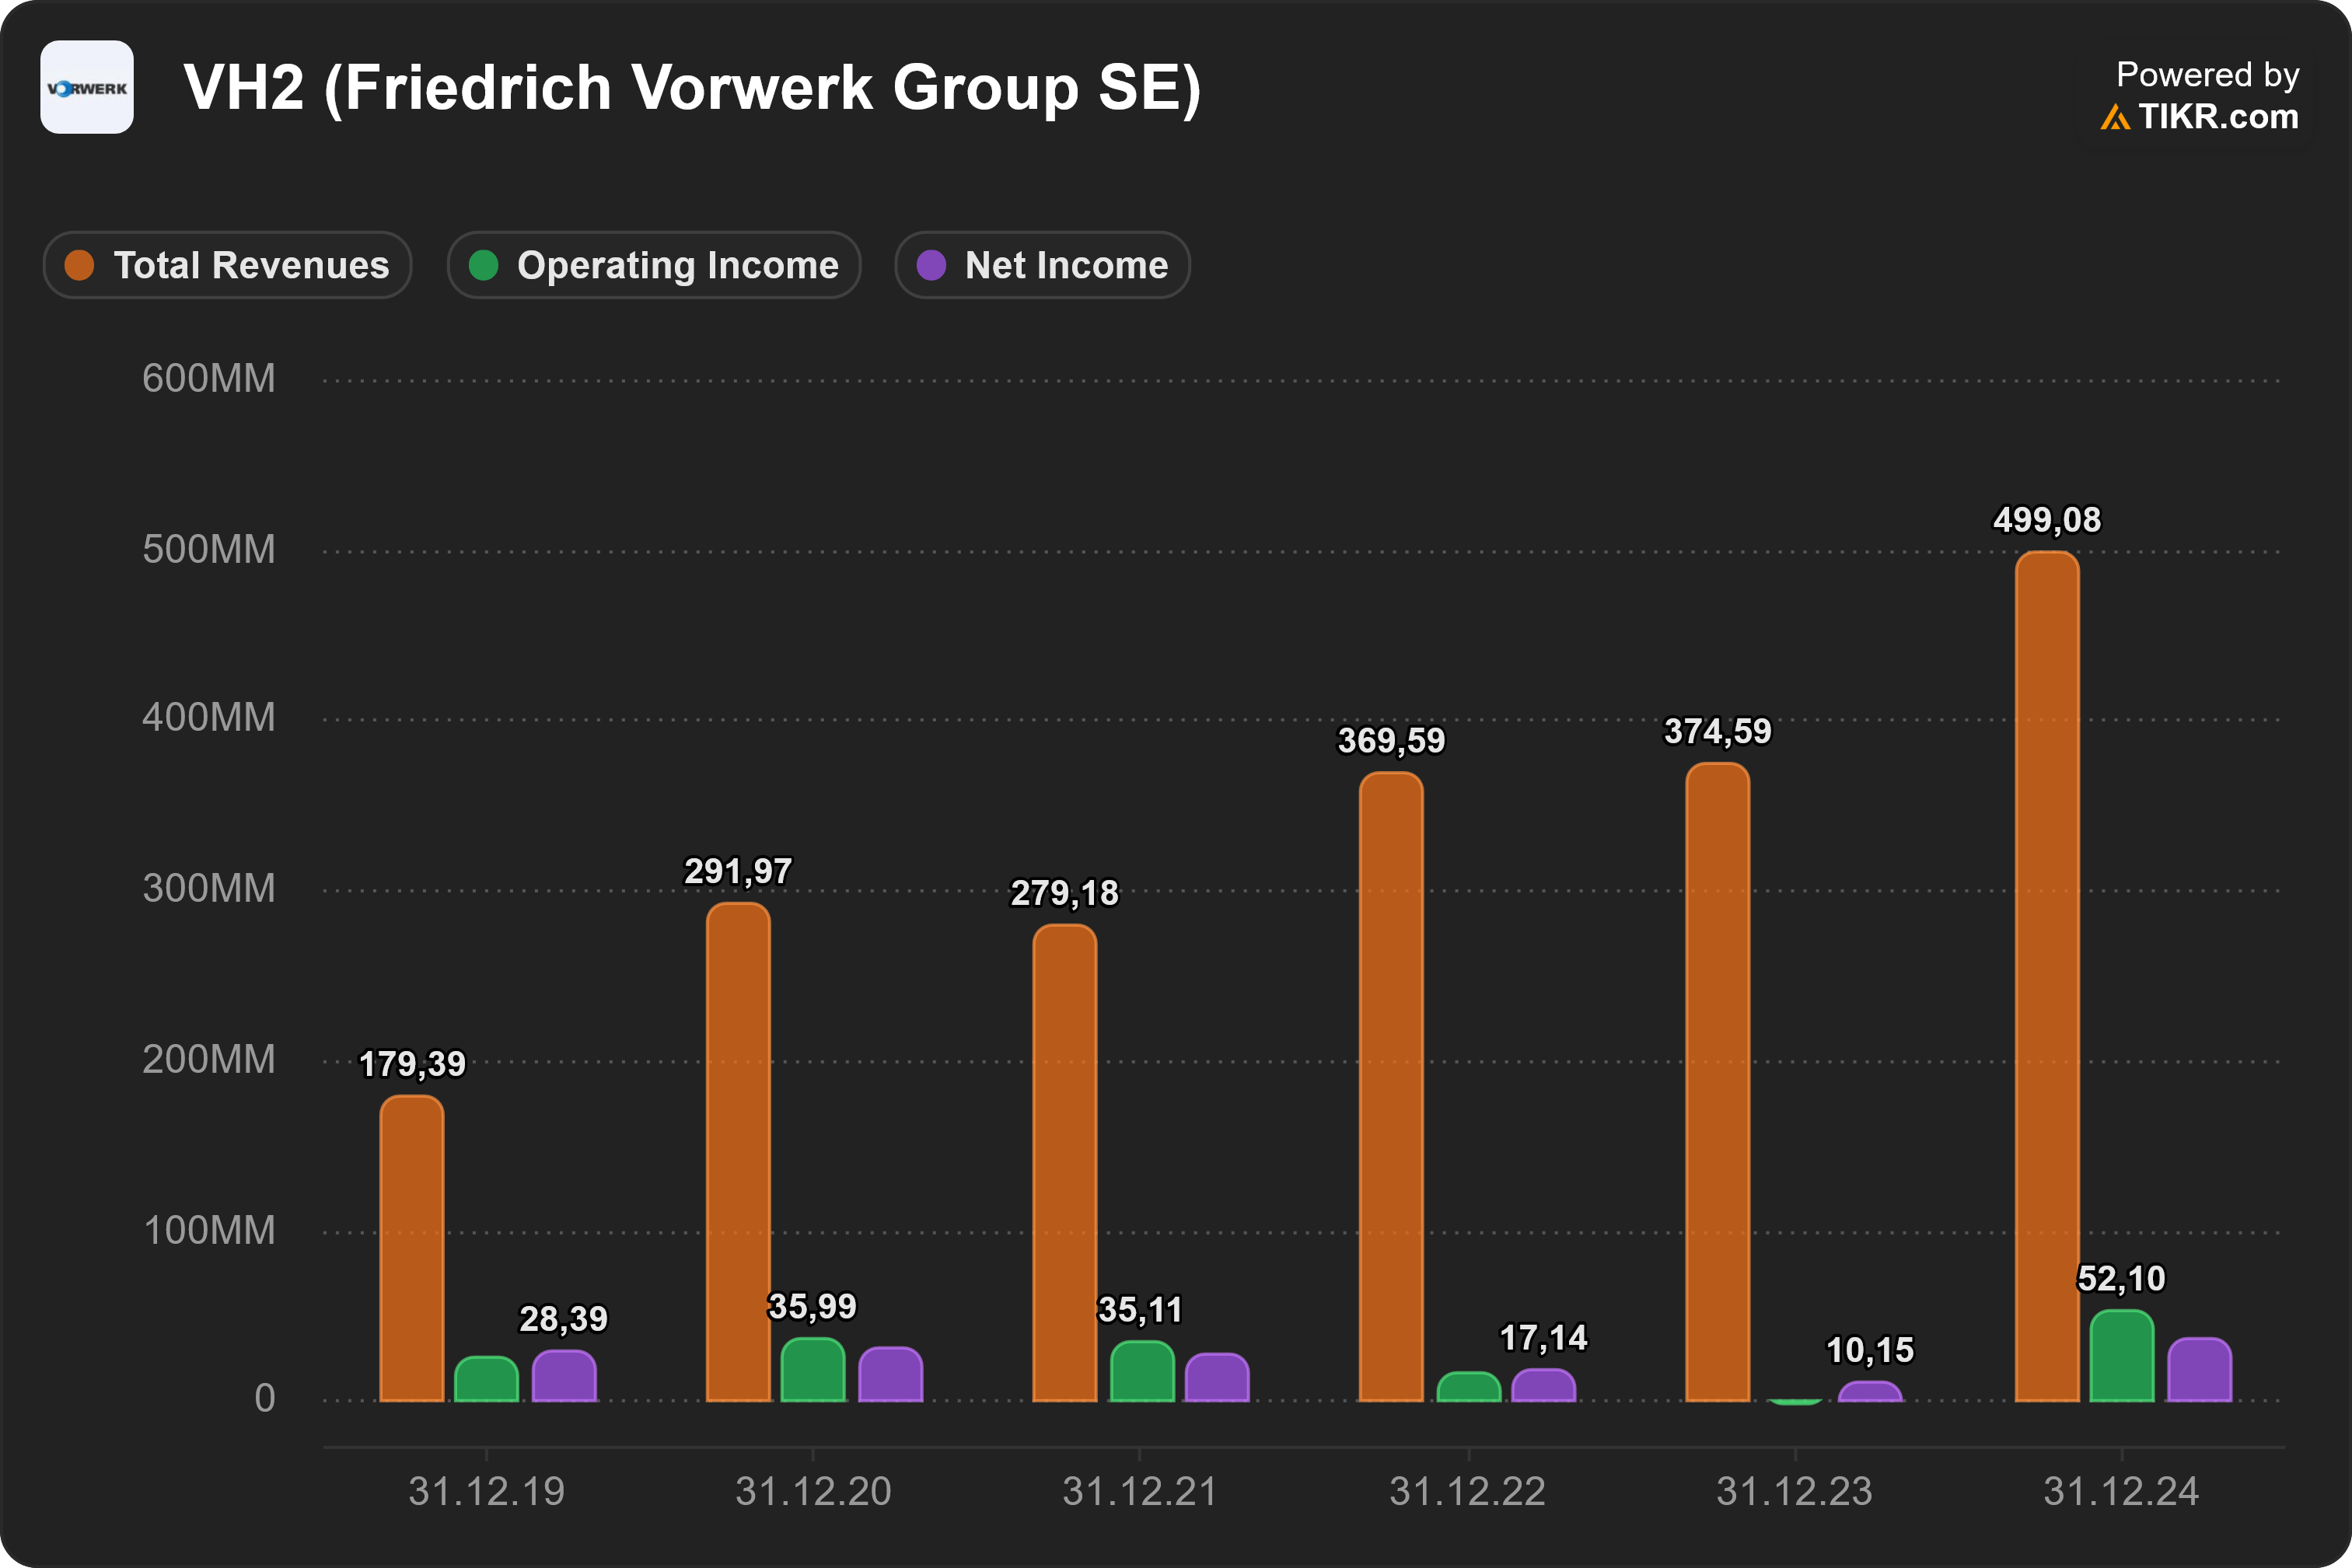
Starting with the revenue, operating income, and net income development, the top-line trajectory is broadly upward, but far from linear. Revenues grew from roughly €180 million in 2019 to nearly €300 million in 2020, dipped slightly in 2021, and then resumed growth into €370–375 million in 2022–2023. The real breakout came in 2024, when revenues jumped to just under €500 million, the strongest year in the company’s history. This reflects both higher project volumes and the ramp-up of large electricity and pipeline contracts.
What’s more interesting is what happened below the revenue line. Operating income and net income peaked early (2019–2021), then collapsed in 2022–2023 before rebounding strongly in 2024. In 2022, operating income fell sharply despite higher revenues, and by 2023 profitability nearly vanished. This was not a demand problem—it was an execution and margin problem, driven by fixed-price contracts, cost inflation, and complex project structures. In 2024, however, operating income surged to over €50 million, with net income following suit. That gap between revenue growth and profit recovery underlines an important point: Vorwerk didn’t just grow again in 2024—it fixed its execution.
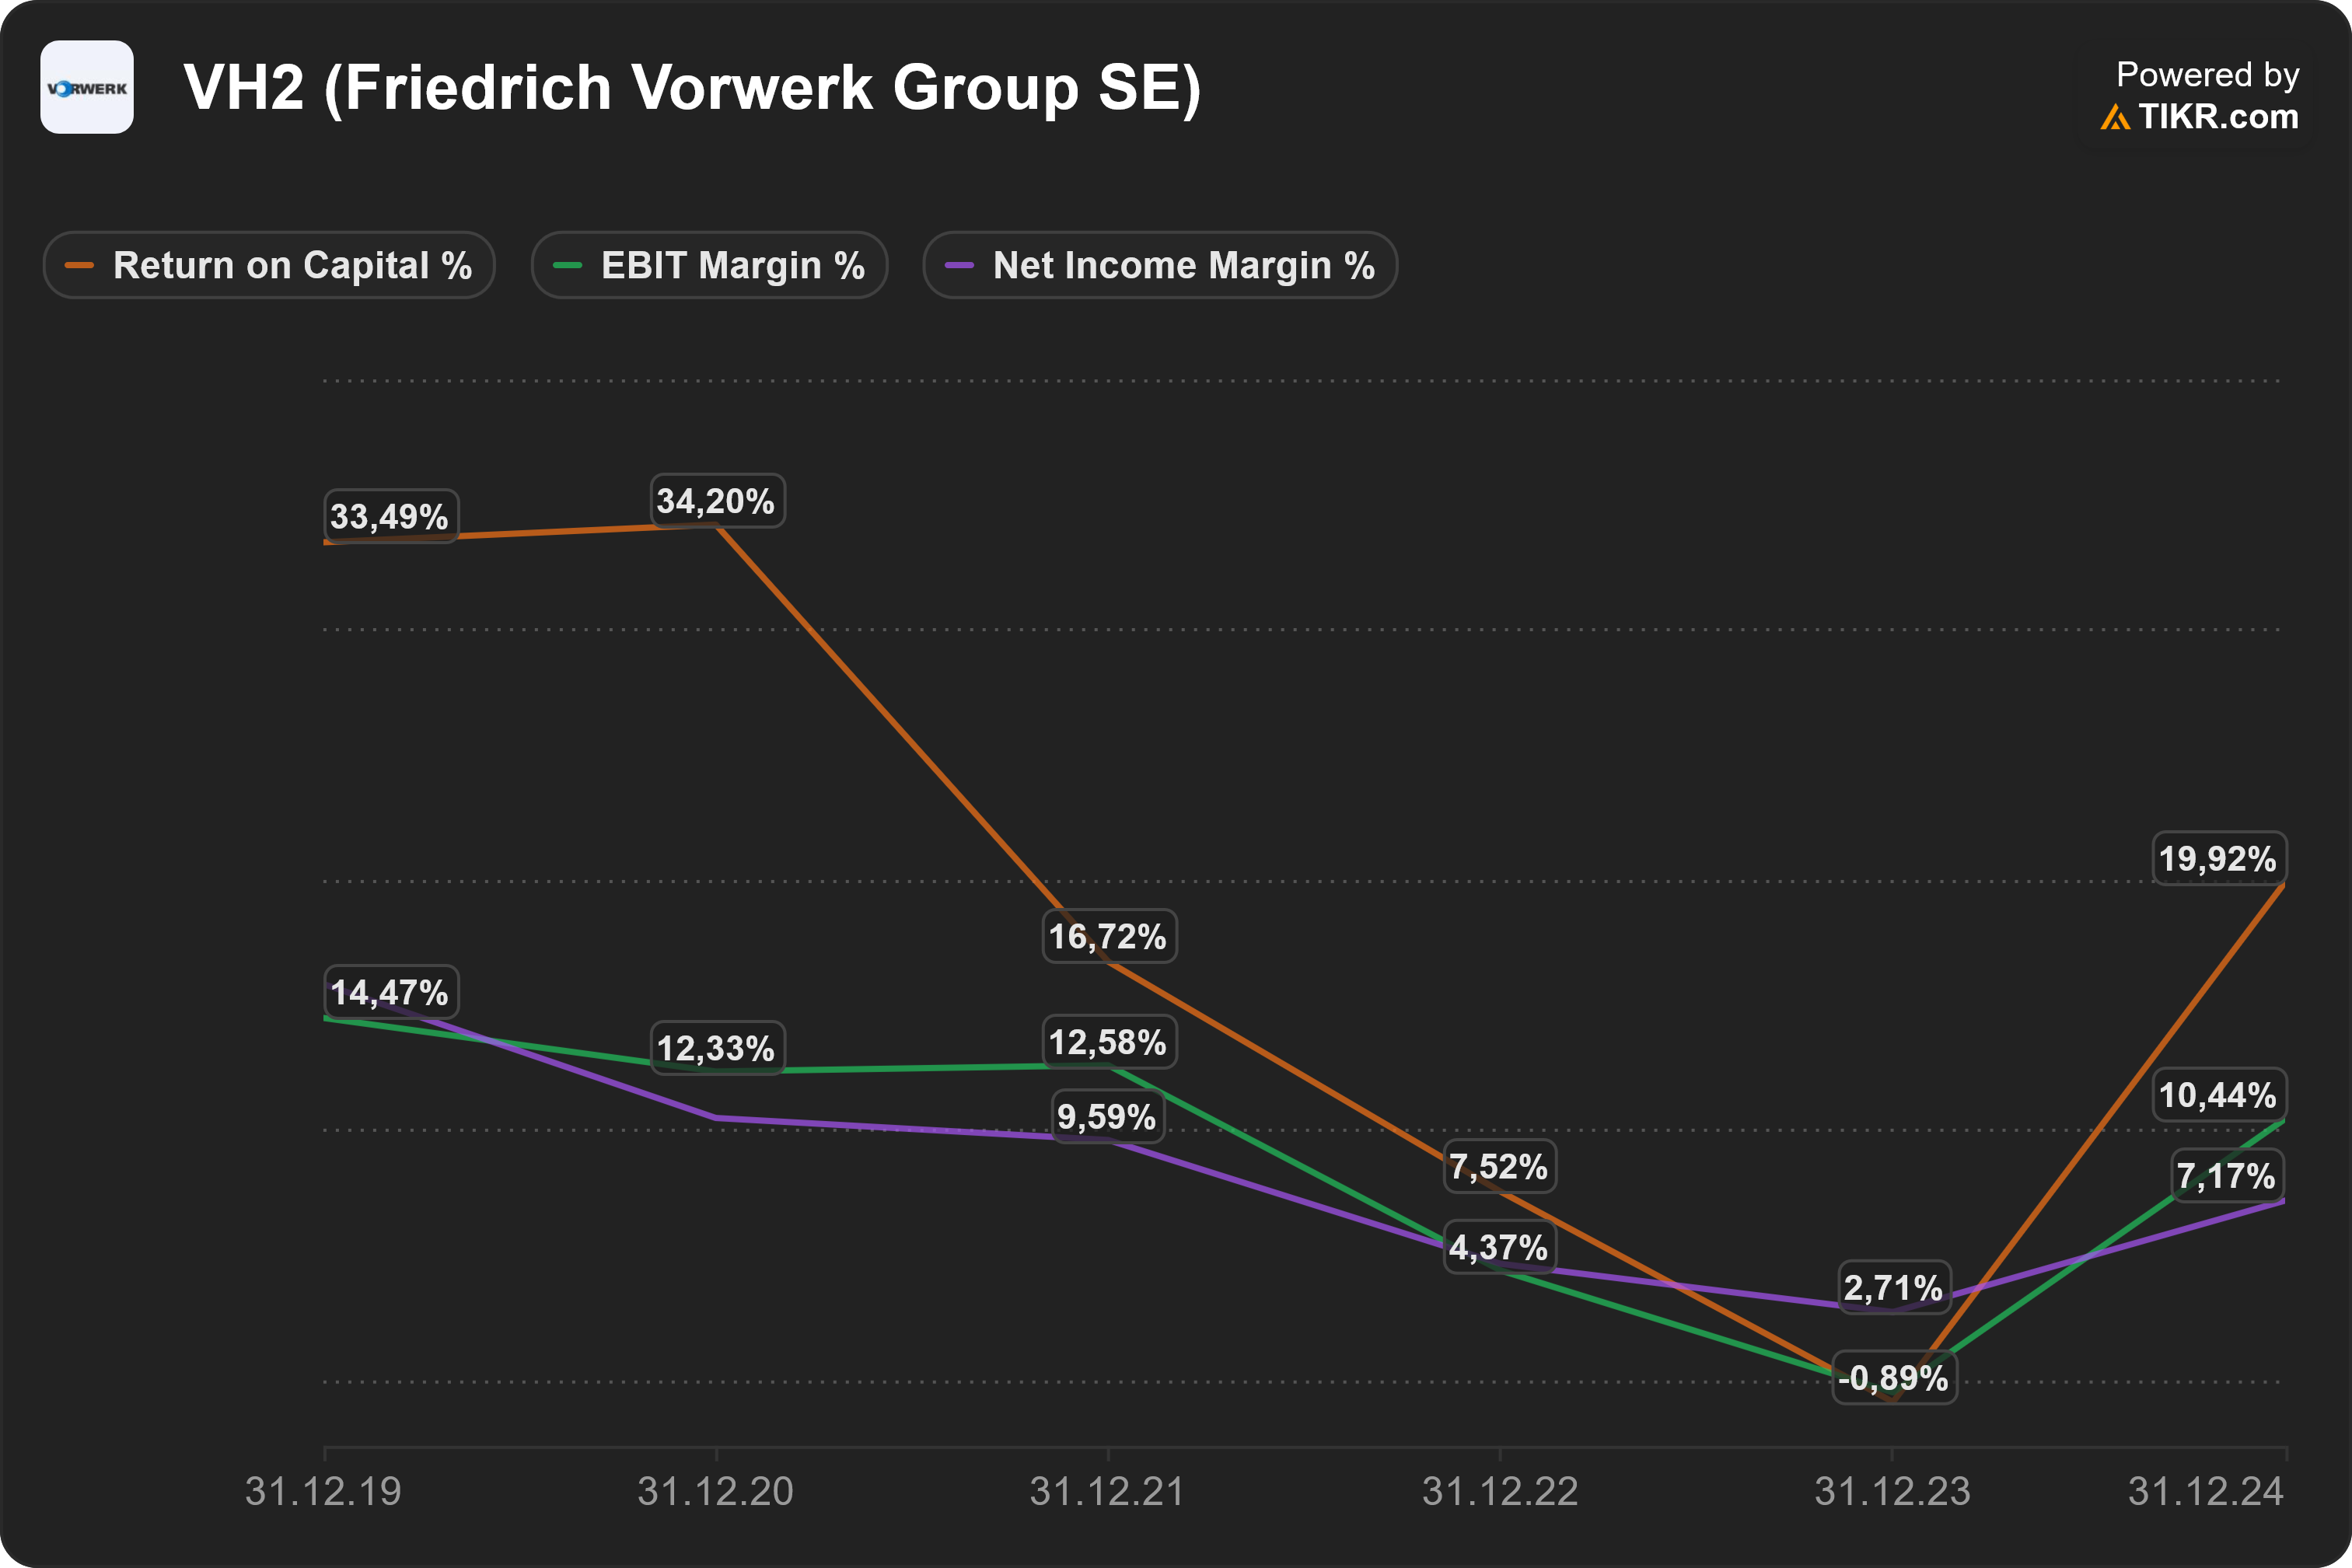
This is reinforced when you look at the profitability and efficiency ratios. Return on capital employed (ROCE) was extremely strong in 2019–2020, above 30%, reflecting a smaller project base and very efficient capital usage. As the company scaled up, ROCE fell steadily, bottoming out in 2023 at barely above zero. EBIT and net income margins show the same pattern: double-digit margins early on, then a steady erosion through 2021–2023, before a clear rebound in 2024. EBIT margin recovered into the low double digits, and net margin moved back into healthy territory.
The key takeaway here is not that Vorwerk suddenly became “high margin” again, but that 2023 marked the low point. The ratio recovery in 2024 suggests that the company has learned how to manage larger, more complex infrastructure projects without destroying profitability. This matters enormously for investors, because it indicates that scale is no longer the enemy of returns.
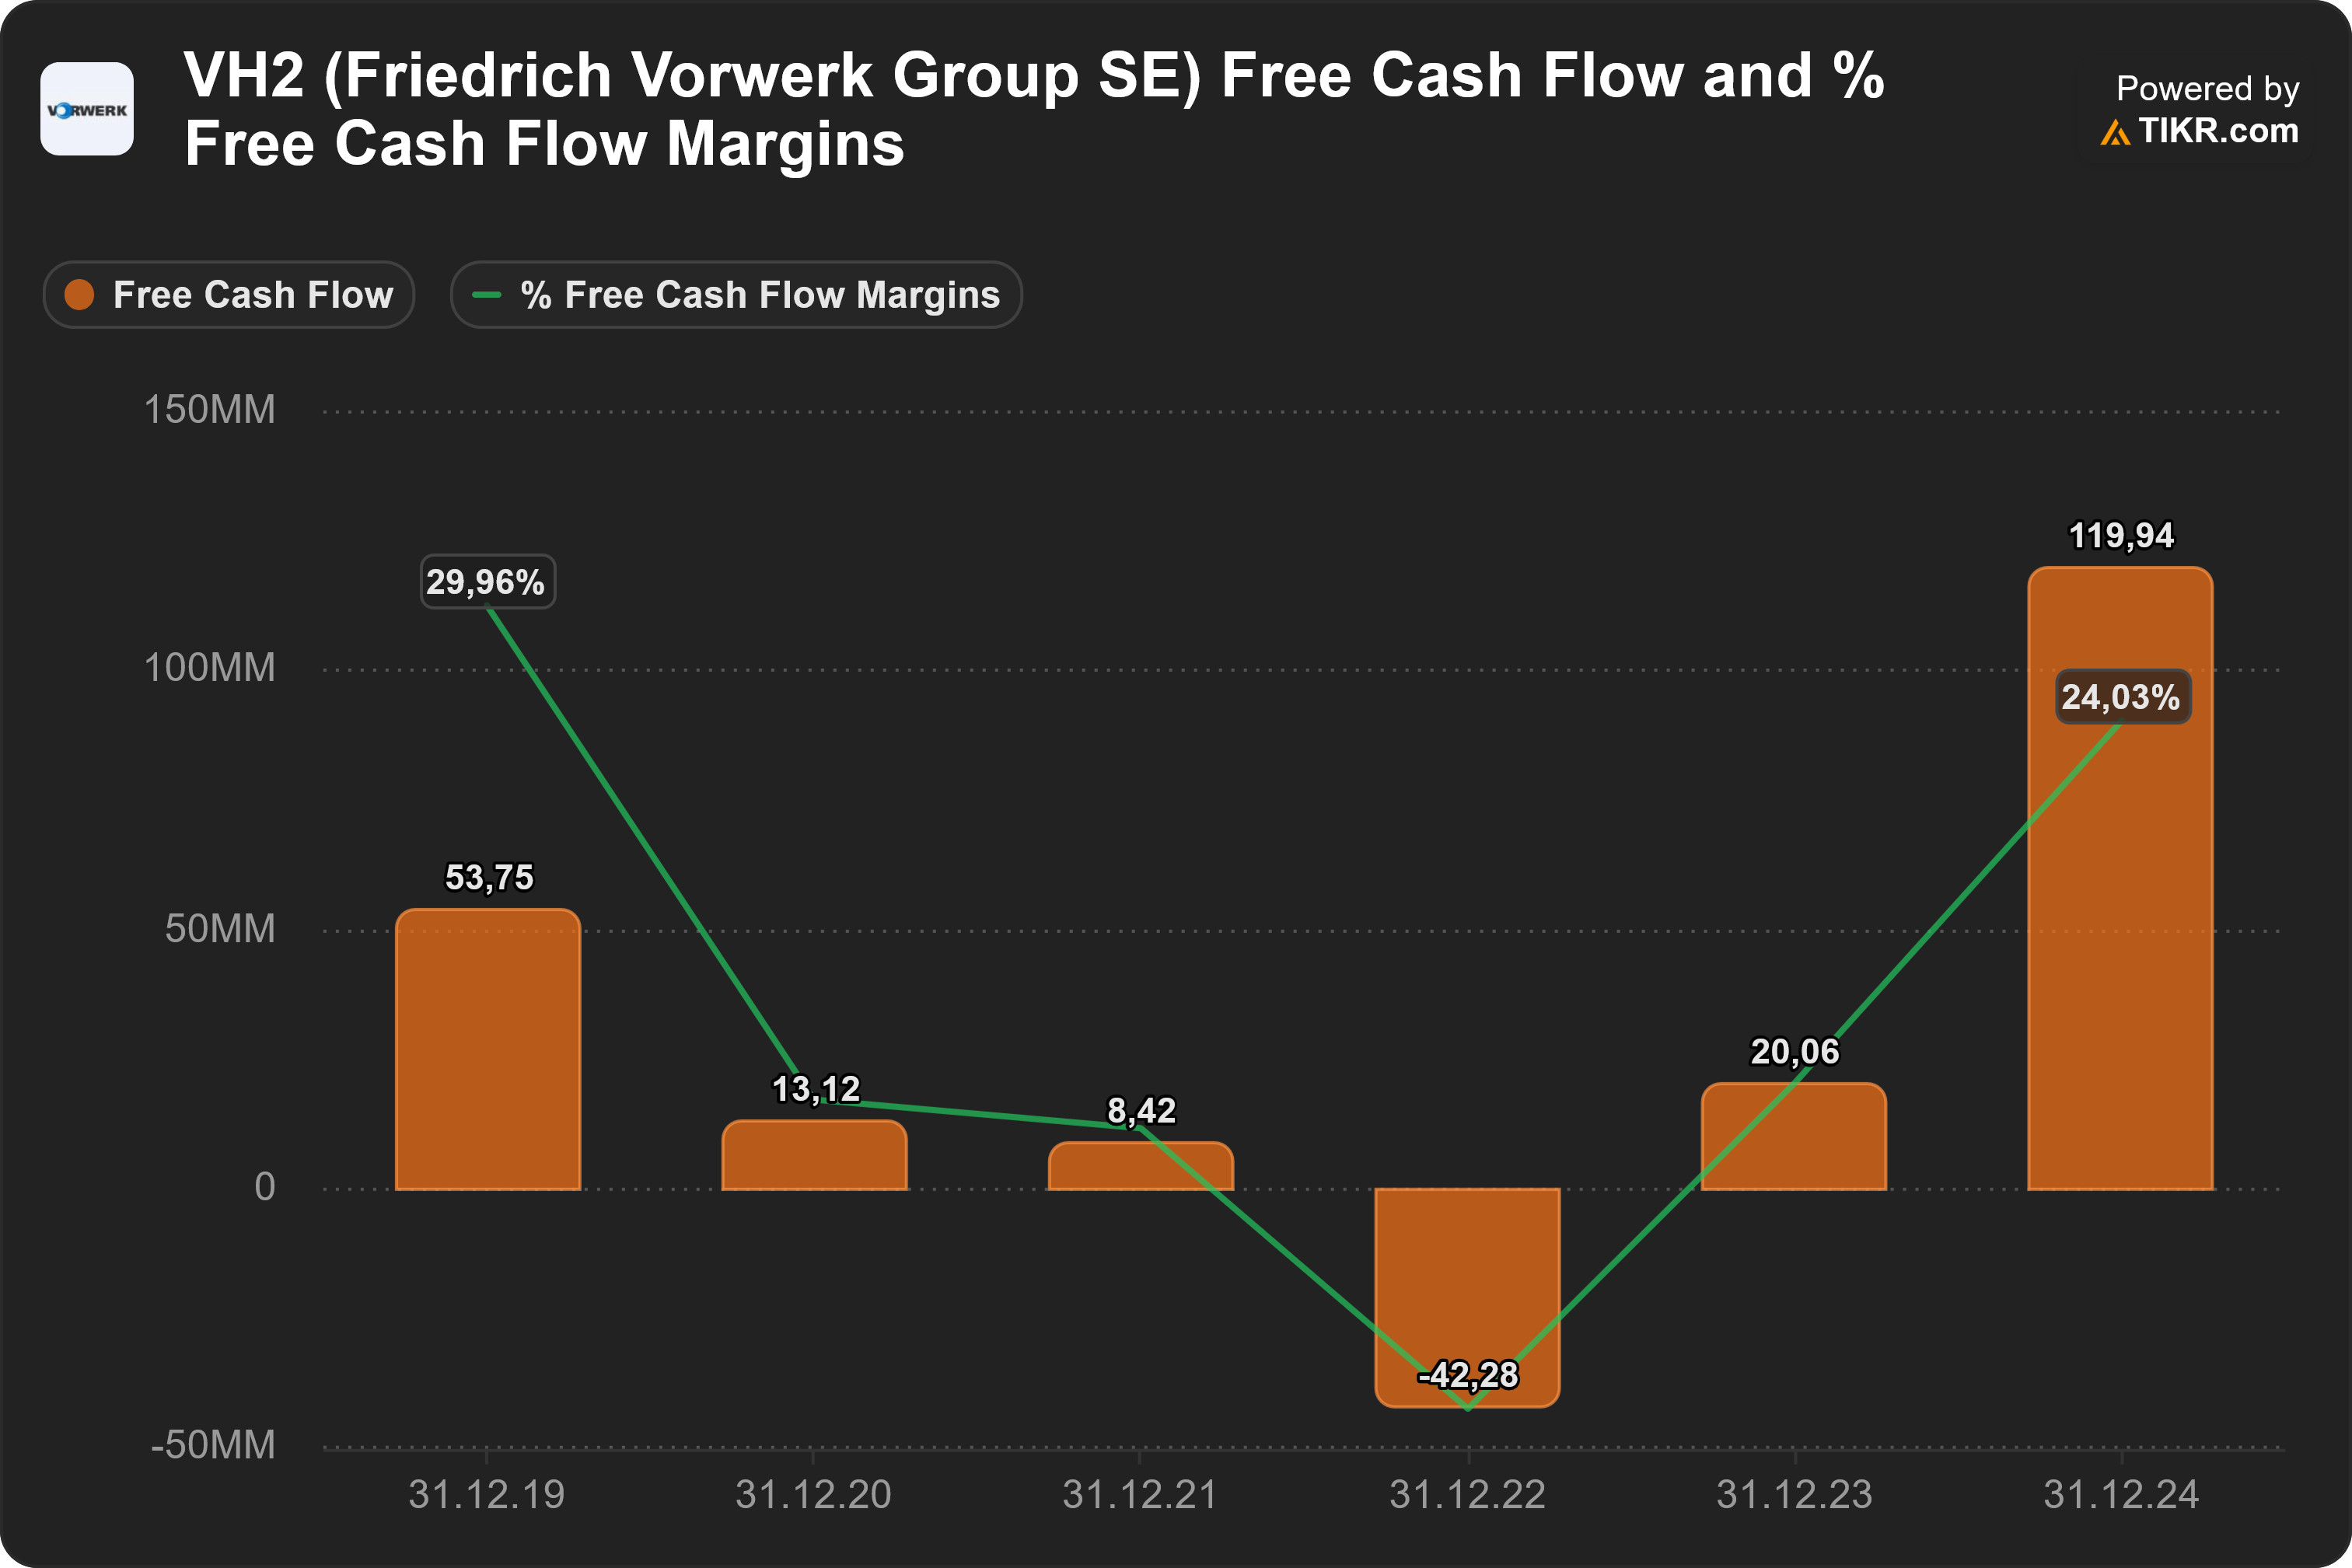
The cash flow chart adds another crucial layer. Free cash flow has been volatile by design, not by accident. Vorwerk generated strong free cash flow in 2019, then much lower but still positive figures in 2020 and 2021. In 2022, free cash flow turned deeply negative, reflecting heavy working capital investment as large projects ramped up. This is exactly what you would expect from a project-driven EPC-style business entering a growth phase.
What’s striking is the reversal. In 2023, free cash flow turned positive again, and in 2024 it exploded to roughly €120 million, with a free cash flow margin north of 20%. That is an exceptionally strong conversion rate and tells us two things: first, projects are now being completed and billed, releasing working capital; second, profitability improvements are translating into real cash, not just accounting earnings. This validates the quality of the 2024 earnings in a way income statement numbers alone cannot.
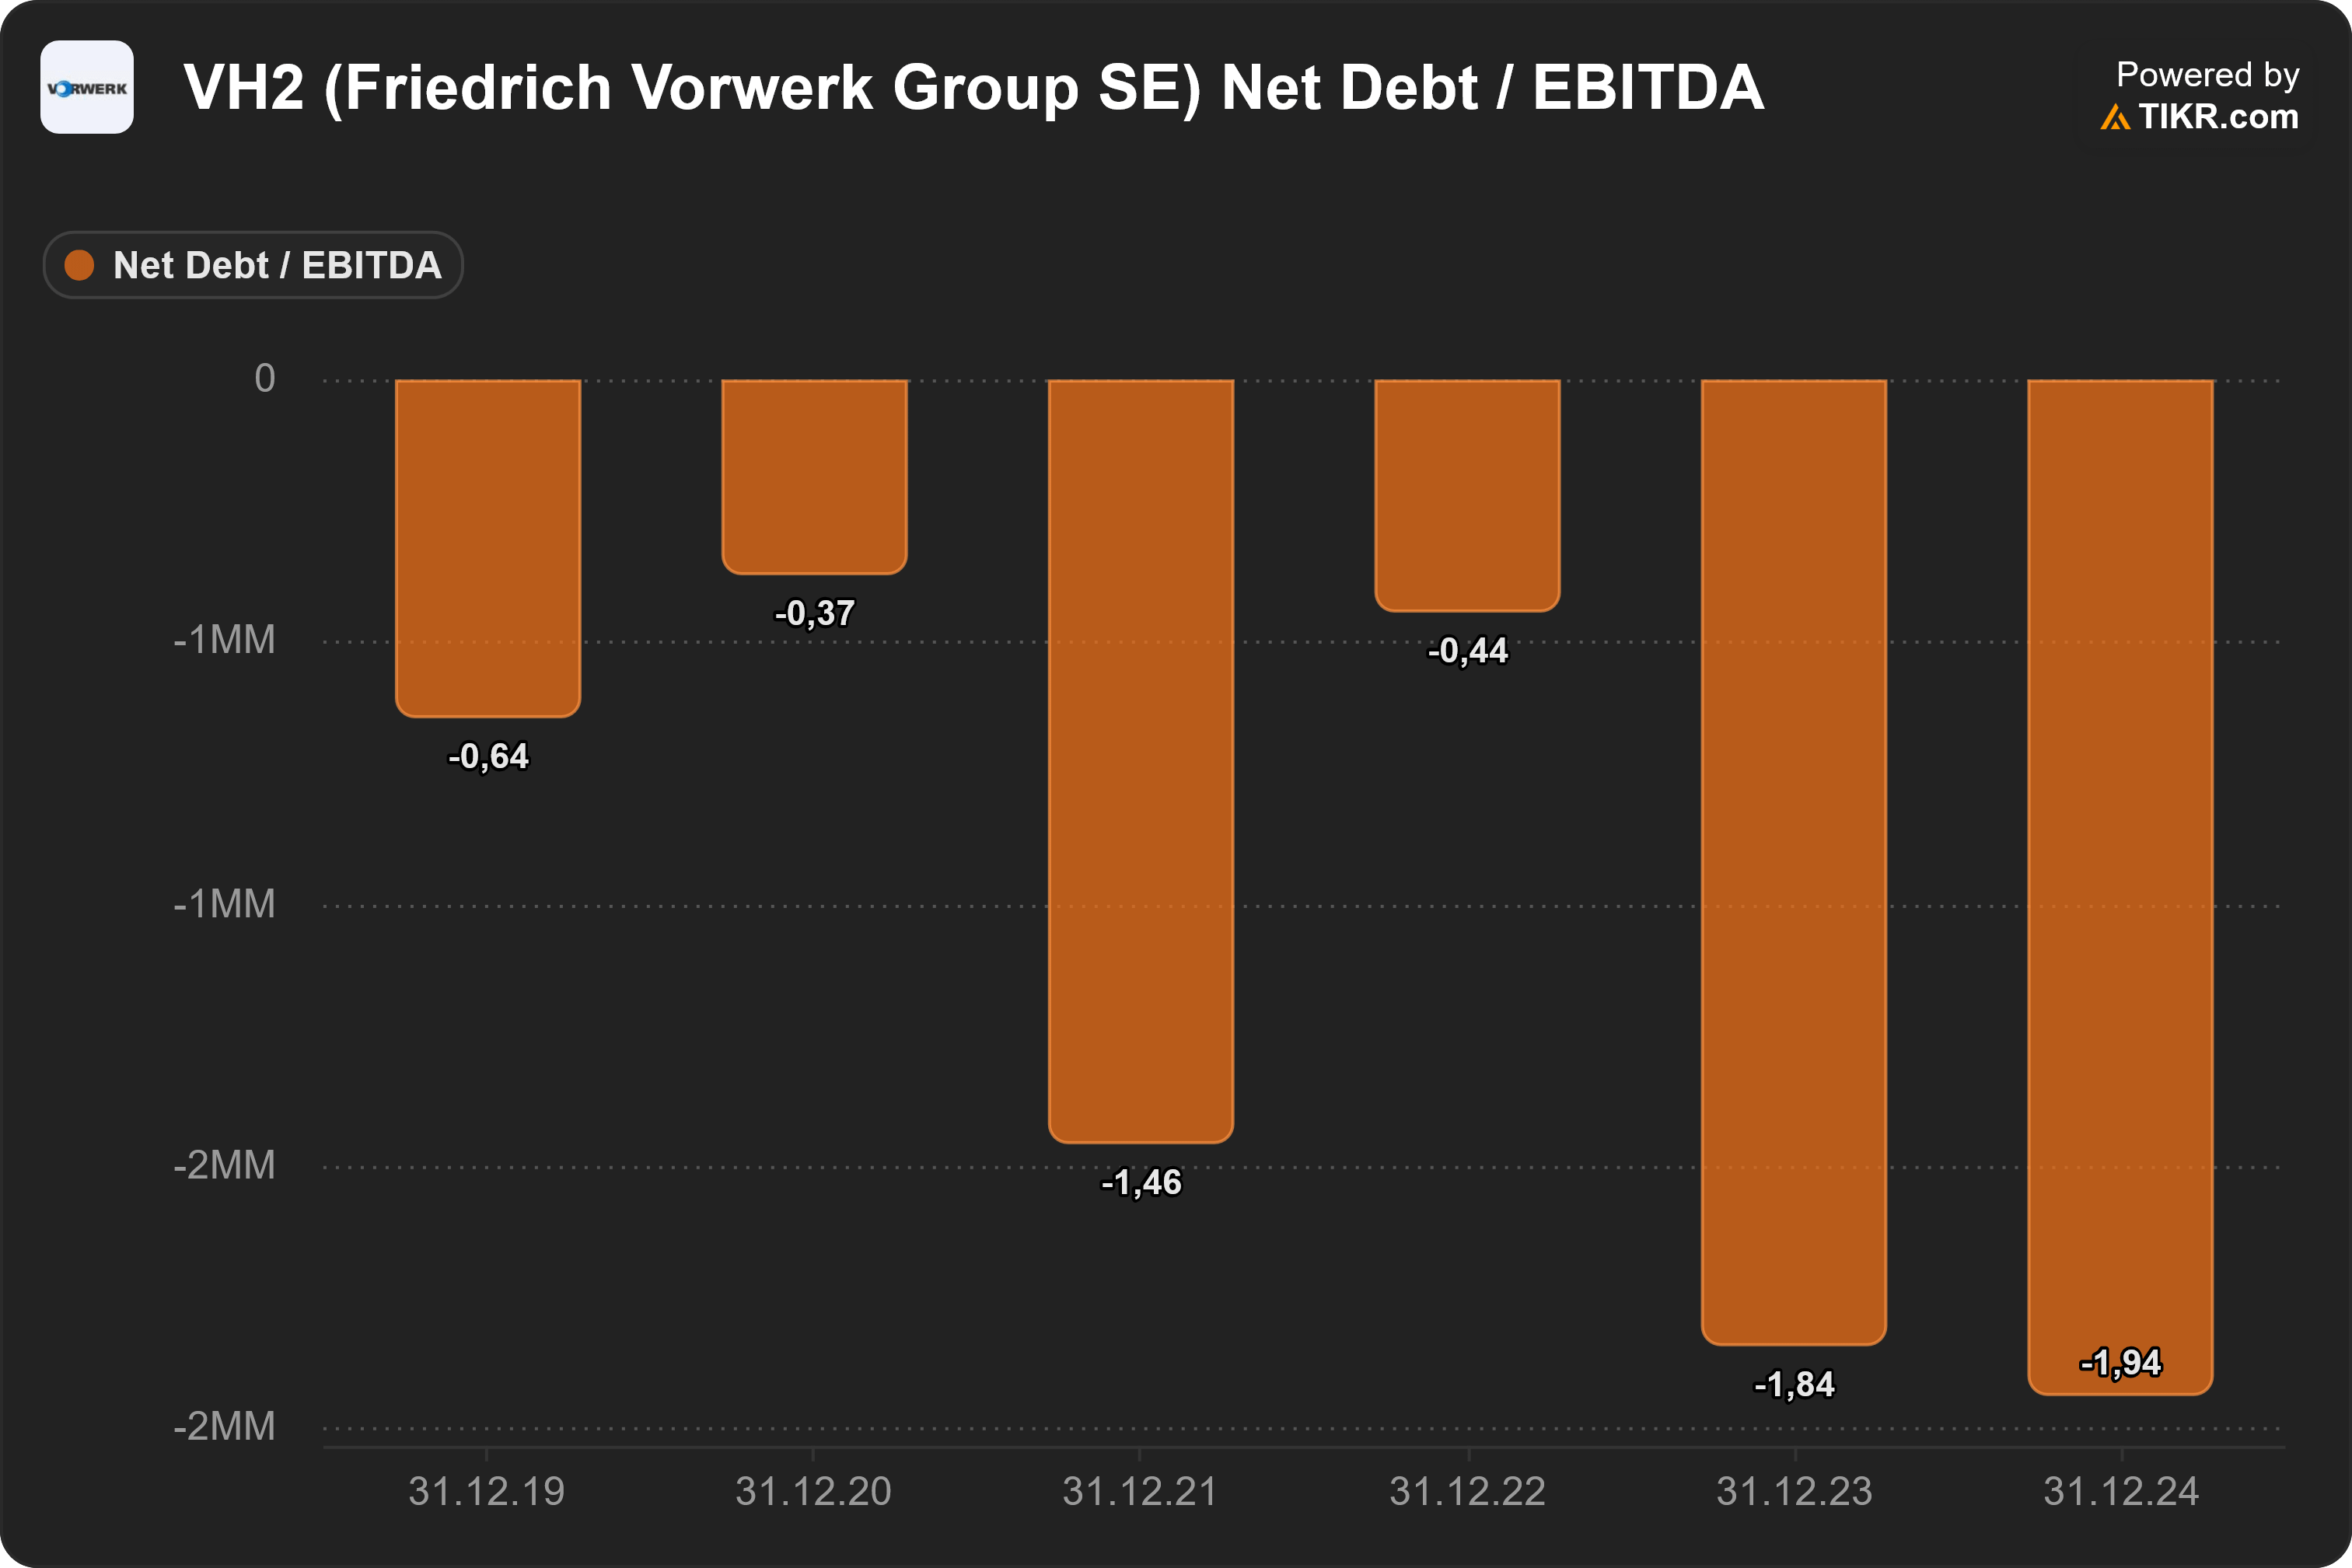
Finally, the net debt / EBITDA chart ties everything together. Vorwerk has been in a net cash position throughout the entire period, with net debt to EBITDA consistently negative. Even during the difficult 2022–2023 phase, leverage was never a concern. In fact, as EBITDA rebounded in 2024, the net cash position deepened further, pushing net debt / EBITDA close to -2×. This is a very conservative balance sheet for a company operating in large-scale infrastructure construction.
This financial structure gives Vorwerk strategic optionality. It can absorb project volatility, pre-finance working capital, invest in equipment and technology, and still remain financially robust. Importantly, it also makes Vorwerk a credible partner for very large projects, where counterparties care deeply about balance sheet strength.
Putting all four charts together, the picture is coherent. Vorwerk went through a classic scaling valley: revenues rose first, margins collapsed, cash flows turned negative, and returns suffered. Then, in 2024, the business emerged on the other side with higher scale, restored profitability, strong cash generation, and an even stronger balance sheet. This is not a story of linear growth—it’s a story of operational maturation.
Vorwerk is no longer just a growth story riding the energy transition. It is increasingly a cash-generative, execution-proven infrastructure contractor—and that shift is clearly visible across revenues, margins, cash flows, and leverage.
Business Model Explained
Friedrich Vorwerk’s business model is built around one idea: being a true one-stop shop for energy infrastructure. The company operates across four closely linked segments—Natural Gas, Electricity, Clean Hydrogen, and Adjacent Opportunities—but in reality these silos blur. Vorwerk’s strength lies in delivering integrated, turnkey projects that span multiple technologies under a single accountable contractor.
Natural Gas Infrastructure
This is Vorwerk’s traditional backbone. The company designs, builds, and upgrades large-diameter pipelines, compressor stations, storage connections, and city-gate facilities. If gas needs to move from an LNG terminal to industry, Vorwerk can handle the entire chain. Importantly, many of these assets are already being prepared for biogas and future hydrogen use, extending their relevance well beyond fossil gas.
Electricity Grid Infrastructure
Germany’s energy transition requires massive underground high-voltage “electricity highways” to move wind power from north to south—and this is squarely in Vorwerk’s wheelhouse. The company installs HVDC underground cables, performs complex landfall drilling for offshore wind, and builds converter and transformer stations. Flagship projects like SuedLink and Corridor A-Nord highlight Vorwerk’s edge in technically demanding, environmentally sensitive construction, often delivered via consortia due to their scale.
Clean Hydrogen & Energy Transformation
Vorwerk is actively positioning for the hydrogen economy. Today, that means installing electrolyzers (1–5 MW systems), engineering hydrogen production plants, and repurposing existing gas pipelines for hydrogen transport. The segment also includes adjacent niches such as biogas upgrading and CO₂ transport infrastructure for carbon capture—new markets that reuse the same pipeline and plant expertise.
Services & Maintenance
After construction, Vorwerk often stays on as a long-term service partner, providing maintenance, repairs, and operational support. While still a smaller share of revenue, this creates recurring income and sticky customer relationships.
What really differentiates Vorwerk
The core advantage is deep vertical integration. Vorwerk does almost everything in-house: engineering, drilling, welding, electrical work, and even proprietary technology. A standout example is the PX2 automated welding system, which boosts productivity and quality—and has already opened doors in new European markets.
This full-value-chain approach reduces interfaces and risk for customers while improving execution efficiency. The flip side: the business is resource- and working-capital intensive, making project management, cost control, and skilled labor availability critical. Contracts are often fixed-price, so execution discipline directly determines margins.
For mega-projects, Vorwerk frequently joins joint ventures or consortia, allowing participation in billion-euro pipelines and HVDC corridors while sharing risk and capital needs—albeit sometimes at lower margins.
Bottom line: Vorwerk is leveraging specialized engineering know-how and niche technology to capture a growing slice of Europe’s massive energy infrastructure spend. It’s a high-growth, infrastructure-as-a-service model, tightly linked to the energy transition—and execution is everything.
Strengths and Weaknesses
Strengths
• Integrated energy expertise
Vorwerk combines deep technical know-how across gas, electricity, and hydrogen with proprietary technology like its PX2 automated welding system. Few peers of similar size can plan, build, and service complex energy infrastructure end-to-end, making Vorwerk a highly attractive one-stop contractor for large, technically demanding projects.
• Powerful secular growth tailwinds
The company sits squarely in the path of Europe’s energy transition and energy-security push. Grid upgrades for renewables, hydrogen networks, LNG import infrastructure, and even CO₂ transport pipelines all require exactly Vorwerk’s capabilities. This infrastructure build-out is expected to last well over a decade, giving Vorwerk a long, visible growth runway.
• Strong order backlog and visibility
With an order backlog of ~€1.1 billion—roughly two years of revenue—Vorwerk enjoys excellent forward visibility. Large, multi-year projects like Corridor A-Nord underpin future sales and reflect strong customer trust in a highly competitive market.
• Rock-solid balance sheet
Vorwerk operates with net cash of over €100 million, providing resilience and strategic flexibility. The company can absorb project timing swings, invest in new technology and equipment, and pursue M&A or joint ventures without financial stress—something management explicitly sees as a growth lever.
• Rapidly improving profitability
After earlier margin pressure, profitability has inflected sharply upward. EBITDA margins reached ~16% in 2024 and over 25% in Q3 2025, with returns on capital rising. This suggests Vorwerk is scaling up execution quality—and if margins hold, earnings should outpace revenue growth.
Weaknesses
• Limited scale and capacity constraints
Despite its success, Vorwerk remains a mid-sized player with around 2,000 employees. The largest infrastructure projects still require consortia or joint ventures, which dilute revenue and margins. Rapid growth also puts pressure on hiring, training, and equipment availability.
• High execution and project concentration risk
Revenue is often concentrated in a small number of mega-projects, making execution critical. Delays, cost overruns, or permitting issues can materially impact results. For example, parts of the A-Nord HVDC project have faced approval delays, highlighting the risk of lumpy earnings and timing volatility.
• Dependence on regulation and politics
Much of Vorwerk’s work depends on government policy, permits, and subsidies. Regulatory delays can push contracts back, while changes in hydrogen rules or infrastructure priorities could slow growth. These risks are largely outside management’s control.
• Exposure to cost inflation and labor shortages
Fixed-price contracts leave Vorwerk vulnerable to rising material costs and skilled labor shortages. While the company is hiring aggressively, a sustained lack of qualified engineers or technicians could constrain growth or pressure margins if execution capacity lags demand.
• Execution risk in new growth areas
Hydrogen, CO₂ transport, and new geographies are promising but still unproven. Investments in R&D, technology, and acquisitions may take time to pay off, and international expansion adds complexity. There is an element of “learning while scaling” as Vorwerk moves beyond its traditional core.
Dividends and Share Buybacks
Vorwerk’s shareholder return policy has been deliberately conservative. Since its 2021 IPO, the company has paid only modest dividends, recommending €0.12 per share for both 2022 and 2023. That translates into a negligible yield and a very low payout ratio, reflecting a clear choice: reinvest profits to fuel growth rather than pay them out. Management explicitly stated that retained earnings are being carried forward to support expansion.
Despite its strong cash position, Vorwerk has not executed any share buybacks. While the company has authorization to repurchase up to 10% of its shares, management has chosen not to use it. The rationale is straightforward. According to the CFO, capital is prioritized for organic growth investments (machinery, capacity, working capital), potential strategic acquisitions, and maintaining a rock-solid balance sheet—an important signal of reliability when bidding for large infrastructure contracts. Buybacks, for now, are clearly not a priority.
That said, dividends are set to rise. While there is no fixed payout ratio, management has indicated that the next dividend will reflect the sharp increase in 2024 profits. The yield may still be modest, but the absolute payout should move meaningfully above €0.12.
Bottom line: Vorwerk’s capital allocation is firmly growth-first. Shareholders get a small but growing dividend, no buybacks for now, and a company that is reinvesting at high returns while avoiding balance-sheet risk. For long-term investors, this discipline is attractive—as long as reinvested cash continues to deliver the strong growth currently on display.
Stock Valuation
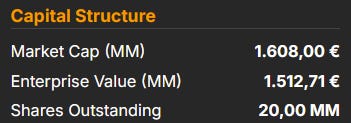
At €80 per share, Friedrich Vorwerk is firmly in re-rated territory. The market no longer treats it as a volatile project contractor, but as a structural beneficiary of Europe’s energy infrastructure cycle. Looking at NTM normalized P/E and EV/EBIT, today’s valuation is demanding—but not detached from reality.
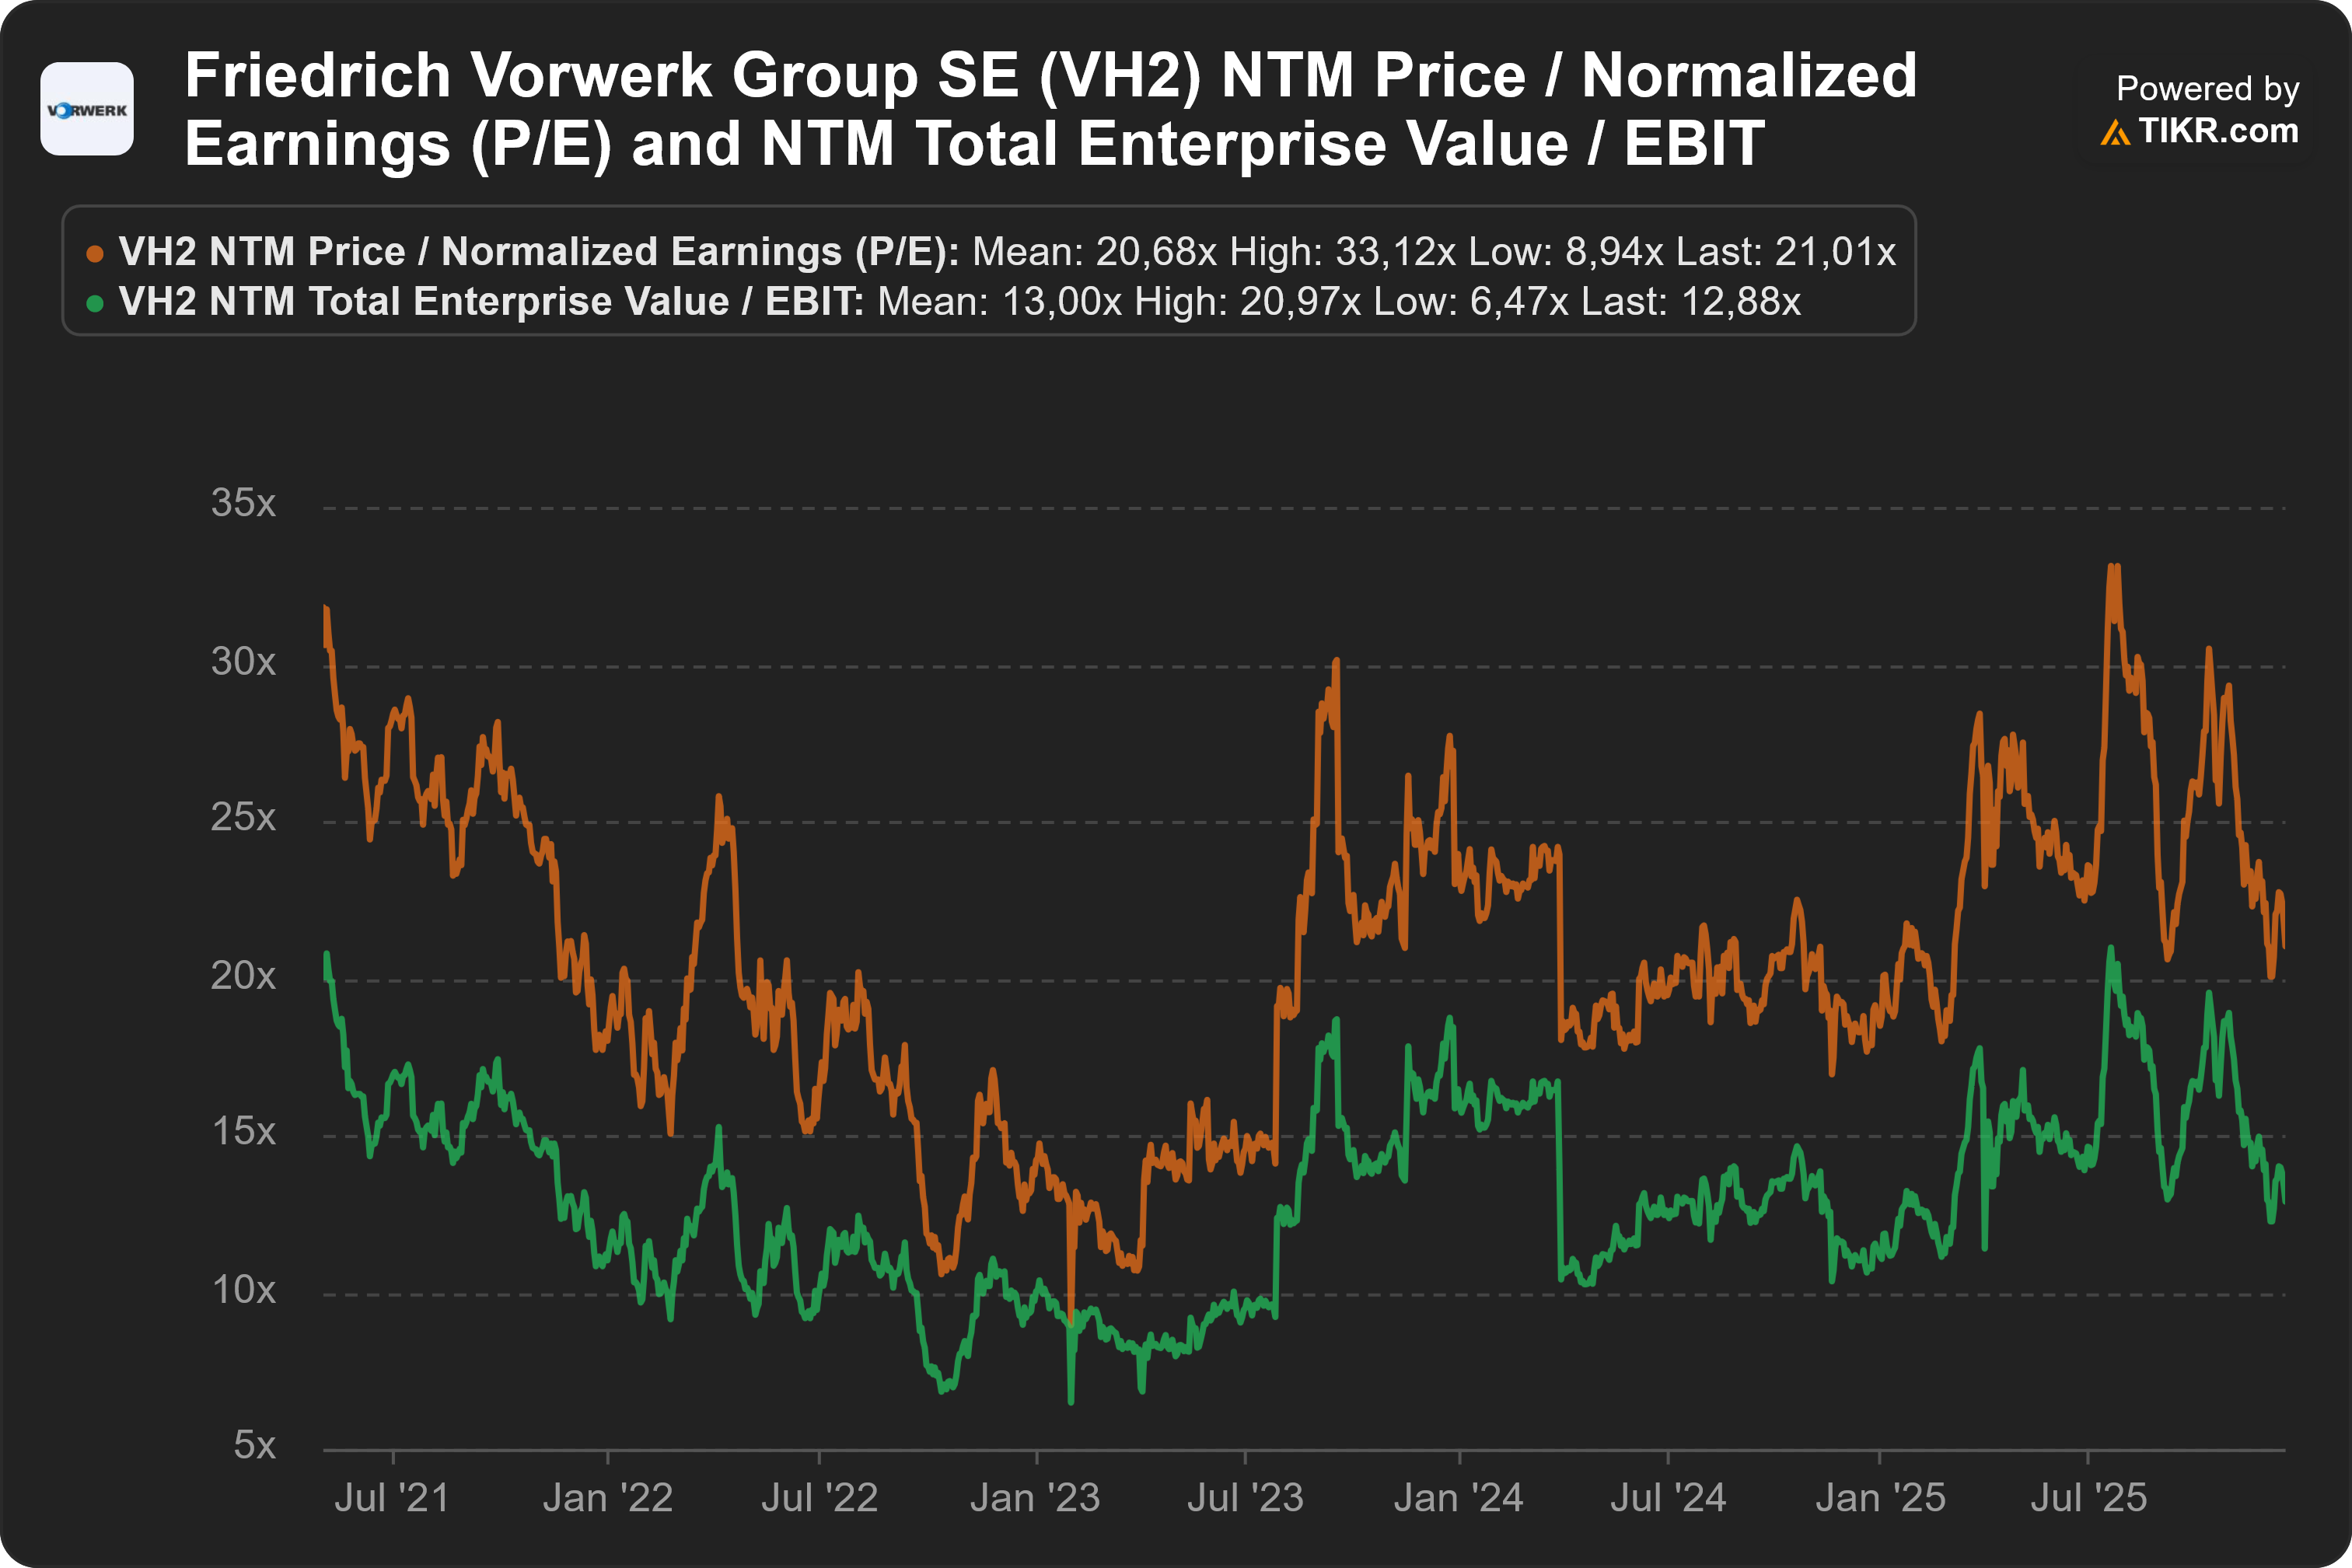
On a next-twelve-month, normalized basis, Vorwerk trades at roughly 21× P/E and ~12.9× EV/EBIT, broadly in line with its historical averages (around ~20–21× P/E and ~13× EV/EBIT). That’s an important point: despite the massive share price appreciation, multiples themselves are not at extremes. What has changed is the earnings base they are applied to.
Viewed through a cycle-adjusted lens, assuming sustainable mid-cycle EBIT margins of ~9–11% (below 2024 peaks, well above the 2022–23 trough), a cycle-adjusted P/E of ~18–20× or EV/EBIT of ~13–15× looks reasonable. Under those assumptions, a fair value range of roughly €75–85 emerges—suggesting the stock is fairly valued, not cheap, but not obviously stretched either.
A reverse DCF helps anchor what the current price actually implies. Using a 9% WACC and a 2% terminal growth rate, today’s enterprise value requires:
Low-to-mid-teens growth in free cash flow over the next 5–6 years
Sustainable EBIT margins around ~10–11%
Continued strong cash conversion and no balance-sheet leverage creep
Translated into numbers, the market is implicitly discounting an FCF CAGR of roughly 12–14% over the explicit forecast period. That is a high bar, but not an unreasonable one given Vorwerk’s backlog, balance sheet, and recent step-change in execution quality. Crucially, this growth does not assume a hydrogen boom materializes overnight—it mainly assumes steady project flow across electricity grids, gas infrastructure, and adjacent energy systems.
If one instead assumes mid-single-digit FCF growth beyond 2026 and margins drifting back toward 8–9%, fair value compresses into the €60–70 range. Conversely, if Vorwerk sustains double-digit margins and compounds FCF in the low teens for longer, valuations north of €90 can be justified mathematically.
Bottom line
At €80, Vorwerk is priced for continued execution, not for perfection—but also not for disappointment. The stock trades close to normalized historical multiples, supported by a much stronger operating and cash-flow profile than in prior cycles. From here, returns will depend far more on earnings and free-cash-flow compounding than on further multiple expansion.
Vorwerk has earned its re-rating. Now it must defend it with delivery.
Bullish Investment Case
Why is Friedrich Vorwerk compelling as a long-term investment? In one word: growth—driven by powerful mega-trends and already backed by hard execution results.
1. Booming demand for energy infrastructure
Europe is entering a once-in-a-generation infrastructure upgrade cycle, and Germany is at its center. Massive spending on power grids, gas pipelines, hydrogen networks, and energy security is underway—and Vorwerk sits right at the intersection. Its order backlog above €1 billion and a 45% YoY jump in project volume in 9M 2025 show how strong demand already is. This is not cyclical noise: infrastructure programs run through the next decade (hydrogen alone is planned until 2035), offering a long runway for growth.
2. Proven execution and record results
Vorwerk isn’t just benefiting from tailwinds—it’s delivering. Q3 2025 was a record quarter, with revenue above €200 million, growth rates approaching 50%, and EBITDA margins of 25.4%. Importantly, profitability is scaling alongside revenue. Management has repeatedly beaten expectations and raised guidance, building credibility and reinforcing the case for earnings compounding from here.
3. Real competitive edge, not just exposure
Despite its smaller size, Vorwerk has carved out a defensible niche through full-scope, technologically advanced execution. Specialized capabilities—such as complex drilling, advanced pipeline welding, and turnkey delivery—give it an edge in time-critical, high-complexity projects. This matters when clients face labor shortages and tight deadlines. Early involvement in hydrogen and CO₂ pilot projects adds a first-mover advantage as these markets scale.
4. Financial strength to fuel expansion
With net cash and no balance-sheet stress, Vorwerk can self-fund growth—investing in equipment, hiring aggressively, and pursuing bolt-on acquisitions. Over 100 new hires in Q3 2025 alone underline how quickly capacity is being expanded. The strong balance sheet also enables Vorwerk to bid confidently on large projects, where bonding and working capital are critical.
5. Upside optionality beyond current forecasts
Beyond today’s backlog, Vorwerk has meaningful optionality. Examples include the potential €5 billion NATO fuel pipeline expansion and newly approved CO₂ pipeline infrastructure in Germany. These opportunities aren’t fully reflected in current numbers, but they represent asymmetric upside over the medium term.
6. Strategic value not captured by near-term multiples
Finally, Vorwerk may carry strategic value beyond earnings. As energy-transition infrastructure scales, its know-how, relationships, and execution track record could make it a valuable partner—or even a takeover candidate—for larger industrial players. Some investors see today’s valuation as underestimating the long-term strategic relevance of the business.
In short: Vorwerk is in the right market at the right time, with strong execution, financial firepower, and multi-year tailwinds. It’s rare to see a company of this size grow this fast while being anchored to government-backed, long-duration infrastructure spending. For long-term investors, Vorwerk looks less like a one-off winner—and more like a potential compounding story.
Bearish Investment Case
No investment is risk-free, and Friedrich Vorwerk’s rapid rise comes with real challenges. Skeptics point to the following concerns:
1. Project concentration and execution risk
Vorwerk’s results depend heavily on a small number of very large projects. One example is Corridor A-Nord, which represents a significant share of the electricity backlog and has already faced permitting delays. If execution falters—through delays, cost overruns, or technical issues—the financial and reputational impact could be outsized. As project sizes increase, complexity and risk rise in tandem, leaving little room for error.
2. Workforce and capacity constraints
Scaling an engineering organization this quickly is difficult. While Vorwerk has expanded headcount by ~15%, qualified engineers, welders, and project managers remain scarce. Some analysts flag staffing as a key risk: if hiring can’t keep pace, Vorwerk may have to turn down work or stretch teams too thin, risking quality and margins. A tight labor market also means rising wages and subcontractor costs, which could pressure profitability.
3. Hydrogen hype vs. reality
Part of Vorwerk’s valuation reflects expectations of a future hydrogen boom. The bear case questions the timing and certainty of that buildout. Europe’s hydrogen plans have already seen delays, and large-scale pipelines or electrolyzer projects could slip further if regulation, subsidies, or economics disappoint. If hydrogen ramps up more slowly than hoped, growth could cool once today’s gas and power projects peak.
4. External dependencies: permits, politics, competition
Vorwerk operates in a highly regulated environment. Lengthy permitting processes, political shifts, or changing infrastructure priorities can delay or cancel projects. At the same time, rising infrastructure budgets may attract larger engineering and construction players, intensifying competition and squeezing margins. Vorwerk’s niche advantages could narrow if rivals scale up or underbid.
5. Seasonality and normalization risk
Construction activity is seasonal and somewhat cyclical, with winter slowdowns and potential project deferrals. The 2024–25 period has been unusually favorable due to post-crisis urgency. If these tailwinds fade, growth could normalize, creating volatility that challenges a high-growth narrative.
In short: The bearish case isn’t that Vorwerk is a bad company—but that expectations are extremely high. Heavy project concentration, capacity constraints, hydrogen timing risk, and a valuation that assumes near-flawless execution all raise the stakes. For investors, the story remains attractive—but the path forward is unlikely to be linear, and price paid will matter just as much as performance delivered.
Outlook
Looking ahead, Friedrich Vorwerk’s outlook remains broadly positive, supported by strong secular tailwinds and a >€1 billion order backlog—though a few key variables warrant close attention.
Guidance points to another record year
Management recently raised 2025 guidance to €650–680 million in revenue and an EBITDA margin of ~21%, implying 30%+ sales growth and an even sharper rise in profits. Delivery will hinge on executing the existing backlog and converting expected new orders in the second half. On the Q3 call, management emphasized a robust growth trajectory across natural gas, electricity, and hydrogen, backed by ongoing innovation (e.g. upgraded welding systems) and expansion into areas like district heating and CO₂ transport.
Industry backdrop strongly supportive
The macro setup in Germany and Europe is highly favorable. Massive, policy-backed infrastructure programs—grid expansion, LNG connections, hydrogen core networks, and major power corridors like SuedLink—are either underway or close to award. Vorwerk is already involved in many of these projects and well positioned to win additional contracts in gas, electricity, and hydrogen. Management expects the recent order intake lull to be temporary, with several large awards approaching. Beyond Germany, geopolitical and climate initiatives (e.g. NATO fuel pipelines, CO₂ infrastructure) add further medium-term optionality.
Key watchpoints for investors
• Timing and permitting risk
Project execution depends heavily on regulatory approvals and permits. Delays—whether for hydrogen pipelines, CO₂ transport, or power routes—can shift revenue between years. Political support is strong, but bureaucratic timing remains a swing factor.
• Margin sustainability
The guided ~20% EBITDA margin is well above historical levels. Management argues margins should structurally improve as lower-margin legacy contracts roll off, which is encouraging. Still, investors will want confirmation—especially guidance for 2026—that current margins are sustainable, not cyclical peaks.
• Order intake and backlog replenishment
As current projects are executed, new contract wins must refill the backlog. The book-to-bill ratio will be a key metric to watch. Landing large hydrogen, LNG, or power-grid contracts would meaningfully extend the growth runway beyond 2025.
• Strategic moves and capital allocation
Vorwerk’s strong balance sheet allows for bolt-on acquisitions or partnerships to expand capacity or expertise. Any inorganic growth—or a shift toward higher shareholder returns once capex moderates—could reshape the medium-term outlook.
Bottom line: Vorwerk enters the next phase with strong momentum, high visibility, and favorable industry dynamics. If execution stays tight and order flow continues, double-digit growth looks achievable for several more years. The key test will be sustaining margins and replenishing the backlog as today’s mega-projects progress. So far, the story is intact—but the next chapters of the energy transition will determine just how durable this growth really is.
Conclusion
Friedrich Vorwerk Group SE has become an unlikely standout in today’s market. Not a flashy tech name, but a decades-old engineering firm that has reinvented itself at exactly the right moment. Digging into the numbers and strategy reveals a clear story: Vorwerk is a critical enabler of Europe’s energy transition, and it’s executing with remarkable momentum. 2024 was a breakout year, and 2025 is on track to raise the bar again, fueled by booming demand for pipelines, power grids, and hydrogen infrastructure. What started as traditional pipeline construction has evolved into a high-tech, fully integrated infrastructure platform—a niche that few competitors can match.
For long-term investors, the appeal is obvious: multi-year secular tailwinds, a management team that consistently overdelivers, a fortress balance sheet, and multiple growth options—from hydrogen and CO₂ to new regions. At the same time, the stock’s dramatic rally means expectations are high. At today’s valuation, investors are betting that Vorwerk can keep scaling profitably while navigating the execution risks inherent in large infrastructure projects.
The reality lies between the bull and bear cases. Vorwerk has the potential to be a “picks-and-shovels” winner of the energy transition, compounding growth as infrastructure spending accelerates. But success will depend on flawless execution, disciplined expansion, and sustained margins—with little room for missteps.
The bottom line: Vorwerk represents a rare blend of old-economy engineering expertise and new-economy relevance. It sits in the engine room of an energy infrastructure boom—and so far, it’s handling the pressure well. For investors willing to tolerate some volatility and think in multi-year terms, Friedrich Vorwerk SE offers an intriguing opportunity: a smaller industrial player with a credible path to becoming a much bigger one.
Behind Vorwerk, the main shareholder, MBB SE, a German investment company, is also worth a look. MBB shaped Vorwerk into its current form and initiated its IPO to finance its growth.
Very nice analysis. Learned about on a company I had never heard of