

Disclaimer: The information provided in this publication is for educational and informational purposes only and does not constitute financial advice. The content is solely reflective of my personal views and opinions based on my research and is not intended to be used as a basis for investment decisions. While every effort is made to ensure that the information is accurate and up-to-date, the writer makes no representations as to the accuracy, completeness, suitability, or validity of any information in this post and will not be liable for any errors, omissions, or delays in this information or any losses, injuries, or damages arising from its display or use. All readers are advised to conduct their own independent research or consult a professional financial advisor before making any investment decisions. The author is not invested in the mentioned stock.
E-Book and Paperback “Investing in Small-Caps - The ultimate Guide”

Logista Integral, S.A.: Europe’s Hidden Distribution Powerhouse
Some of the most interesting businesses in the market are the ones you never really notice.
They don’t sell glamorous products, they don’t dominate headlines, and they rarely feature in growth-stock conversations. Instead, they sit quietly in the background, making the everyday economy work — reliably, repeatedly, and with very little drama.
Logista Integral, S.A. is exactly that kind of company.
Every day, Logista moves cigarettes, medicines, magazines, convenience goods, parcels, and digital transactions from producers to tens of thousands of small retailers across Southern Europe. It’s not flashy. It’s not disruptive. But it’s deeply embedded infrastructure — the kind that’s hard to replace, easy to underestimate, and often highly profitable for patient investors.
At first glance, Logista can look like a relic of the past: tied to tobacco, operating in mature markets, growing slowly. And yet, beneath the surface, it combines remarkable consistency, strong cash generation, and one of the most generous dividend profiles in Europe. It has quietly diversified its business, kept leverage low, and built a distribution network that would take decades (and billions) to replicate.
This deep dive looks past the headlines and into the mechanics of the business:
how Logista actually makes money, why its margins are thin but its returns are high, what the market is really pricing in today — and where the balance lies between durability and decline.
This is not a story about explosive growth.
It’s a story about infrastructure-like cash flows, disciplined capital allocation, and getting paid well while you wait.
If you’re interested in businesses that reward patience rather than excitement, Logista is worth a closer look.
Company Overview
Logista Integral, S.A. (LOG) is one of Europe’s largest — and least visible — logistics powerhouses. If you’ve ever bought cigarettes in Spain, a pharma product in Italy, or a magazine in France, chances are Logista was working quietly in the background. The company specializes in what it calls “proximity” retail, meaning small, local points of sale that need frequent, reliable deliveries.
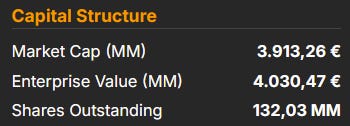
Behind the scenes, Logista operates a highly capillary distribution network serving around 200,000 outlets across Spain, France, Italy, Portugal, the Benelux, and Poland. Its reach is extraordinary. Tobacco is still the backbone, but the product mix extends far beyond that — from pharmaceuticals, convenience goods and lotteries to books, parcels and electronic top-up cards. For manufacturers, Logista offers exactly what matters most: the fastest and most reliable route to thousands of small retailers. To support this, the company also runs Spain’s largest transport network, including courier and parcel services.
Logista’s roots go back decades and tie directly to Spain’s former tobacco monopoly. Today, it is a publicly listed company, with Imperial Brands still holding roughly 50% of the shares, a legacy of Logista’s original role as Imperial’s distribution arm. But the business has evolved. Over the past years, Logista has systematically diversified beyond tobacco, expanding into pharma, convenience products, parcel delivery, and specialized logistics like cold-chain transport.
At its core, Logista is a quiet infrastructure business — a critical, behind-the-scenes operator that keeps everyday products moving efficiently from producers to thousands of local shops across Southern Europe. It doesn’t chase headlines. It just makes the system work.
Latest Financials at a Glance
Logista’s latest results for fiscal year 2025 paint a familiar picture: steady growth on the top line, paired with a slightly softer bottom line. The company’s key internal metric, “Economic Sales” (essentially gross profit), reached €1.81 billion, up around 3% year-on-year. Total revenues — which largely reflect pass-through product costs and taxes — climbed to an impressive €13.54 billion (+4.2%), underlining just how much volume flows through Logista’s network every single day. Growth was driven mainly by strong performance in Iberia and Italy, more than compensating for a weaker trend in France.
Profitability, however, edged lower. Adjusted EBIT came in at €378 million, down about 2% from the prior year, while net profit declined 9% to €281 million. Importantly, this wasn’t an operational breakdown. Management pointed to lower financial income as the main culprit: as interest rates eased in 2025, Logista earned less on its substantial cash balances and on its daily cash-lending arrangement to Imperial Brands under a roughly €3 billion credit facility. When rates move, Logista feels it immediately.
Cash generation remained a bright spot. Free cash flow stayed robust, helped by favorable working capital dynamics. In fact, some estimates suggest FY2025 free cash flow more than doubled to around €483 million, once again highlighting the cash-rich nature of the business.
Taken together, the numbers show a company doing exactly what Logista tends to do: growing slowly but reliably, converting earnings into cash, and absorbing manageable headwinds — from lower interest income to softer French tobacco volumes — without any real drama.
Key financials
If you look at Logista Integral’s business performance over the past years, the first thing that stands out is not acceleration, disruption, or dramatic swings. What stands out is consistency — and the kind of consistency that only a deeply embedded, structurally advantaged business can deliver.

Starting with the top line, Logista’s revenues show a steady and remarkably smooth upward trajectory. From just over €10.1 billion in FY2019, revenues rise year after year to roughly €13.5 billion by FY2025. There are no boom years, no collapses, no sharp inflection points — just reliable, incremental growth. This is exactly what you would expect from Logista’s core role as the dominant logistics and distribution partner for regulated products (most notably tobacco) across Southern Europe. Volumes don’t explode, pricing power is constrained, but demand is stable, recurring, and resilient even through macro stress.
That stability flows directly into operating income. EBIT grows from roughly €198 million in 2019 to above €310 million by 2024/25. What’s notable here is not just the absolute increase, but the absence of operational leverage drama. Margins do not surge — but they don’t collapse either. This reflects a business that prioritizes service reliability, regulatory compliance, and long-term contracts over aggressive margin expansion. Net income follows a very similar pattern: gradual growth, limited volatility, and no evidence of earnings manipulation or one-off driven profitability. In short, Logista behaves exactly like a mature infrastructure-like distributor should.
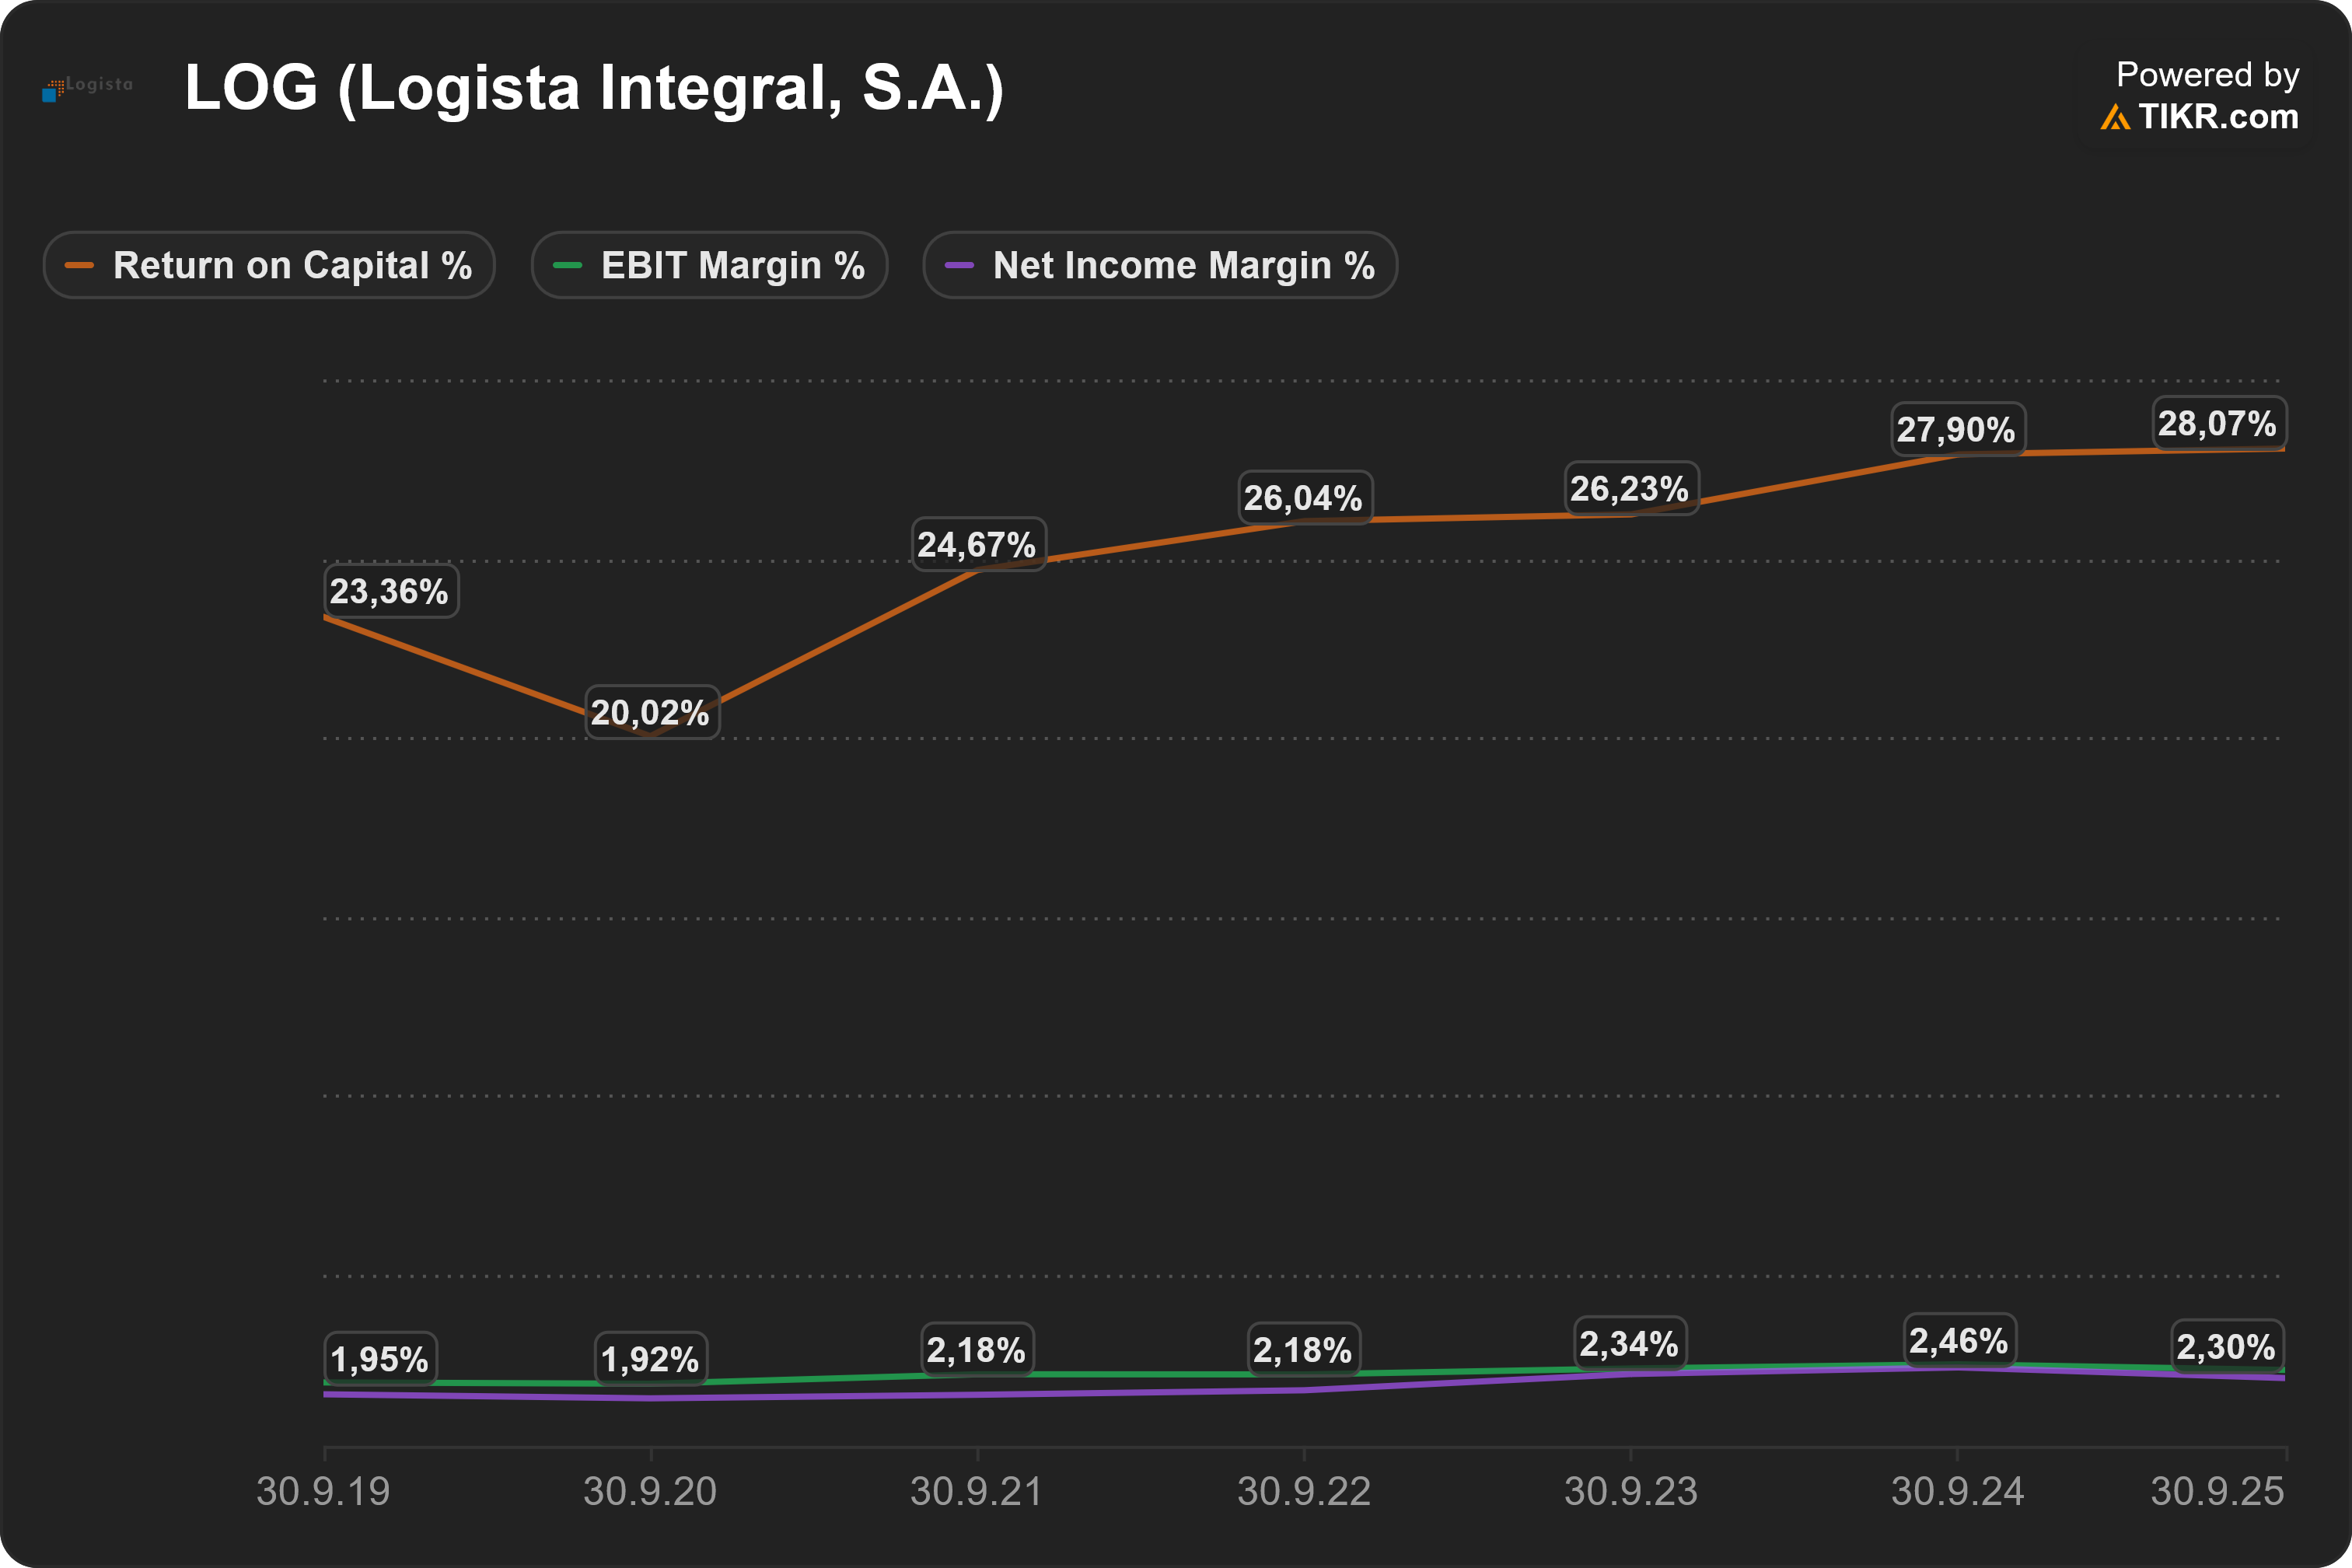
Moving from absolute numbers to returns and margins, the picture becomes even clearer. Return on capital sits consistently in the low-to-high 20% range, dipping briefly in 2020 and then grinding higher to roughly 28% by 2024/25. This is an exceptionally strong outcome for a company that operates on thin margins. It tells us that Logista does not need high margins to create value — it needs scale, efficiency, and asset discipline. Capital is turned over again and again in a system that has very little redundancy.
By contrast, EBIT and net income margins remain modest, hovering around 2–2.5%. At first glance, this might look uninspiring. In reality, it is precisely what makes the model durable. Thin margins discourage competition, regulators tolerate them, and customers accept them — while Logista earns its returns through sheer volume, contractual stickiness, and operational excellence. This is a defensive moat built on structure rather than brand or innovation.
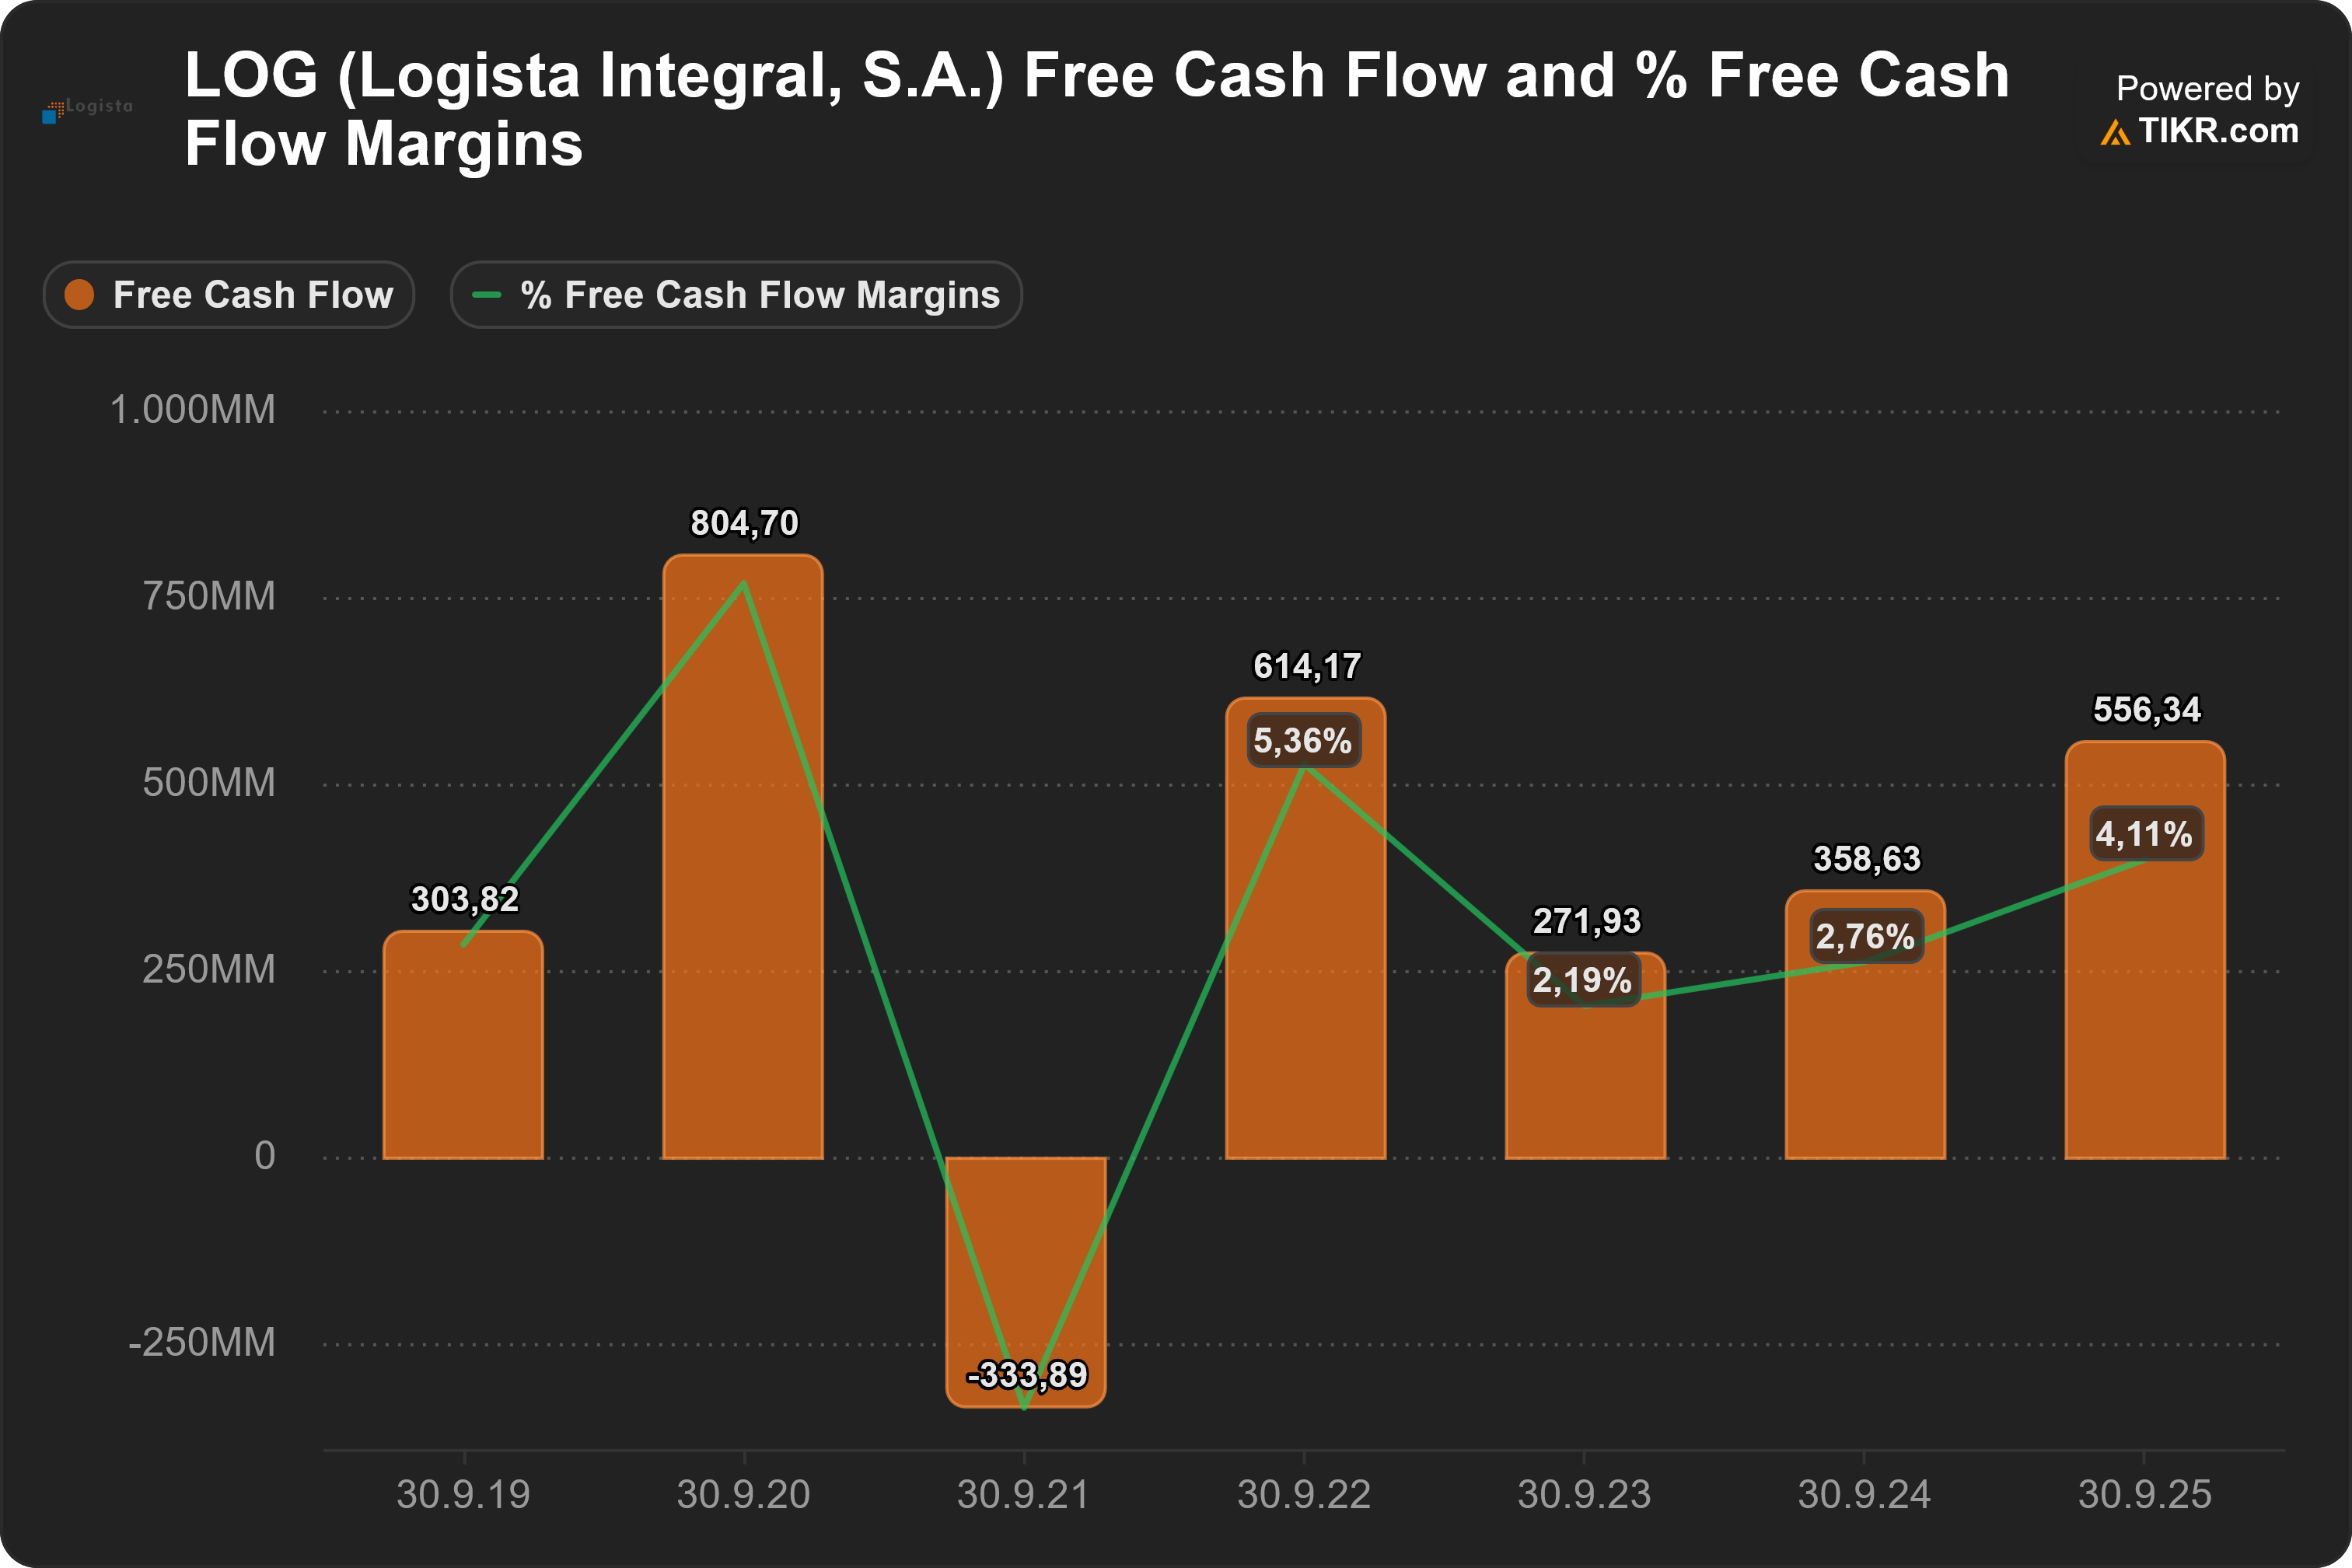
The cash flow picture adds an important layer of nuance. Free cash flow is positive in most years, but not smooth. After strong generation in 2020, Logista posts a sharply negative FCF in 2021, followed by a strong rebound in 2022 and improving levels thereafter. This volatility is not a red flag in this context. It reflects working capital timing, inventory dynamics, and settlement cycles typical for large-scale distributors. What matters is that over the cycle, cash conversion works — and free cash flow margins recover into the 3–5% range in normal years.
Crucially, Logista does not rely on financial engineering to mask weak cash generation. When FCF dips, it is visible. When it recovers, it does so organically. This transparency is rare and valuable, especially in a low-growth, regulated environment.
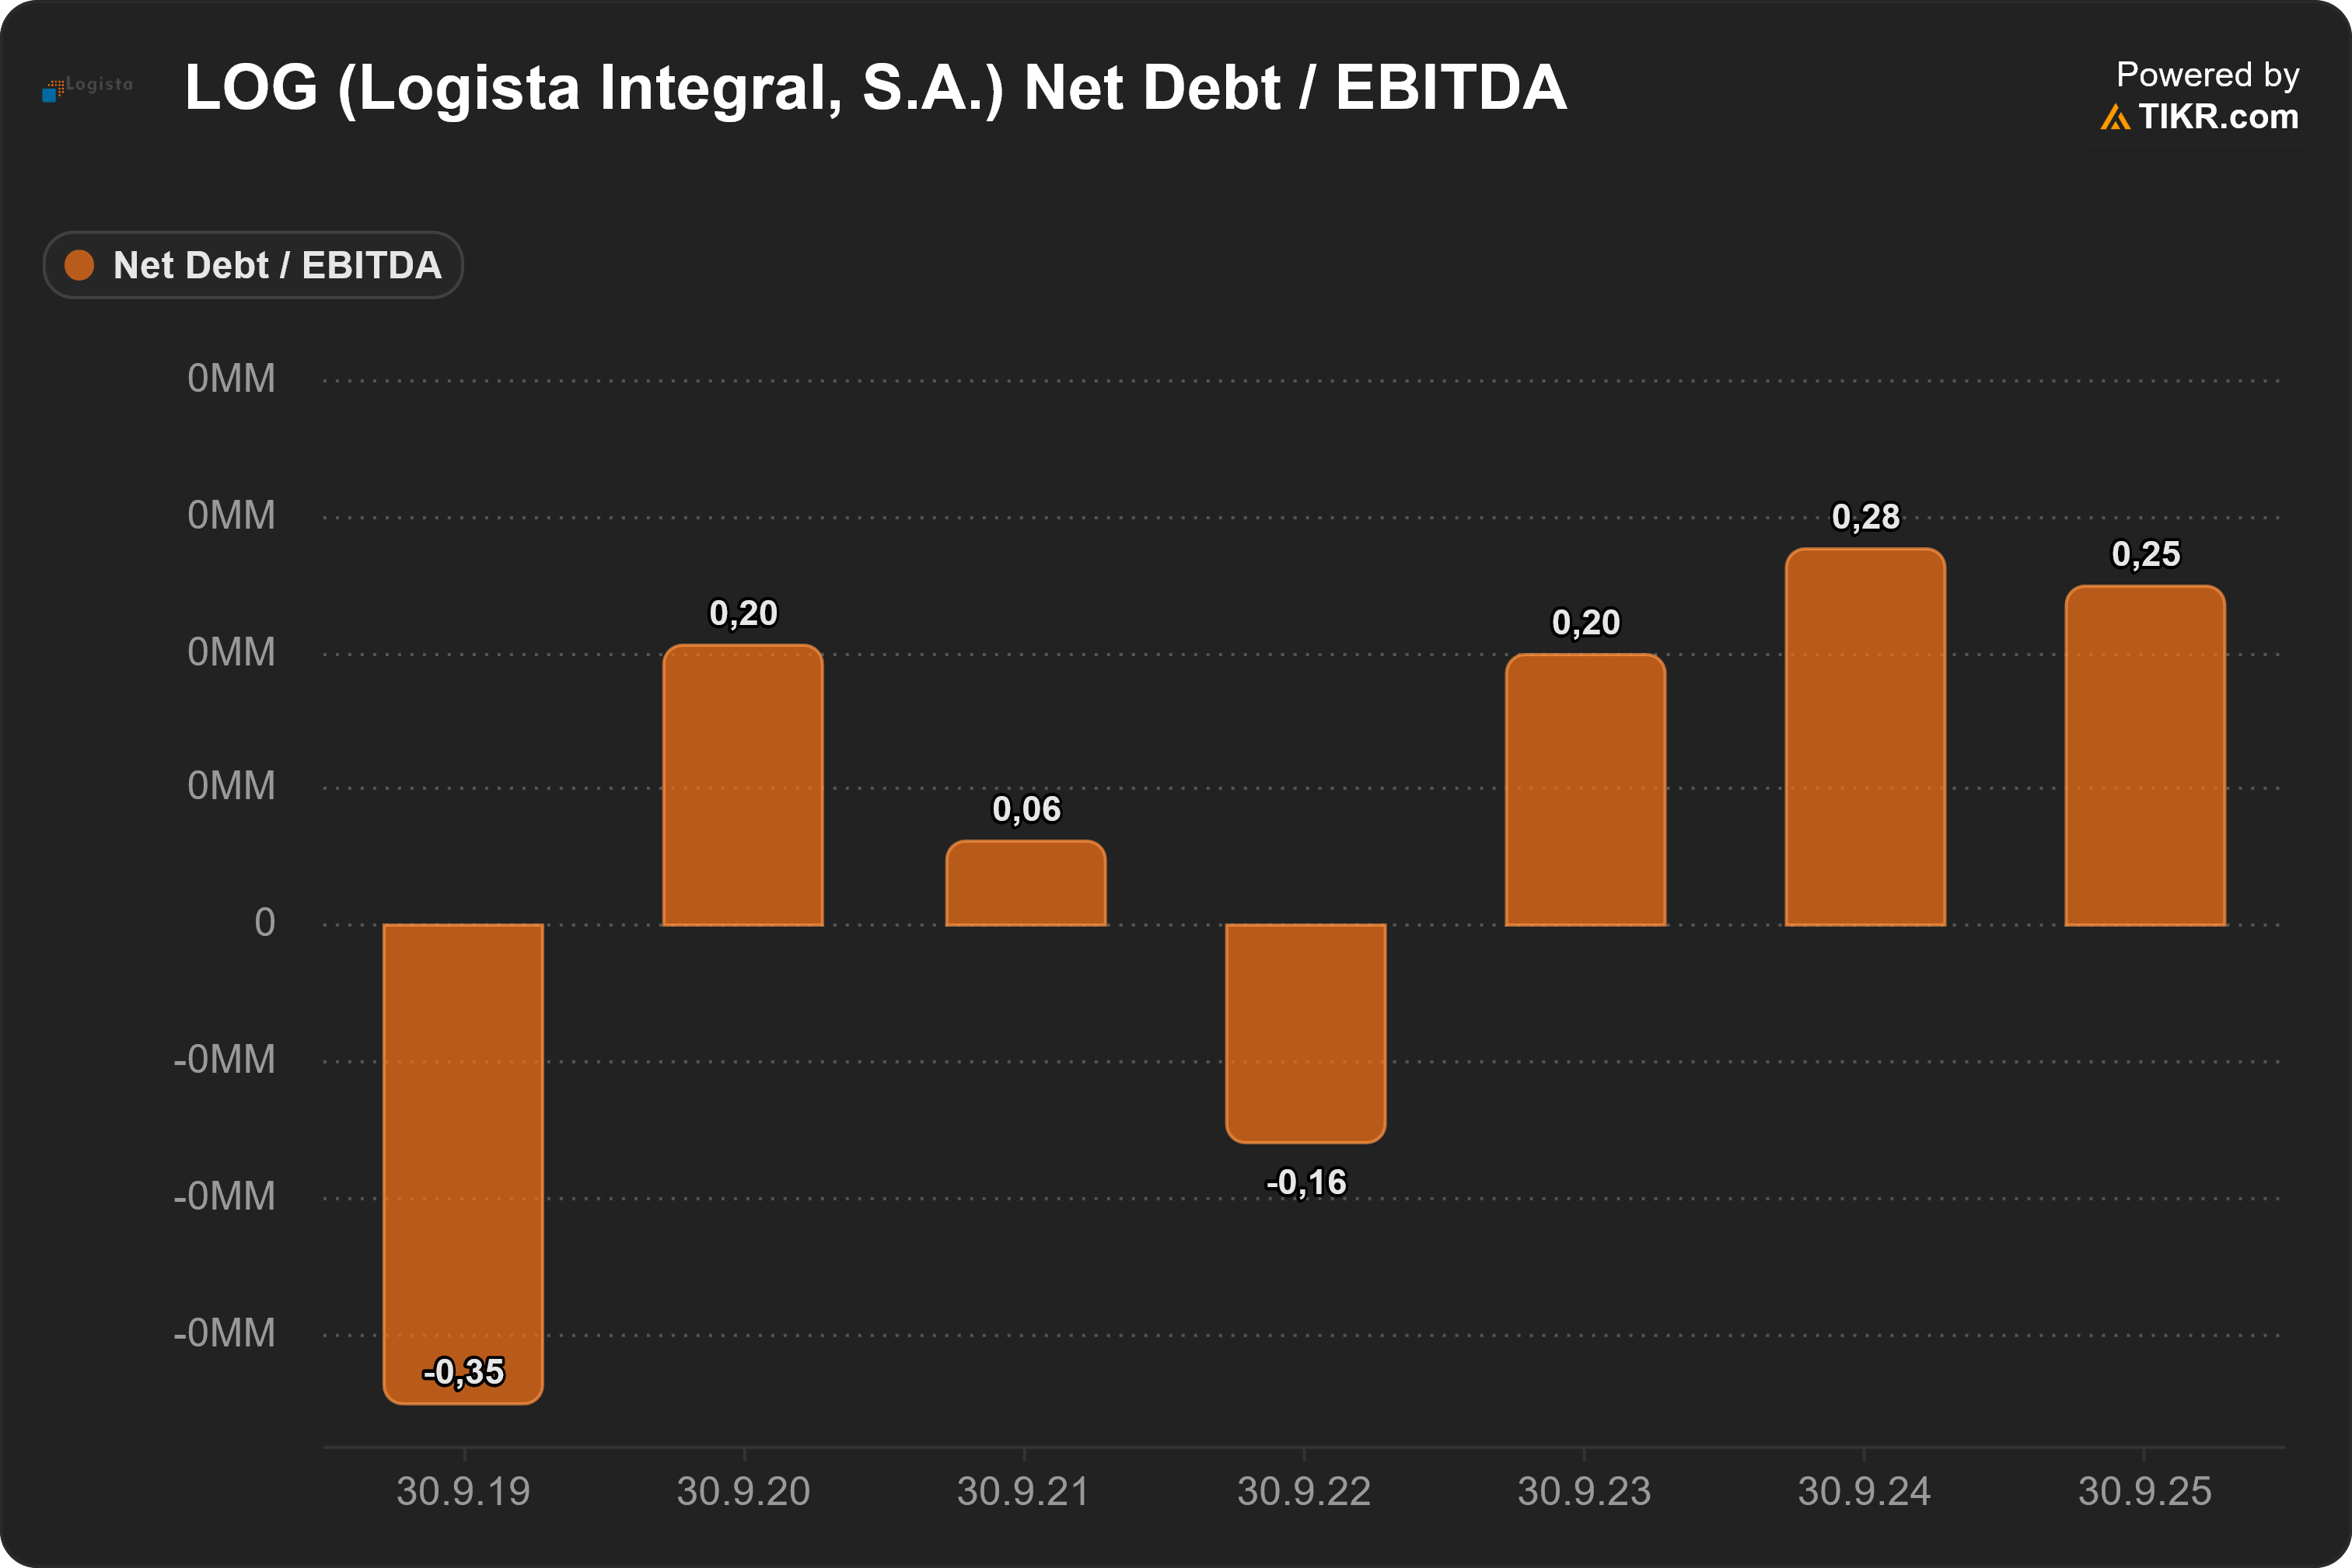
Finally, the balance sheet and leverage complete the picture. Net debt to EBITDA oscillates around zero and remains well below 0.5x throughout the entire period. In some years, Logista even operates in a net cash position. This is not accidental. Management clearly runs the company with a conservative capital structure, aware that regulatory risk, political risk, and structural change in tobacco consumption require balance sheet resilience. Low leverage gives Logista optionality: dividends can be paid, shocks can be absorbed, and strategic adjustments can be made without external pressure.
Taken together, these four charts tell a very coherent story. Logista Integral is not a growth stock, not a turnaround, and not a cyclical bet. It is a cash-generating, high-return, low-drama compounder embedded in critical distribution infrastructure. The numbers do not shout — they reassure. And for long-term investors who value predictability over excitement, that is exactly the point.
Business Model Explained
So how does Logista actually make money? At its core, the business is a highly efficient middleman. Logista sits between manufacturers and a fragmented universe of small retailers — kiosks, petrol stations, pharmacies, convenience stores — that would be expensive and impractical to supply directly. Instead, Logista runs the infrastructure: warehouses, delivery fleets, IT systems, payments, and specialized service points, and earns a distribution margin for moving products from A to B.
This value-add is best captured by “Economic Sales”, Logista’s preferred performance metric. Unlike headline revenue (which is inflated by tobacco taxes and pass-through costs), Economic Sales represent gross profit — the money Logista actually keeps for providing distribution services. In 2025, Economic Sales reached roughly €1.8 billion, a far more meaningful number than the €13+ billion revenue headline.
Operationally, Logista spans several business lines. Tobacco remains the historical core, accounting for roughly half of Economic Sales. In markets like Spain and Italy, tobacco distribution has high regulatory barriers and near-monopoly characteristics, giving Logista entrenched positions and predictable volumes — even as long-term consumption trends slowly decline.
Alongside tobacco sits convenience products and e-transactions: snacks, drinks, magazines, books, lottery tickets, and electronic top-ups. These products ride along the same delivery routes, improving network efficiency and diversifying revenue. Logista even runs Logista Payments, which handles electronic transactions at retail points.
A key growth pillar is pharmaceutical distribution. Through Logista Pharma, the company offers specialized, often temperature-controlled logistics for pharmacies and hospitals. This segment has expanded rapidly in Iberia and Italy, where aging populations support structurally rising demand.
Then there’s transport and parcel services, including businesses like Nacex (parcel delivery) and Transportes El Mosca (freight and cold-chain logistics). These operations serve both Logista’s internal needs and third-party customers. In fact, transport is now one of the largest contributors to Economic Sales in Iberia, giving Logista capabilities well beyond tobacco — including food and refrigerated logistics.
Crucially, Logista has been actively diversifying away from tobacco. In fiscal 2023, non-tobacco activities reached 50% of Economic Sales for the first time. This shift has been driven by targeted acquisitions — from Italian pharma distributor Gramma Farmaceutici, to Spanish cold-chain specialist Carbó Collbatallé, to book distributor SGEL Libros — as well as organic growth. The strategy is simple but powerful: build one massive distribution machine, then feed more product categories through it.
Financially, this model produces thin margins but strong cash flows. Net profit margins sit around 2% of revenue, while adjusted EBIT is roughly 20% of Economic Sales. But capital intensity is low, and working capital dynamics are favorable — products are sold quickly while suppliers are paid later. The result is excellent cash generation. With minimal net debt (around 0.2× EBITDA), Logista runs a conservative balance sheet that comfortably supports its generous dividend policy, which we’ll turn to later.
Strengths and Weaknesses
Strenghts
Every business has its strengths and its trade-offs. From a long-term investor’s perspective, Logista’s profile is defined by a powerful core and a very specific set of risks.
On the strengths side, the most important advantage is Logista’s dominant market position and network effects. With a capillary distribution network serving roughly 200,000 points of sale, Logista is the clear leader in proximity retail distribution across Southern Europe. This infrastructure is expensive, complex, and time-consuming to replicate. Manufacturers and retailers depend on Logista as a one-stop distribution partner, creating high switching costs and a durable moat in its core markets.
Another key pillar is diversification. While tobacco remains the historical backbone, Logista now operates across convenience goods, pharmaceuticals, publications, parcel delivery, and transport logistics. This has meaningfully reduced reliance on cigarettes. In fact, non-tobacco activities reached 50% of gross profit in 2023, helping to offset long-term volume declines in smoking. The ability to bundle multiple products on the same delivery routes increases efficiency and boosts revenue per stop — a subtle but powerful advantage.
Logista is also a strong cash generator. Its low-margin, high-volume model converts a large share of earnings into free cash flow, supported by minimal capex needs and favorable working capital dynamics. With very low leverage, operating profits flow largely to shareholders. This underpins Logista’s exceptionally generous dividend policy, with payouts close to 90–100% of net income. For income-focused investors, the stock has offered a yield of roughly 7% or more, backed by real, recurring cash flows rather than balance-sheet stretch.
The business is further supported by resilience and stability. Logista distributes products with relatively steady demand — tobacco, food, medicines, and convenience items — many of which are non-discretionary or habit-driven. As a result, earnings have historically been remarkably stable across economic cycles, including during recessions and inflationary periods. Operating primarily in developed European markets adds regulatory predictability, even if tobacco regulation remains tight.
Finally, Logista has shown an ability to grow through acquisitions and new categories. Bolt-on deals like Transportes El Mosca expanded its capabilities in cold-chain logistics, while investments in next-generation nicotine products allow it to evolve alongside its tobacco customers. Backed by a strong balance sheet, Logista has the financial flexibility to continue pursuing selective acquisitions, particularly in areas like pharma distribution where long-term demand is structurally attractive.
Weaknesses and Risks
No business is without risk, and Logista’s weak spots are closely tied to the very factors that make it stable.
The most obvious challenge is continued reliance on tobacco. Despite meaningful diversification, around half of Logista’s gross profit still comes from tobacco products. Cigarette consumption in Western Europe is in structural decline, driven by regulation, higher taxes, and changing consumer behavior. This showed up clearly in FY2025, when tobacco volumes fell sharply in France (nearly –9%) and edged lower in Spain. Over time, Logista must grow non-tobacco segments just to offset this drag. A faster-than-expected decline — whether from aggressive regulation or shifts to alternative products outside Logista’s distribution network — would weigh on revenues and profits.
Closely related is regulatory and tax risk. Tobacco and pharmaceuticals are among the most heavily regulated industries in Europe. Changes in taxation, product rules, display regulations, or flavor bans can indirectly hurt volumes and disrupt distribution economics. Higher taxes also raise the risk of illicit trade, which bypasses legal distributors entirely. In addition, Logista’s historical link to Imperial Brands creates a degree of dependency. While there’s no sign of change today, any major strategic shift by Imperial — such as altering distribution arrangements or reducing its stake — could introduce uncertainty.
Another structural risk lies in thin margins. Logistics is a scale business, and Logista operates on very tight operating margins, making cost control essential. Inflation in fuel, labor, or IT investments can quickly squeeze profitability if not fully passed on. This was visible in FY2025, when Economic Sales grew 3% but the adjusted EBIT margin slipped to 20.9% from 21.9%. Execution matters: operational disruptions, acquisition integration issues, or inefficiencies in the transport network can have an outsized impact on earnings.
There’s also an unusual — but real — exposure to interest rates. Because Logista holds large cash balances and lends surplus cash to Imperial Brands, its net profit fluctuates with European interest rates. In 2024, high rates boosted financial income; in 2025, falling rates cut financial income by roughly €30 million, dragging on net profit. This doesn’t reflect operational weakness, but it does mean reported earnings can move independently of core performance.
Finally, Logista faces natural growth limits and geographic concentration. Its core markets in Southern Europe are mature and low-growth, implying organic growth in the low single digits over time. Management’s guidance for mid-single-digit EBIT growth is solid, but not explosive. Expansion will likely remain gradual, especially with a conservative acquisition stance. Profit concentration in Spain and Italy also increases exposure to local economic or regulatory shocks, while the weaker performance in France in 2025 highlights that not all regions are equally robust.
In short, Logista’s investment case is a balancing act. Network dominance, diversification, and cash generation provide a strong defensive foundation — but success over the long run depends on management’s ability to adapt as tobacco declines and regulation evolves. That tension sits at the heart of the bull and bear cases, which we’ll turn to next.
🔒 The rest of this article is for paid subscribers
If you choose to upgrade, you’ll get access to the full deep dive – including the companies dividend policy and buyback activity, valuation breakdowns, and both the bullish and bearish investment case. In every paid section, I go beyond the headlines and share detailed numbers, scenarios, and outlooks that long-term investors can actually use. It’s where I connect the dots between financial performance, strategy, and what it means for your portfolio.