

Disclaimer: The information provided in this publication is for educational and informational purposes only and does not constitute financial advice. The content is solely reflective of my personal views and opinions based on my research and is not intended to be used as a basis for investment decisions. While every effort is made to ensure that the information is accurate and up-to-date, the writer makes no representations as to the accuracy, completeness, suitability, or validity of any information in this post and will not be liable for any errors, omissions, or delays in this information or any losses, injuries, or damages arising from its display or use. All readers are advised to conduct their own independent research or consult a professional financial advisor before making any investment decisions. The author is not invested in the mentioned stock.
E-Book and Paperback “Investing in Small-Caps - The ultimate Guide”

HCI Group, Inc.
Insurance is not an industry known for innovation or excitement—until stress exposes who is merely surviving and who is genuinely prepared. Florida’s homeowners market has been one of the harshest testing grounds in the industry, breaking insurers through hurricanes, litigation, and capital missteps.
HCI Group, Inc. operates right at the center of that storm.
Over the past decade, the company has navigated extreme volatility while steadily expanding its footprint across underwriting, technology, and capital-light growth structures. The result is a business that looks very different today than it did just a few years ago—larger, more complex, and harder to categorize.
This analysis examines how HCI makes money, how its platform is structured, and where the real risks and opportunities lie. The aim is not to predict the weather, but to understand whether the company is positioned to endure it.
Company Overview
In a hurricane-battered market where many insurers have collapsed, HCI Group, Inc. (NYSE: HCI) has emerged as a survivor turned innovator. Based in Tampa, Florida, HCI is a property & casualty insurance holding company—but with a distinctly high-tech edge.
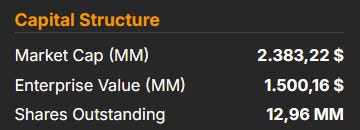
At its core, HCI focuses on Florida homeowners insurance, yet its model is far from traditional. The company has built a diversified, vertically integrated ecosystem spanning insurance underwriting, insurance technology, reinsurance, claims management, and real estate. Its largest carrier, Homeowners Choice, writes residential property policies across Florida, while TypTap Insurance targets specific niches within homeowners and specialty lines. TypTap’s operations are supported by proprietary platforms developed by Exzeo, HCI’s former in-house technology arm that is now a separately listed company.
HCI has further expanded through policyholder-owned reciprocal exchanges such as Tailrow Insurance Exchange and CORE, which it sponsors and manages. Beyond that, the group includes a Bermuda-based reinsurance affiliate (Claddaugh), an in-house claims adjusting firm (Griston), and a commercial real estate portfolio held through Greenleaf Capital, focused on Florida assets.
This may sound eclectic—but it’s deliberately constructed. By keeping underwriting, claims, reinsurance, analytics, and capital deployment under one roof (or tightly affiliated structures), HCI has created a self-reinforcing insurance platform. That integration has allowed the company to withstand Florida’s extreme volatility and grow beyond the limits of a typical regional insurer.
Latest Financials
HCI’s financial comeback has been striking, especially after the storm-driven turbulence of recent years. In 2023, the company delivered record profitability, generating $79 million in net income ($7.62 per share) on $550.7 million in revenue—a sharp reversal from 2022’s $55 million net loss, which was heavily impacted by Hurricane Ian. A calmer storm season, higher premium rates, and tighter underwriting drove the turnaround, pushing HCI’s combined ratio well below 100% and firmly back into underwriting profit.
That momentum didn’t fade. 2024 and 2025 have taken performance to another level. In Q3 2025 alone, HCI earned $4.90 per share and posted a remarkable 64% combined ratio, fueled by an exceptionally low 22% loss ratio in a quiet quarter. Quarterly revenue reached ~$216 million, and while investment income normalized, underwriting strength more than compensated.
The balance sheet tells the same story. Book value per share surged to ~$63 by Q3 2025, up from roughly $33 at the start of 2023, and management expects it to approach $80 by year-end 2025. In just two years, HCI has gone from deep losses to industry-leading underwriting margins.
Weather risk always looms—but for now, HCI is executing flawlessly and riding a powerful wave of profitability.
Financial History
HCI Group’s recent business performance reads like a textbook example of cyclical pain followed by operational leverage kicking in. The charts tell a story that is neither smooth nor linear—but very revealing if you follow the sequence carefully.
Revenues, operating momentum and net income: scale first, volatility later, then payoff
Starting with revenues and net income, the long-term trajectory is unmistakably upward. Total revenues rise steadily from roughly $240m in 2019 to about $750m by 2024, nearly tripling over five years. This growth is not a one-off spike but a sustained expansion, reflecting a much larger premium base and a structurally bigger business.
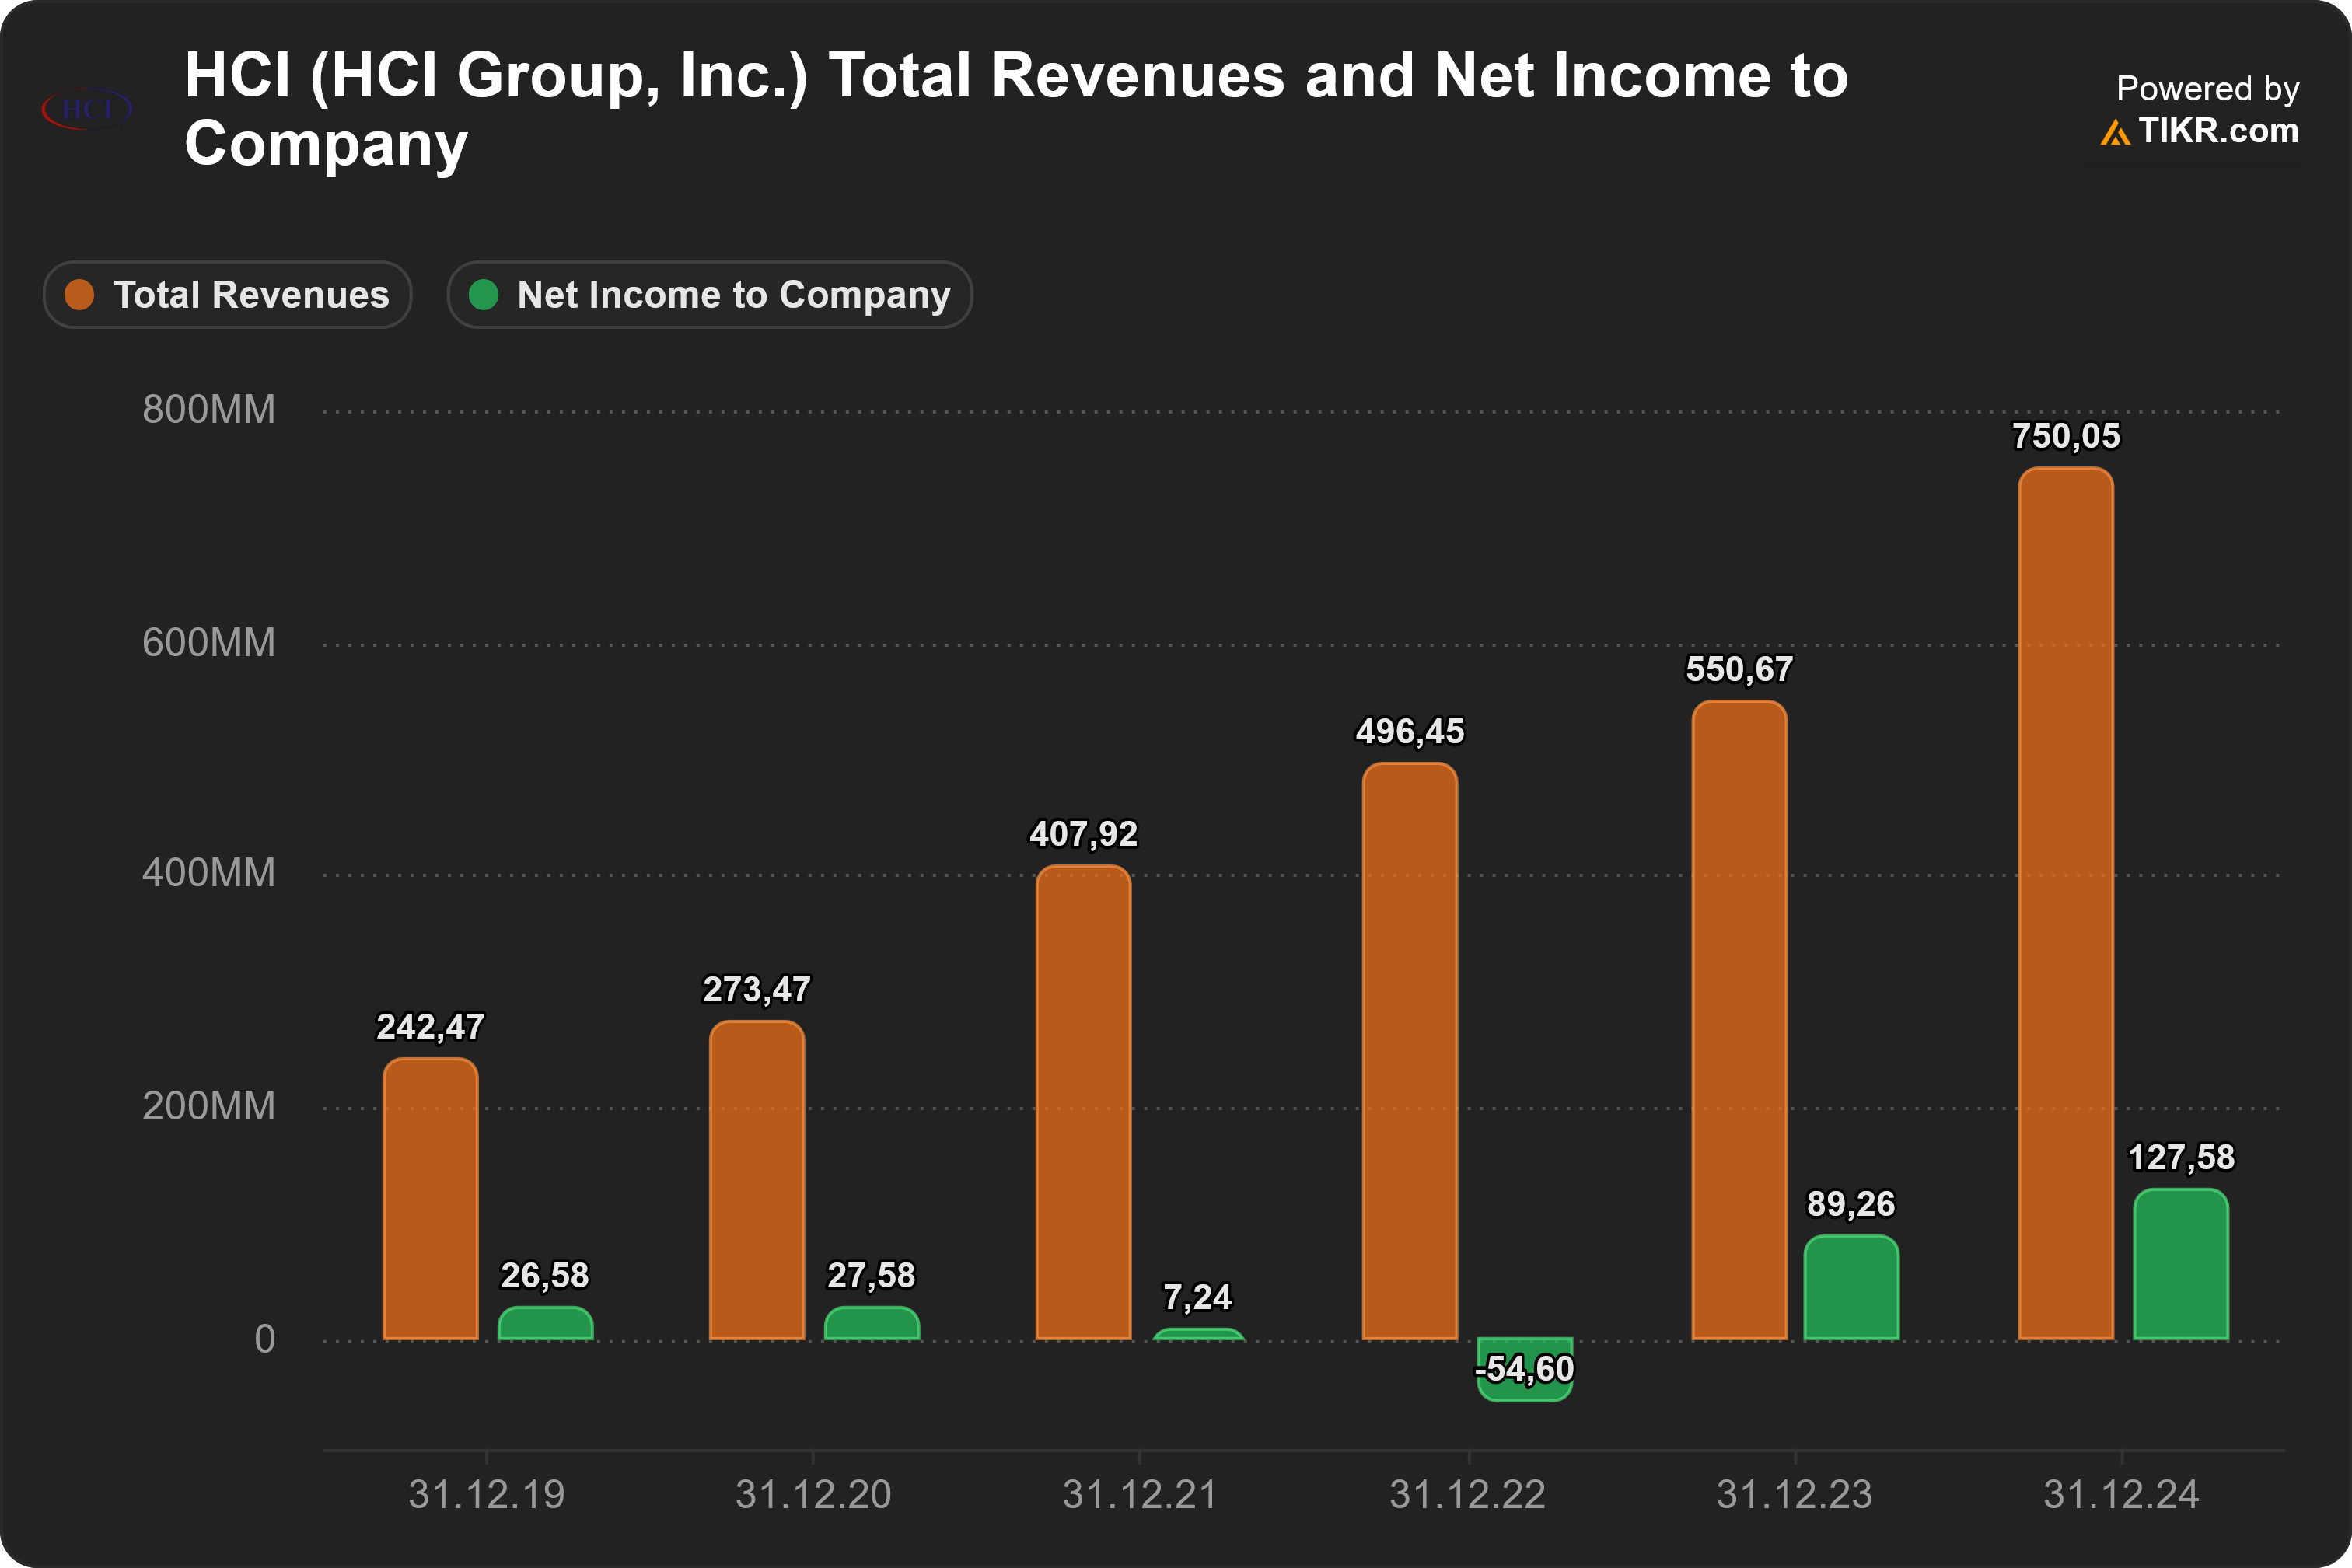
However, profitability clearly lagged scale for several years. Net income was modest in 2019 and 2020, weakened further in 2021, and then collapsed into a significant loss in 2022. That year stands out sharply in the chart: revenues continued to grow, but earnings swung deeply negative. This is the classic insurance problem—growth without protection when losses spike.
What follows in 2023 and 2024 is the most important part of the story. Net income rebounds hard, first to around $90m in 2023 and then to roughly $128m in 2024, far exceeding anything HCI had earned before. Importantly, this recovery happens on top of a much larger revenue base, indicating that the company didn’t just normalize—it began converting scale into profit. This is the moment where pricing, underwriting discipline, and a calmer loss environment start to show through in the numbers.
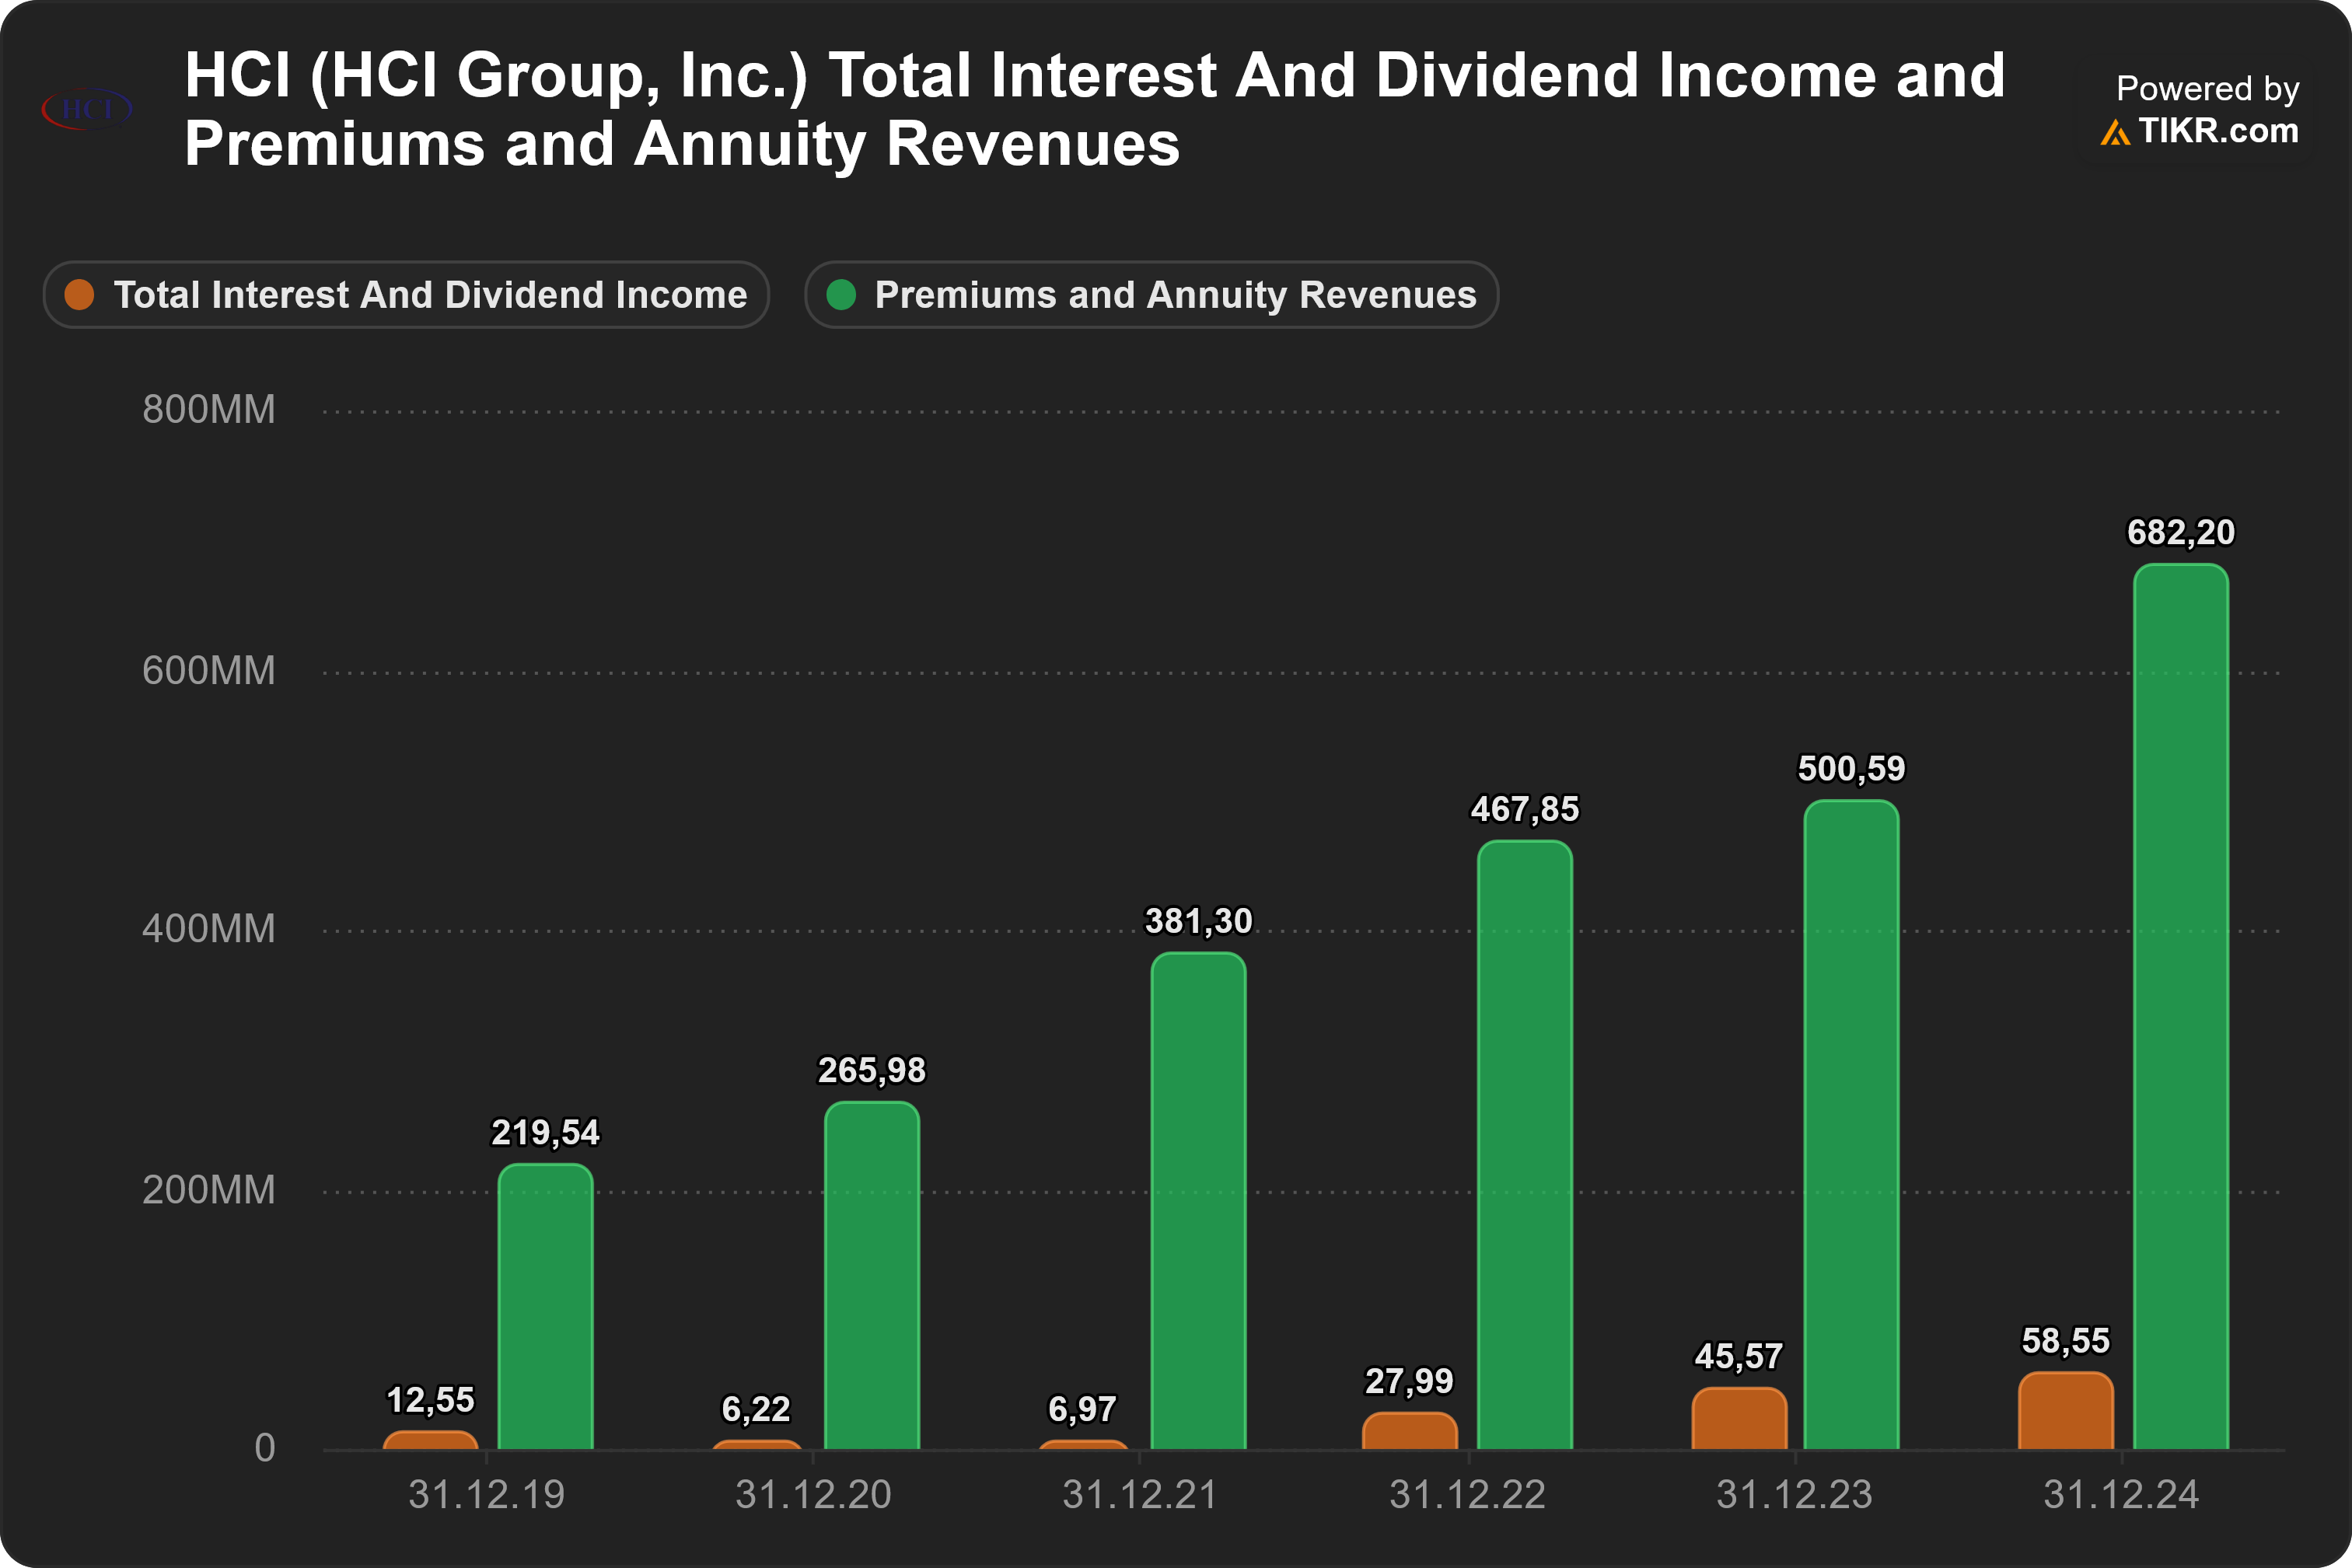
The premium revenue chart reinforces this point. Premiums and annuity revenues rise consistently every year, with no dip even during the loss year. That tells us the 2022 loss was not demand-related—it was loss-driven, not growth-driven. At the same time, interest and dividend income accelerates meaningfully after 2022, reflecting both higher invested assets and a more favorable rate environment. Earnings recovery, therefore, is coming from both sides of the income statement.
Profitability ratios: from capital destruction to capital compounding
The return-on-equity chart compresses this story into one brutal line. ROE was healthy in 2019 and 2020 at around 14%, collapsed close to zero in 2021, and turned sharply negative in 2022 (-16%). That is not cosmetic volatility—it is real capital destruction.
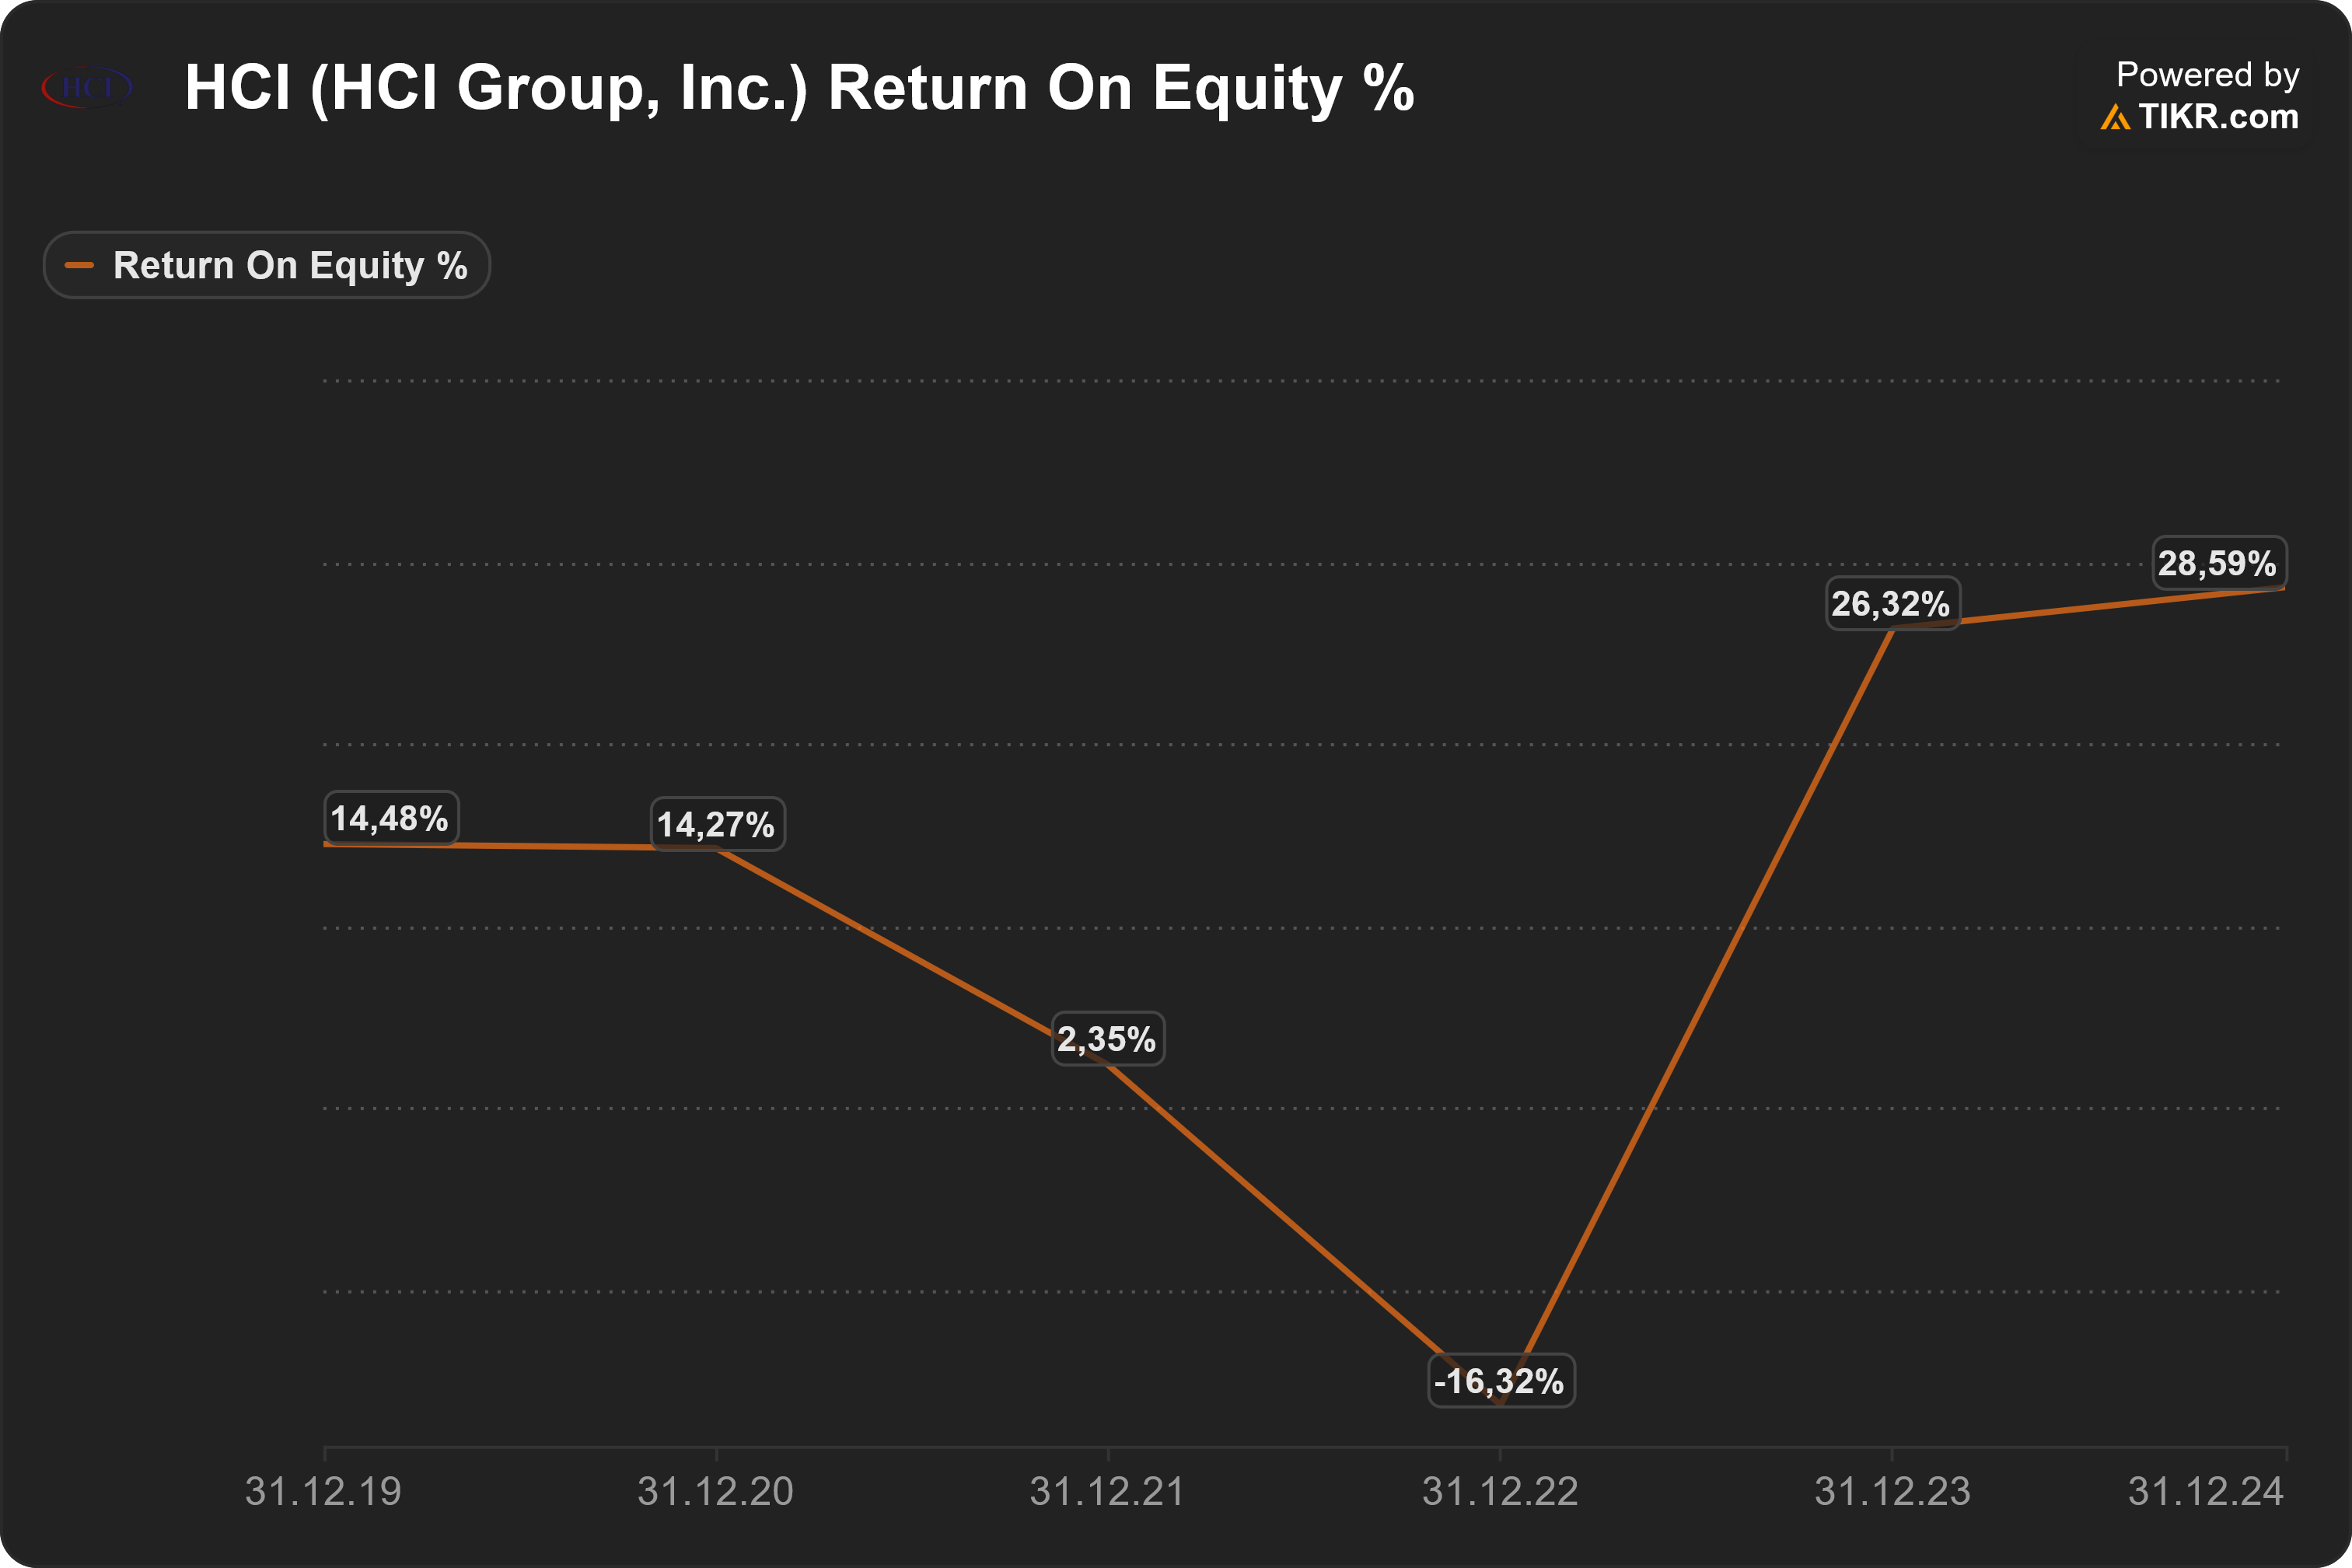
But the rebound is equally dramatic. ROE jumps to 26% in 2023 and climbs further to nearly 29% in 2024. These are not normal insurance returns. They imply that the post-2022 earnings are not just “okay again,” but exceptionally strong relative to equity.
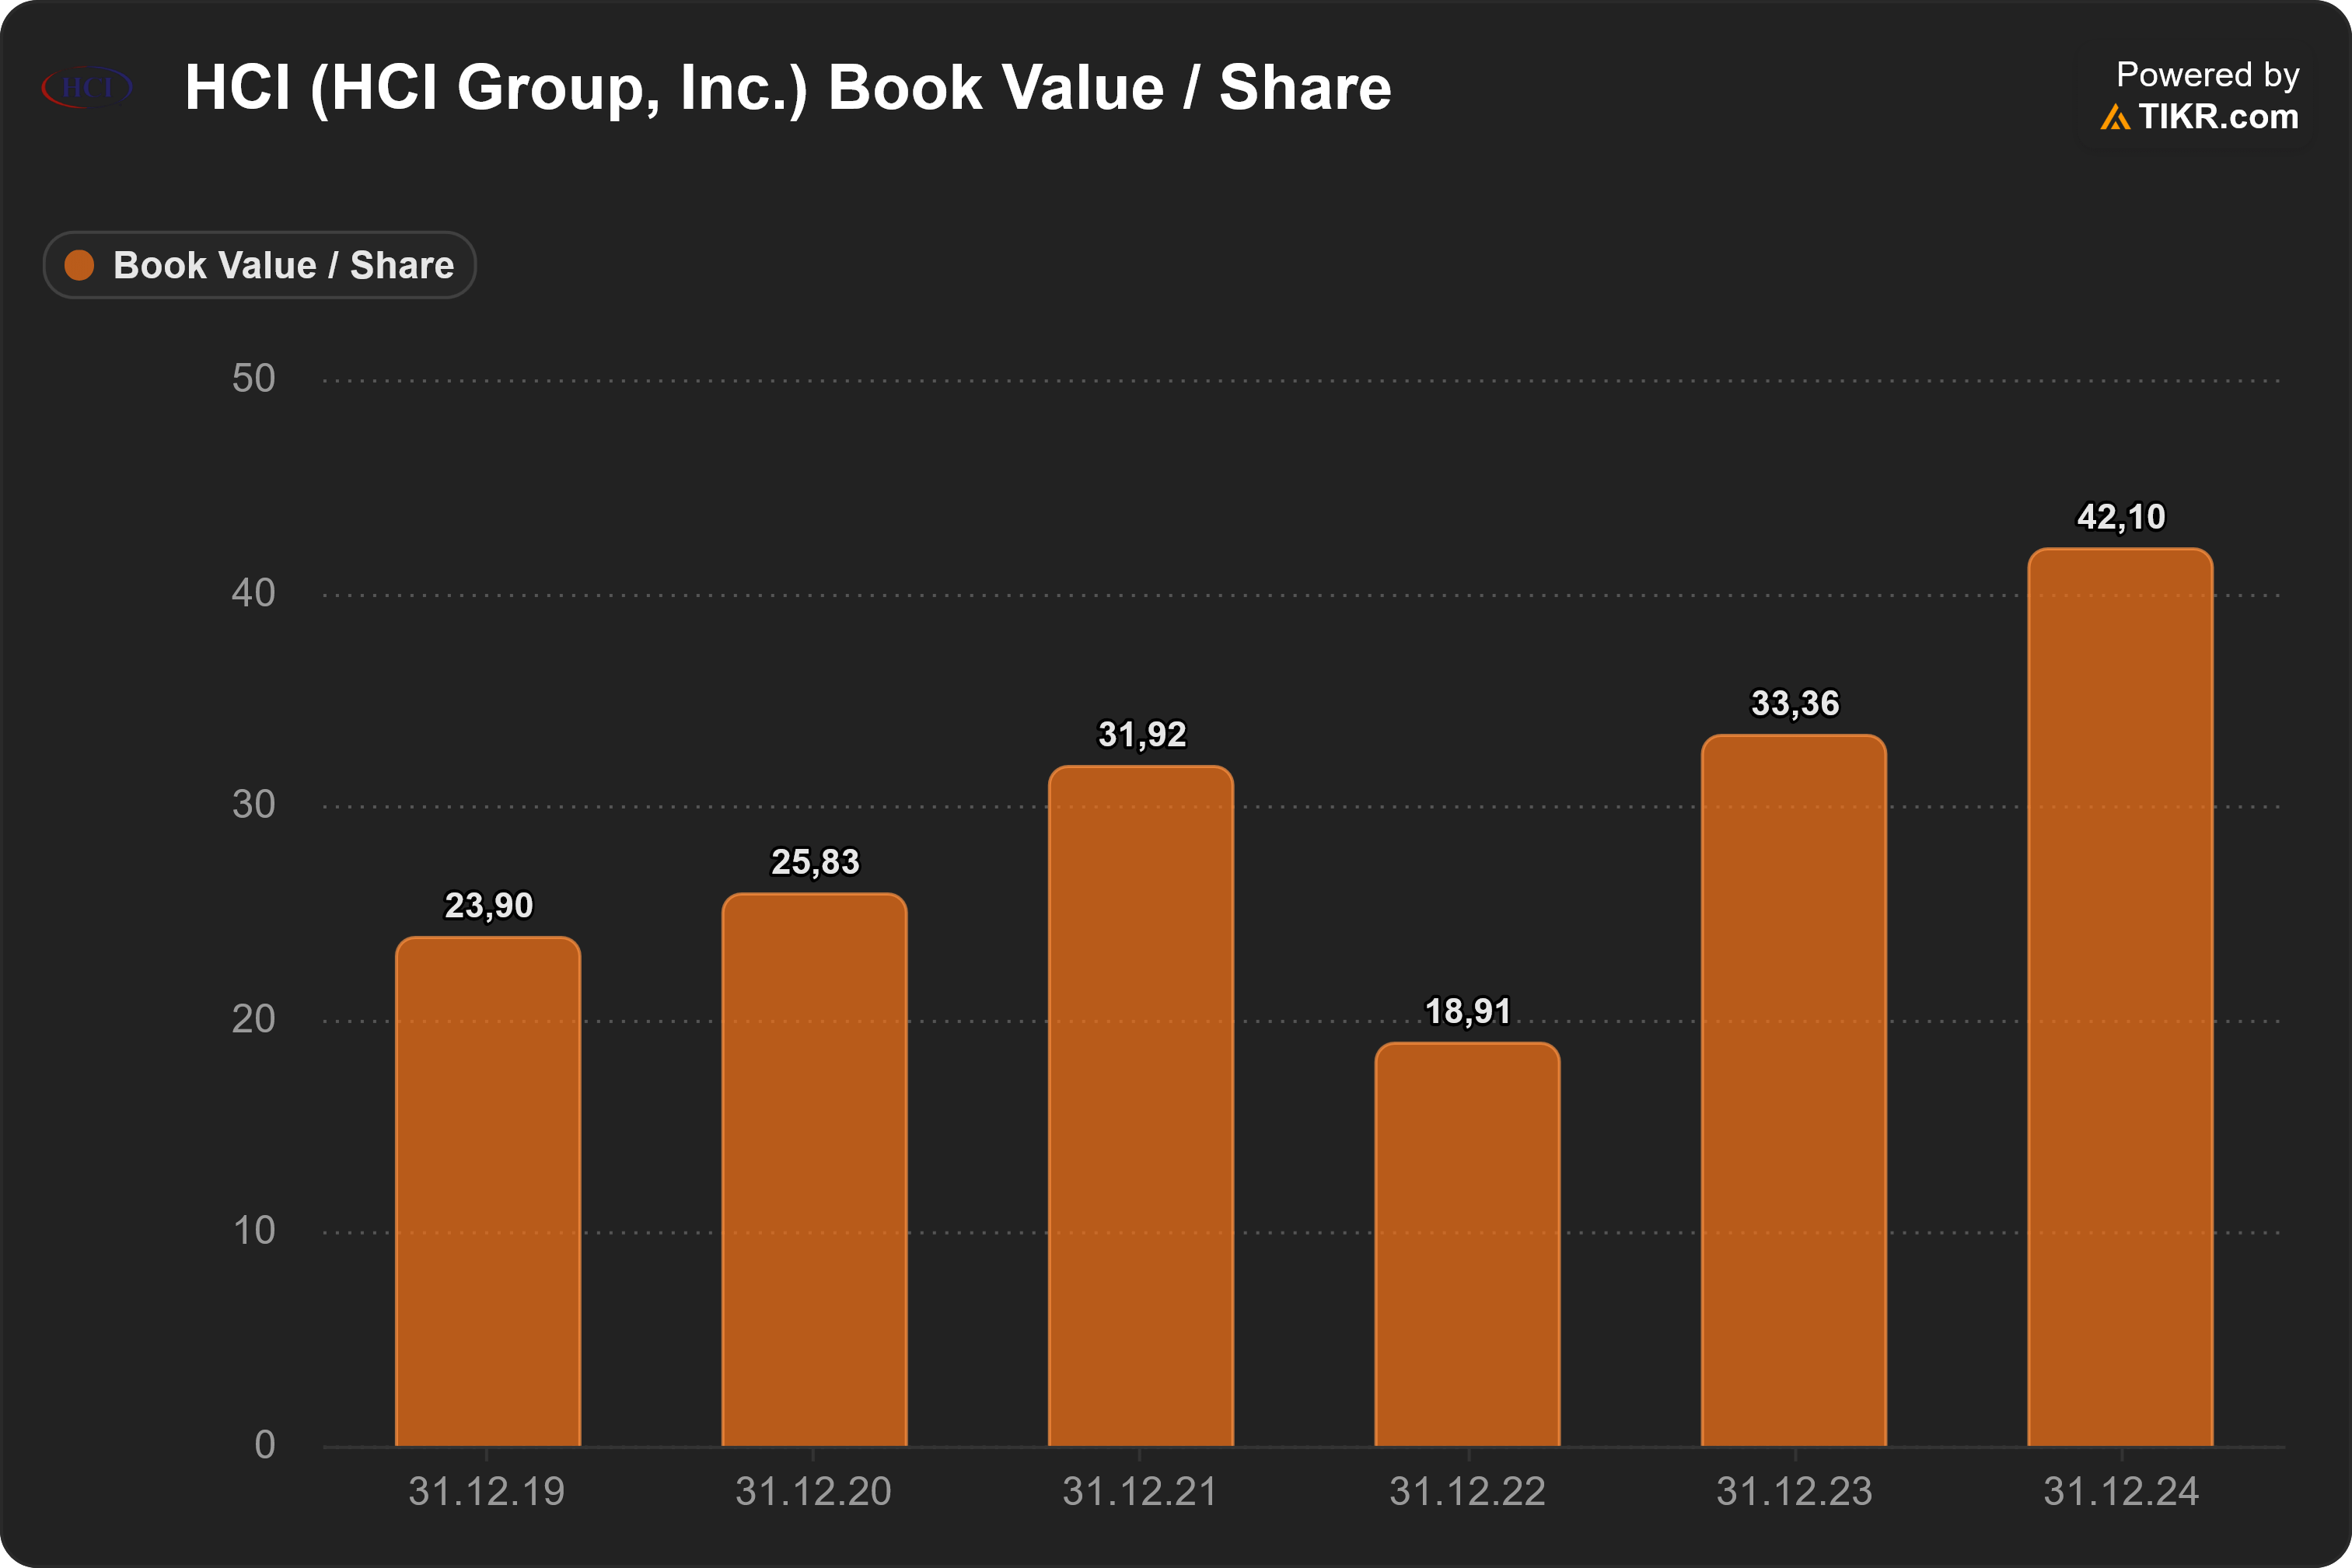
This is where the book value per share chart becomes critical. Book value grows steadily from 2019 through 2021, drops sharply in 2022 (reflecting the loss year), and then recovers faster than before, reaching over $42 per share by 2024, well above the pre-loss peak. That combination—negative ROE followed by very high ROE plus accelerating book value—is exactly what you want to see if a company has genuinely fixed the problem rather than masked it.
In simple terms: 2022 hurt, but it did not permanently impair the franchise. The capital base is now compounding again, and at a faster rate than before.
Balance sheet expansion: earnings with substance
The asset and equity growth strongly suggest that earnings are real and retained, not accounting noise. Total assets expand from about $800m in 2019 to over $2.2bn in 2024. Equity follows the same direction, rising from roughly $185m to nearly $470m.
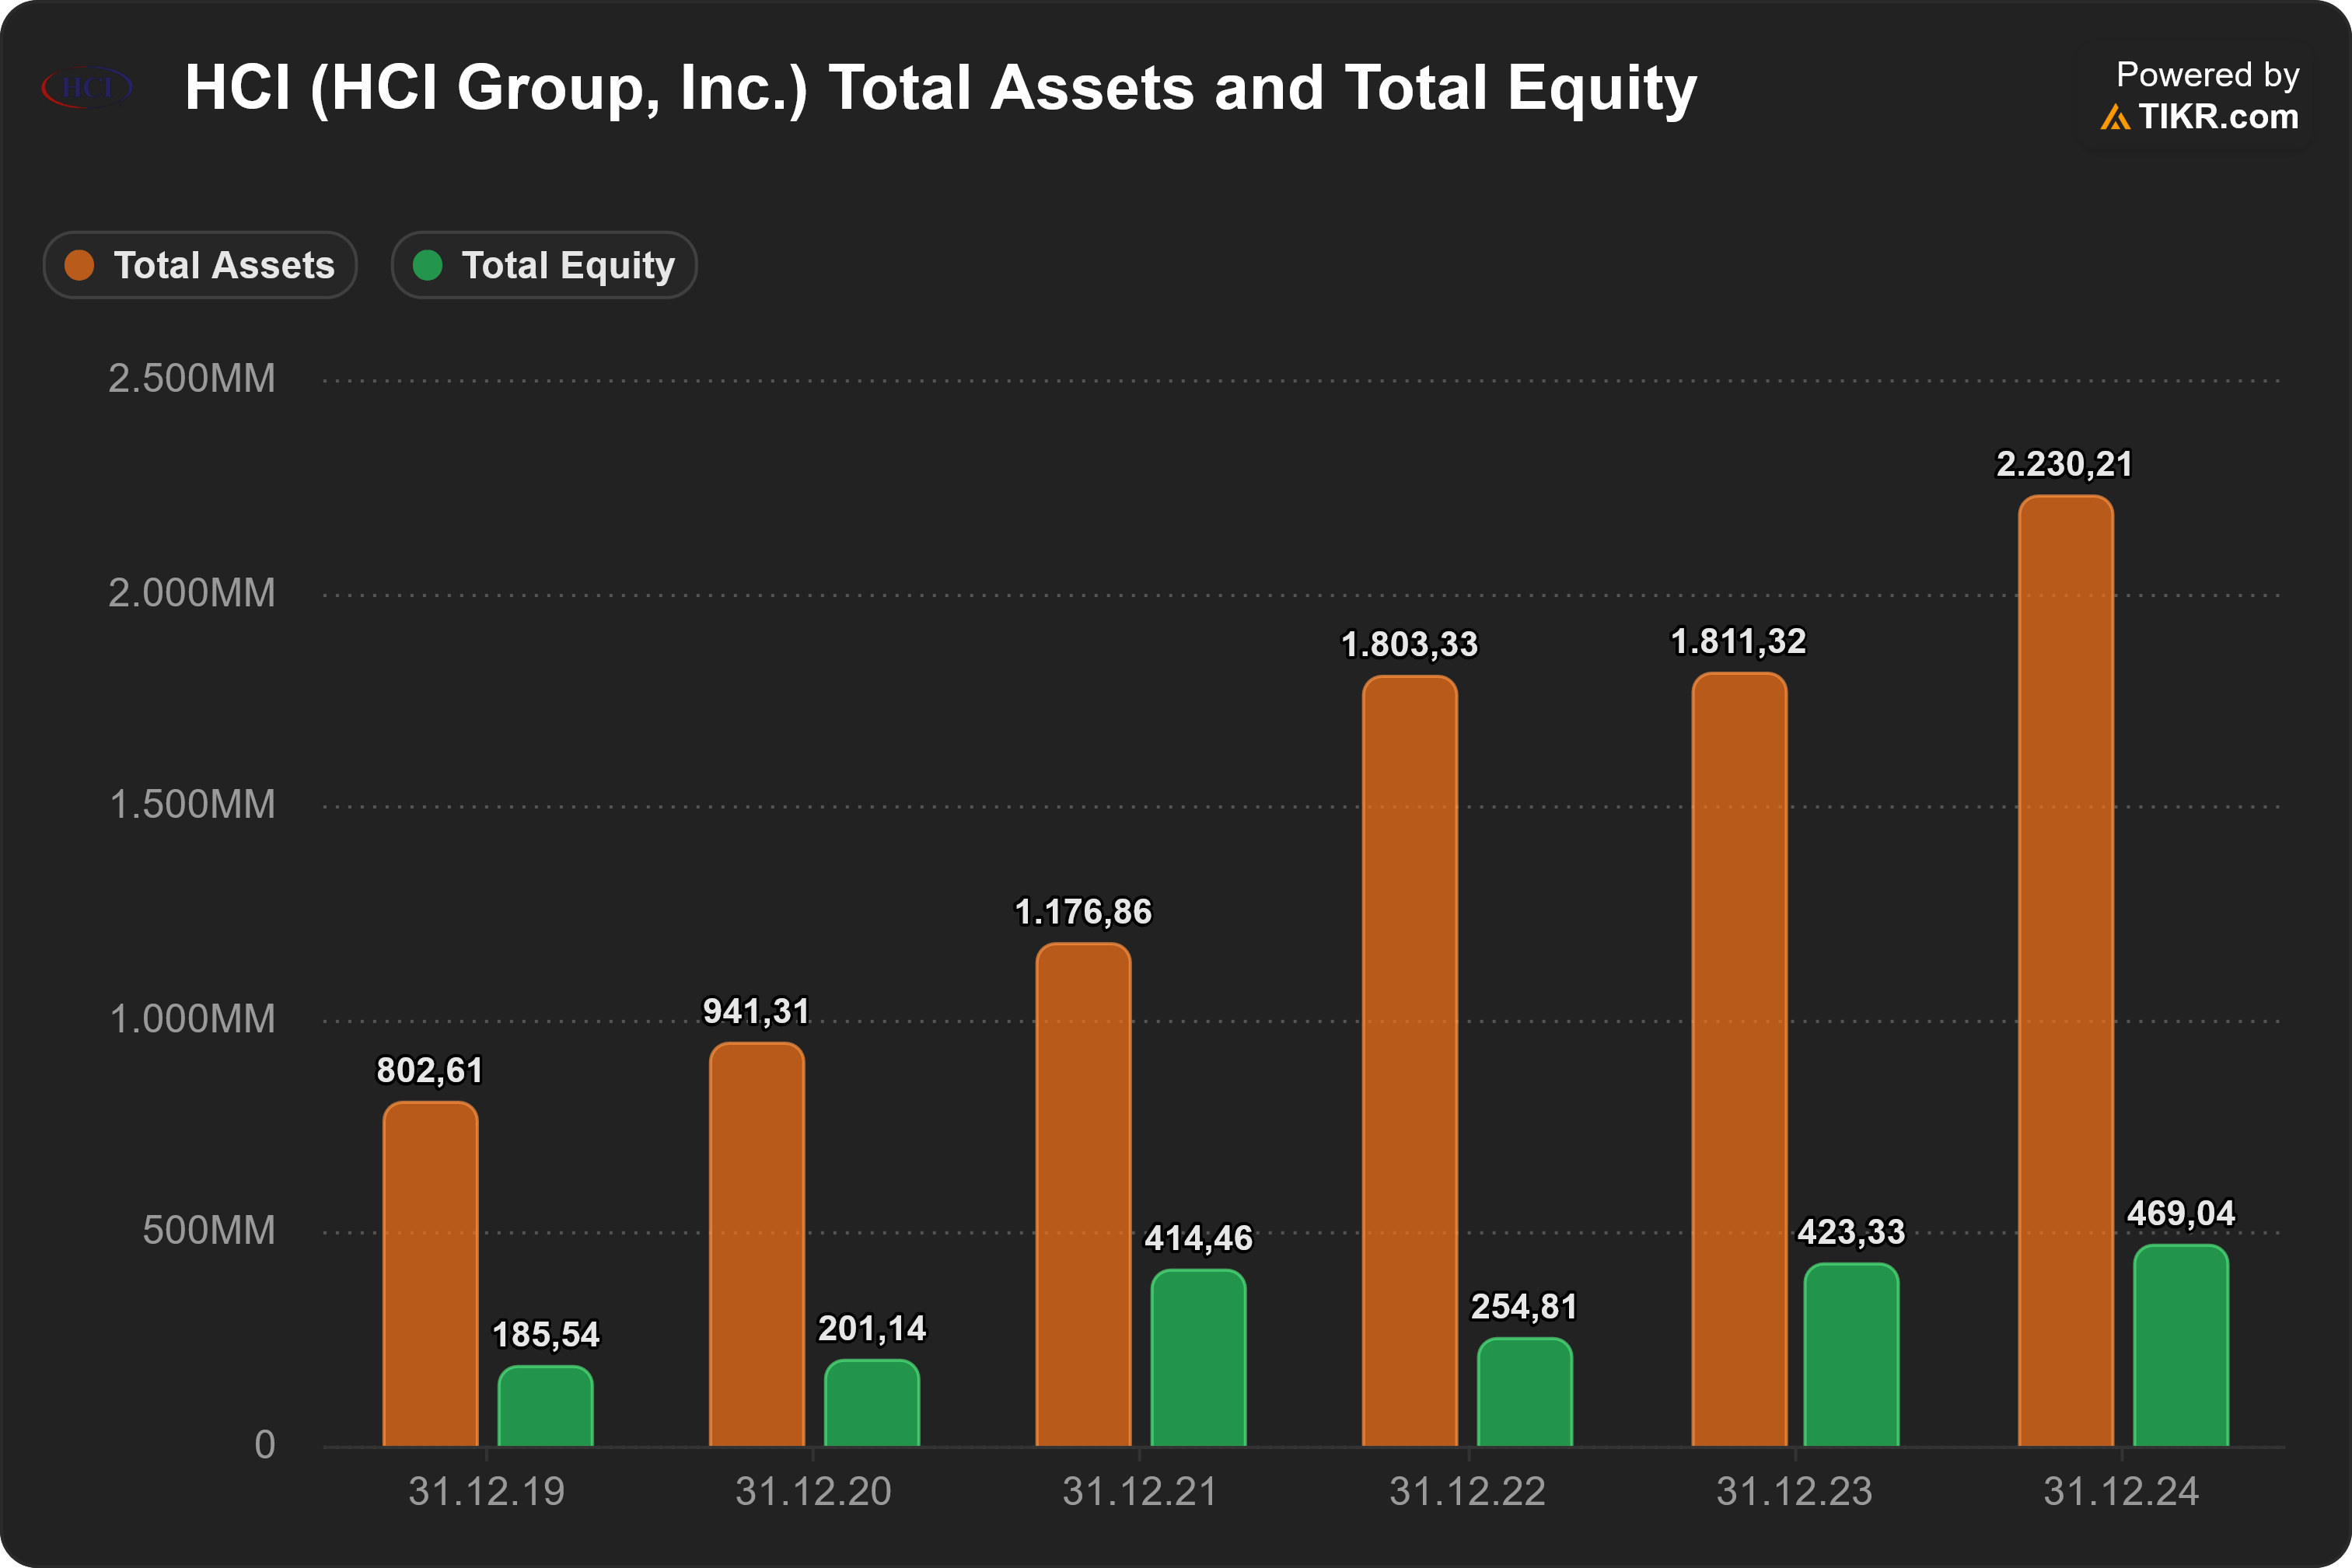
Two things matter here. First, equity growth clearly outpaces dilution concerns—book value per share rises strongly despite a much larger balance sheet. Second, the recovery after 2022 is not driven by leverage alone. Assets and equity grow together, meaning the business is expanding with capital, not on top of fragile capital.
The increasing contribution from interest and dividend income also implies that HCI is benefiting from a larger, better-yielding investment portfolio, which supports earnings stability going forward—assuming losses remain manageable.
Putting it all together
Taken together, the charts show a company that overreached into a loss cycle, absorbed a painful but survivable hit, and then emerged with a larger, more profitable, and more capital-efficient business. HCI today is not the same company it was in 2019—not just bigger, but structurally different.
This is the key takeaway: HCI is no longer in the “prove you can survive” phase. It is now in the “prove you can sustain” phase. The numbers suggest it can—but insurance history reminds us that the real test only comes when the next storm arrives.
Until then, the charts clearly show one thing: HCI has turned scale into earnings, and earnings into capital growth. That is the foundation of every long-term compounder—cyclical or not.
Business Model and Operations
HCI’s business model is built around one idea: a fully integrated, tech-enabled insurance platform designed to grow profitably in difficult markets. Its main revenue driver is property insurance premiums, with subsidiaries underwriting homeowners and related lines (wind, flood) for tens of thousands of Florida policyholders.
A major growth lever has been Florida’s “depopulation” programs, where private insurers assume policies from the state-run insurer of last resort. Founded in 2006 as Homeowners Choice, HCI has repeatedly cherry-picked large blocks of policies, re-underwritten them with its own data and pricing, and turned them profitable. Most notably, HCI assumed ~6,000 policies in late 2023 and another 47,000 policies (~$175 million in premiums) in October 2025. These takeouts instantly boost premium volume and—when selected carefully—can significantly enhance profitability.
What truly sets HCI apart is its technology-first mindset, which has evolved significantly over the past few years. Through its technology arm Exzeo, the company has built proprietary underwriting, quoting, and analytics platforms that power large parts of HCI’s insurance operations, including TypTap. These systems enable algorithmic underwriting, a streamlined agent workflow, and more precise risk selection, contributing to improved efficiency and loss ratios. This is not cosmetic tech: management has repeatedly emphasized that Exzeo’s platforms are a core competitive advantage and a key driver of underwriting performance.
External validation came in 2021, when a major private equity investor committed $100 million to TypTap, implying a valuation of roughly $850 million and confirming the strategic value of HCI’s insurtech capabilities. While the broader insurtech downturn in 2022 delayed monetization plans, HCI did not abandon the strategy. Instead, it restructured and rebranded its technology operations under Exzeo, clearly separating software from underwriting. That approach culminated in Exzeo’s IPO in late 2025, valuing the business at close to $2 billion, with HCI retaining a majority ownership stake.
Today, Exzeo represents a tangible, publicly listed validation of HCI’s long-term bet on technology — transforming what began as an internal efficiency tool into a standalone asset and a potential structural value catalyst alongside the core insurance business.
HCI has also expanded via policyholder-owned reciprocal exchanges, launching CORE in 2023 (condo associations) and Tailrow in 2025 (personal residential lines). These structures allow HCI to manage and earn fees without carrying all the risk on its own balance sheet. Tailrow began with ~14,000 assumed policies, while CORE targets the underserved condo insurance niche. Together, they give HCI additional growth capacity while reducing balance-sheet strain.
Given Florida’s hurricane risk, reinsurance is the backbone of HCI’s risk management. The company purchases extensive third-party reinsurance, taps the Florida Hurricane Cat Fund, and uses its fully collateralized captive reinsurer, Claddaugh, in Bermuda. This structure lets HCI retain profitable layers of risk while capping catastrophe exposure. The payoff was clear in 2022: despite gross losses exceeding $800 million from Hurricane Ian, HCI’s net losses were a fraction of that, thanks to reinsurance. It’s expensive—hundreds of millions in ceded premiums—but essential for survival and long-term compounding.
Vertical integration rounds out the model. Through Griston, HCI handles claims adjusting in-house, aiming for better cost control and service quality. Its real estate arm, Greenleaf Capital, owns income-generating Florida properties and provides optional liquidity; asset sales have periodically boosted earnings, including notable gains in 2023.
HCI is far more than a Florida homeowners insurer. It’s a data-driven underwriter, insurtech platform, reinsurance participant, and disciplined capital allocator. This integrated approach allows HCI to scale aggressively yet selectively, turning one of the toughest insurance markets in the U.S. into a long-term opportunity rather than a liability.
Strengths and Competitive Advantages
HCI Group brings a rare combination of discipline, agility, and innovation—a mix that strongly supports its investment appeal. Its key strengths stand out clearly:
Disciplined Underwriting & Superior Loss Control
HCI’s underwriting performance in 2025 has been exceptionally strong, with a net combined ratio of just 64% in Q3 2025, a remarkably low level for the industry and a testament to disciplined risk selection, smart pricing, and effective loss control. HCI focuses on insuring homes that meet strict quality and risk criteria and exits segments that look unprofitable. Its loss ratios and lower claims frequency have benefited from both rate increases and favorable weather conditions. While TypTap’s original insurtech business has evolved into the standalone Exzeo technology platform, that platform continues to support underwriting excellence and operational efficiency. Exzeo itself has shown strong revenue and income growth in 2025 and now trades publicly, further validating HCI’s tech-enabled approach to underwriting and distribution.
Opportunistic Growth in Times of Chaos
HCI excels at turning industry stress into opportunity. When others retreat, HCI expands—most visibly by assuming large blocks of Citizens policies, sometimes tens of thousands at once. It has also opportunistically acquired books of business outside Florida and launched new carriers like Tailrow and CORE to fill gaps left by retreating competitors. Rather than relying solely on slow, organic growth, HCI uses policy takeouts, targeted M&A, and first-mover product launches to scale quickly when the odds are favorable.
Technology & Data as a True Competitive Advantage
Unlike many regional insurers, HCI built its own proprietary insurance technology stack. Its Exzeo platform enables faster quoting, better pricing, lower expenses, and smarter risk selection. This tech isn’t just supportive—it’s valuable in its own right. The IPO of Exzeo in 2025, at a multi-billion-dollar valuation, unlocked significant hidden value for shareholders and highlighted HCI’s deep insurtech DNA. Few insurers of this size can claim to have built a standalone tech asset of that caliber.
Strong Capital Management & Fortress Balance Sheet
HCI’s balance sheet has strengthened dramatically. Book value roughly doubled in two years, driven by retained earnings and savvy capital allocation. Management has shown a clear “buy low, sell high” mindset—repurchasing shares when cheap and issuing equity only when valuations were attractive. With low leverage, ample liquidity, and nearly $1 billion in cash and investments, HCI has the financial firepower to weather major storms—or capitalize on the next opportunity.
Shareholder-Friendly Culture
Despite being a small-cap, HCI acts like a shareholder-first company. It has paid a steady dividend ($1.60 annually) for years—never cutting it, even during loss-making periods. Insider ownership is meaningful, aligning management with long-term shareholders. Buybacks when undervalued, disciplined dilution when overvalued, and inclusion in major small-cap indices all reinforce management’s focus on value per share, not empire-building.
Weaknesses and Key Risk Factors
Despite its strengths, HCI Group is not a low-risk investment. Several structural and cyclical risks deserve close attention:
Extreme Exposure to Florida Hurricanes
HCI’s biggest risk is simple and unavoidable: Florida weather. The company is heavily exposed to hurricanes, and one major storm can erase a year (or more) of profits. Even with extensive reinsurance, HCI still retains meaningful risk. The impact of Hurricane Ian in 2022, which contributed to a $55 million net loss, is a clear reminder. A direct hit on Tampa or Miami by a Category 4–5 storm would almost certainly hurt earnings and book value. In short, HCI carries tail risk—low probability, high severity events that make results inherently volatile and weather-dependent.
High Geographic & Product Concentration
HCI remains, at its core, a Florida homeowners insurer. Over 90% of premiums come from this single state and line of business. While expansion efforts exist, meaningful diversification outside Florida is still limited. This concentration amplifies exposure not only to hurricanes, but also to Florida-specific risks such as regulatory shifts, litigation trends, or market dysfunction. If the state’s insurance environment deteriorates again—or reforms stall—HCI would feel the impact disproportionately.
Heavy Reliance on Reinsurance
HCI’s model depends on access to affordable reinsurance, which consumes a large share of premiums each year. If reinsurance pricing continues to rise—or capacity tightens after a major global catastrophe—margins could be squeezed or growth constrained. While HCI mitigates counterparty risk by spreading coverage across many highly rated reinsurers and using collateralized structures, reinsurance remains a structural dependency largely outside management’s control.
Regulatory and Legal Uncertainty
Florida’s insurance market operates under constant regulatory scrutiny. While recent legal reforms have helped curb abuse, there’s no guarantee they will remain intact. Political pressure to cap rates, restrict non-renewals, or protect consumers after storms could undermine profitability. Additionally, HCI’s growth strategy relies on regulatory approvals—particularly for Citizens policy assumptions and the operation of reciprocal exchanges. Any slowdown or rule change could limit expansion.
Execution & Complexity Risk
HCI’s integrated model brings operational complexity. Managing large policy takeouts, expanding into new states, running multiple insurance entities, and scaling technology initiatives all at once increases execution risk. Mispricing new books of business, operational strain, or talent shortages could slow momentum. Growth outside Florida—especially in unfamiliar regulatory or weather environments—remains unproven.
🔒 The rest of this article is for paid subscribers
If you choose to upgrade, you’ll get access to the full deep dive – including the companies dividend policy and buyback activity, valuation breakdowns, and both the bullish and bearish investment case. In every paid section, I go beyond the headlines and share detailed numbers, scenarios, and outlooks that long-term investors can actually use. It’s where I connect the dots between financial performance, strategy, and what it means for your portfolio.