

Disclaimer: The information provided in this publication is for educational and informational purposes only and does not constitute financial advice. The content is solely reflective of my personal views and opinions based on my research and is not intended to be used as a basis for investment decisions. While every effort is made to ensure that the information is accurate and up-to-date, the writer makes no representations as to the accuracy, completeness, suitability, or validity of any information in this post and will not be liable for any errors, omissions, or delays in this information or any losses, injuries, or damages arising from its display or use. All readers are advised to conduct their own independent research or consult a professional financial advisor before making any investment decisions. The author is not invested in the mentioned stock.
E-Book and Paperback “Investing in Small-Caps - The ultimate Guide”

Introduction
Coconut water doesn’t usually scream investment case. It sounds more like something you grab after a workout than something you build a serious long-term thesis around. And yet, over the past few years, The Vita Coco Company has quietly transformed itself from a trendy beverage brand into something far more interesting: a profitable, cash-generative category leader that has already survived a real stress test.
This post isn’t about hype or vibes. It’s about what actually happened inside the business—year by year—when costs exploded, margins collapsed, and then, just as quickly, recovered. It’s about how a seemingly simple product scaled globally, how an asset-light model behaved under pressure, and why the numbers today look very different from just a few years ago.
We’ll walk through the company’s revenue growth, profit volatility, margin dynamics, cash flow swings, and balance sheet strength—and what those trends really say about the quality of the business beneath the brand. Some of the charts tell a reassuring story. Others are more uncomfortable. Together, they explain why Vita Coco is no longer just a “growth brand,” and why expectations around the stock have risen so sharply.
If you’ve ever wondered whether Vita Coco is just riding a trend—or quietly building a durable, high-return business, the numbers have a lot to say.
Company Overview
The Vita Coco Company COCO 0.00%↑ is a leading plant-based functional hydration brand, best known for turning coconut water into a global lifestyle beverage. Founded in 2004 by Michael Kirban and Ira Liran, the company transformed a simple idea—bottled coconut water—into an entirely new drink category. Its mission is clear: deliver natural, nutritious beverages that are better for consumers and better for the planet.
While Vita Coco coconut water remains the flagship, the portfolio has expanded into coconut oil, coconut juice, coconut milk, and newer growth bets like Ever & Ever (sustainably packaged water) and PWR LIFT (a protein-infused fitness drink). (Not every experiment stuck—its plant-based energy drink Runa was discontinued in 2023.)
The company went public in October 2021 and operates as a public benefit corporation, underscoring its commitment to social and environmental responsibility. Vita Coco follows an asset-light business model, sourcing coconuts from 17 partner factories across Asia and Latin America and working with thousands of farmers, while outsourcing production and distribution. This setup keeps the company flexible, scalable, and capital-efficient.
Today, Vita Coco products are sold in 35+ countries, with North America, the U.K., and Europe as core markets. In the U.S., Vita Coco dominates with over 40% market share, successfully fending off challenges from giants like Coca-Cola and Pepsi. Its international strength is just as impressive—82% market share in the U.K. alone.
Latest Financials
Vita Coco’s financials show a company that picked up speed in late 2024 and is now firing on all cylinders in 2025. In FY 2024, net sales reached $516 million (+5% YoY). While headline growth was modest, the core Vita Coco Coconut Water brand grew a strong 10%, highlighting continued consumer demand. Gross profit rose to $199 million, pushing gross margin up to 39% (from 37%), driven by pricing and cost improvements. Net income climbed to $56 million, up from $47 million in 2023—proof that Vita Coco can expand earnings even without explosive revenue growth.
Momentum clearly accelerated toward year-end. In Q4 2024, net sales jumped 20% YoY to $127 million, helped by a rebound from earlier inventory shortages. The Vita Coco brand surged 30% in Q4, confirming strong underlying demand once shelves were restocked. Margins dipped temporarily (to 32%) due to higher costs and mix effects, pulling Q4 net income down to $3 million, but this was largely a timing issue rather than a structural problem. Crucially, the company entered 2025 with normalized inventories and accelerating sales.
And 2025 has delivered. Through the first nine months of 2025, net sales are up a striking +24% YoY to $482 million. Q3 2025 revenue surged 37%, fueled by a ~42% jump in Vita Coco Coconut Water sales, driven by both higher volumes and improved availability. A new product launch—the Vita Coco “Treats” chocolate coconut milk line—also paid off, nearly doubling the “Other” product category in Q3. Year-to-date, flagship coconut water sales are up over 30%, easily offsetting weakness in private label.
Q3 2025 Call: “Our International segment continued to deliver exceptionally strong results in the third quarter, with net sales up 48% and 47%, driven by strong growth across our major markets.”
This growth is now translating directly into profits. Net income for the first nine months of 2025 rose to $65.8 million, up from $52.6 million a year earlier. Q3 EPS hit $0.40, beating expectations and rising 18% YoY. Adjusted EBITDA reached $32.4 million, a healthy 17.8% of sales, far above estimates. Cash generation has also surged, with free cash flow margins near 20% in Q3, up sharply from last year.
Financial History
Looking at The Vita Coco Company over the past five years, the financials tell a story that’s more interesting than a simple growth chart. This is a business that scaled rapidly, absorbed a severe cost shock, and then emerged with meaningfully better economics. The four charts together capture that arc very clearly.
Revenues, Operating Income, and Net Income: Growth Never Stopped — Margins Did
Start with the top line. Revenues grew every single year, rising from about $311 million in 2020 to $516 million in 2024. That alone matters. Even during periods of margin stress, Vita Coco continued to push product through the system, expand distribution, and grow household penetration. There was no demand cliff.
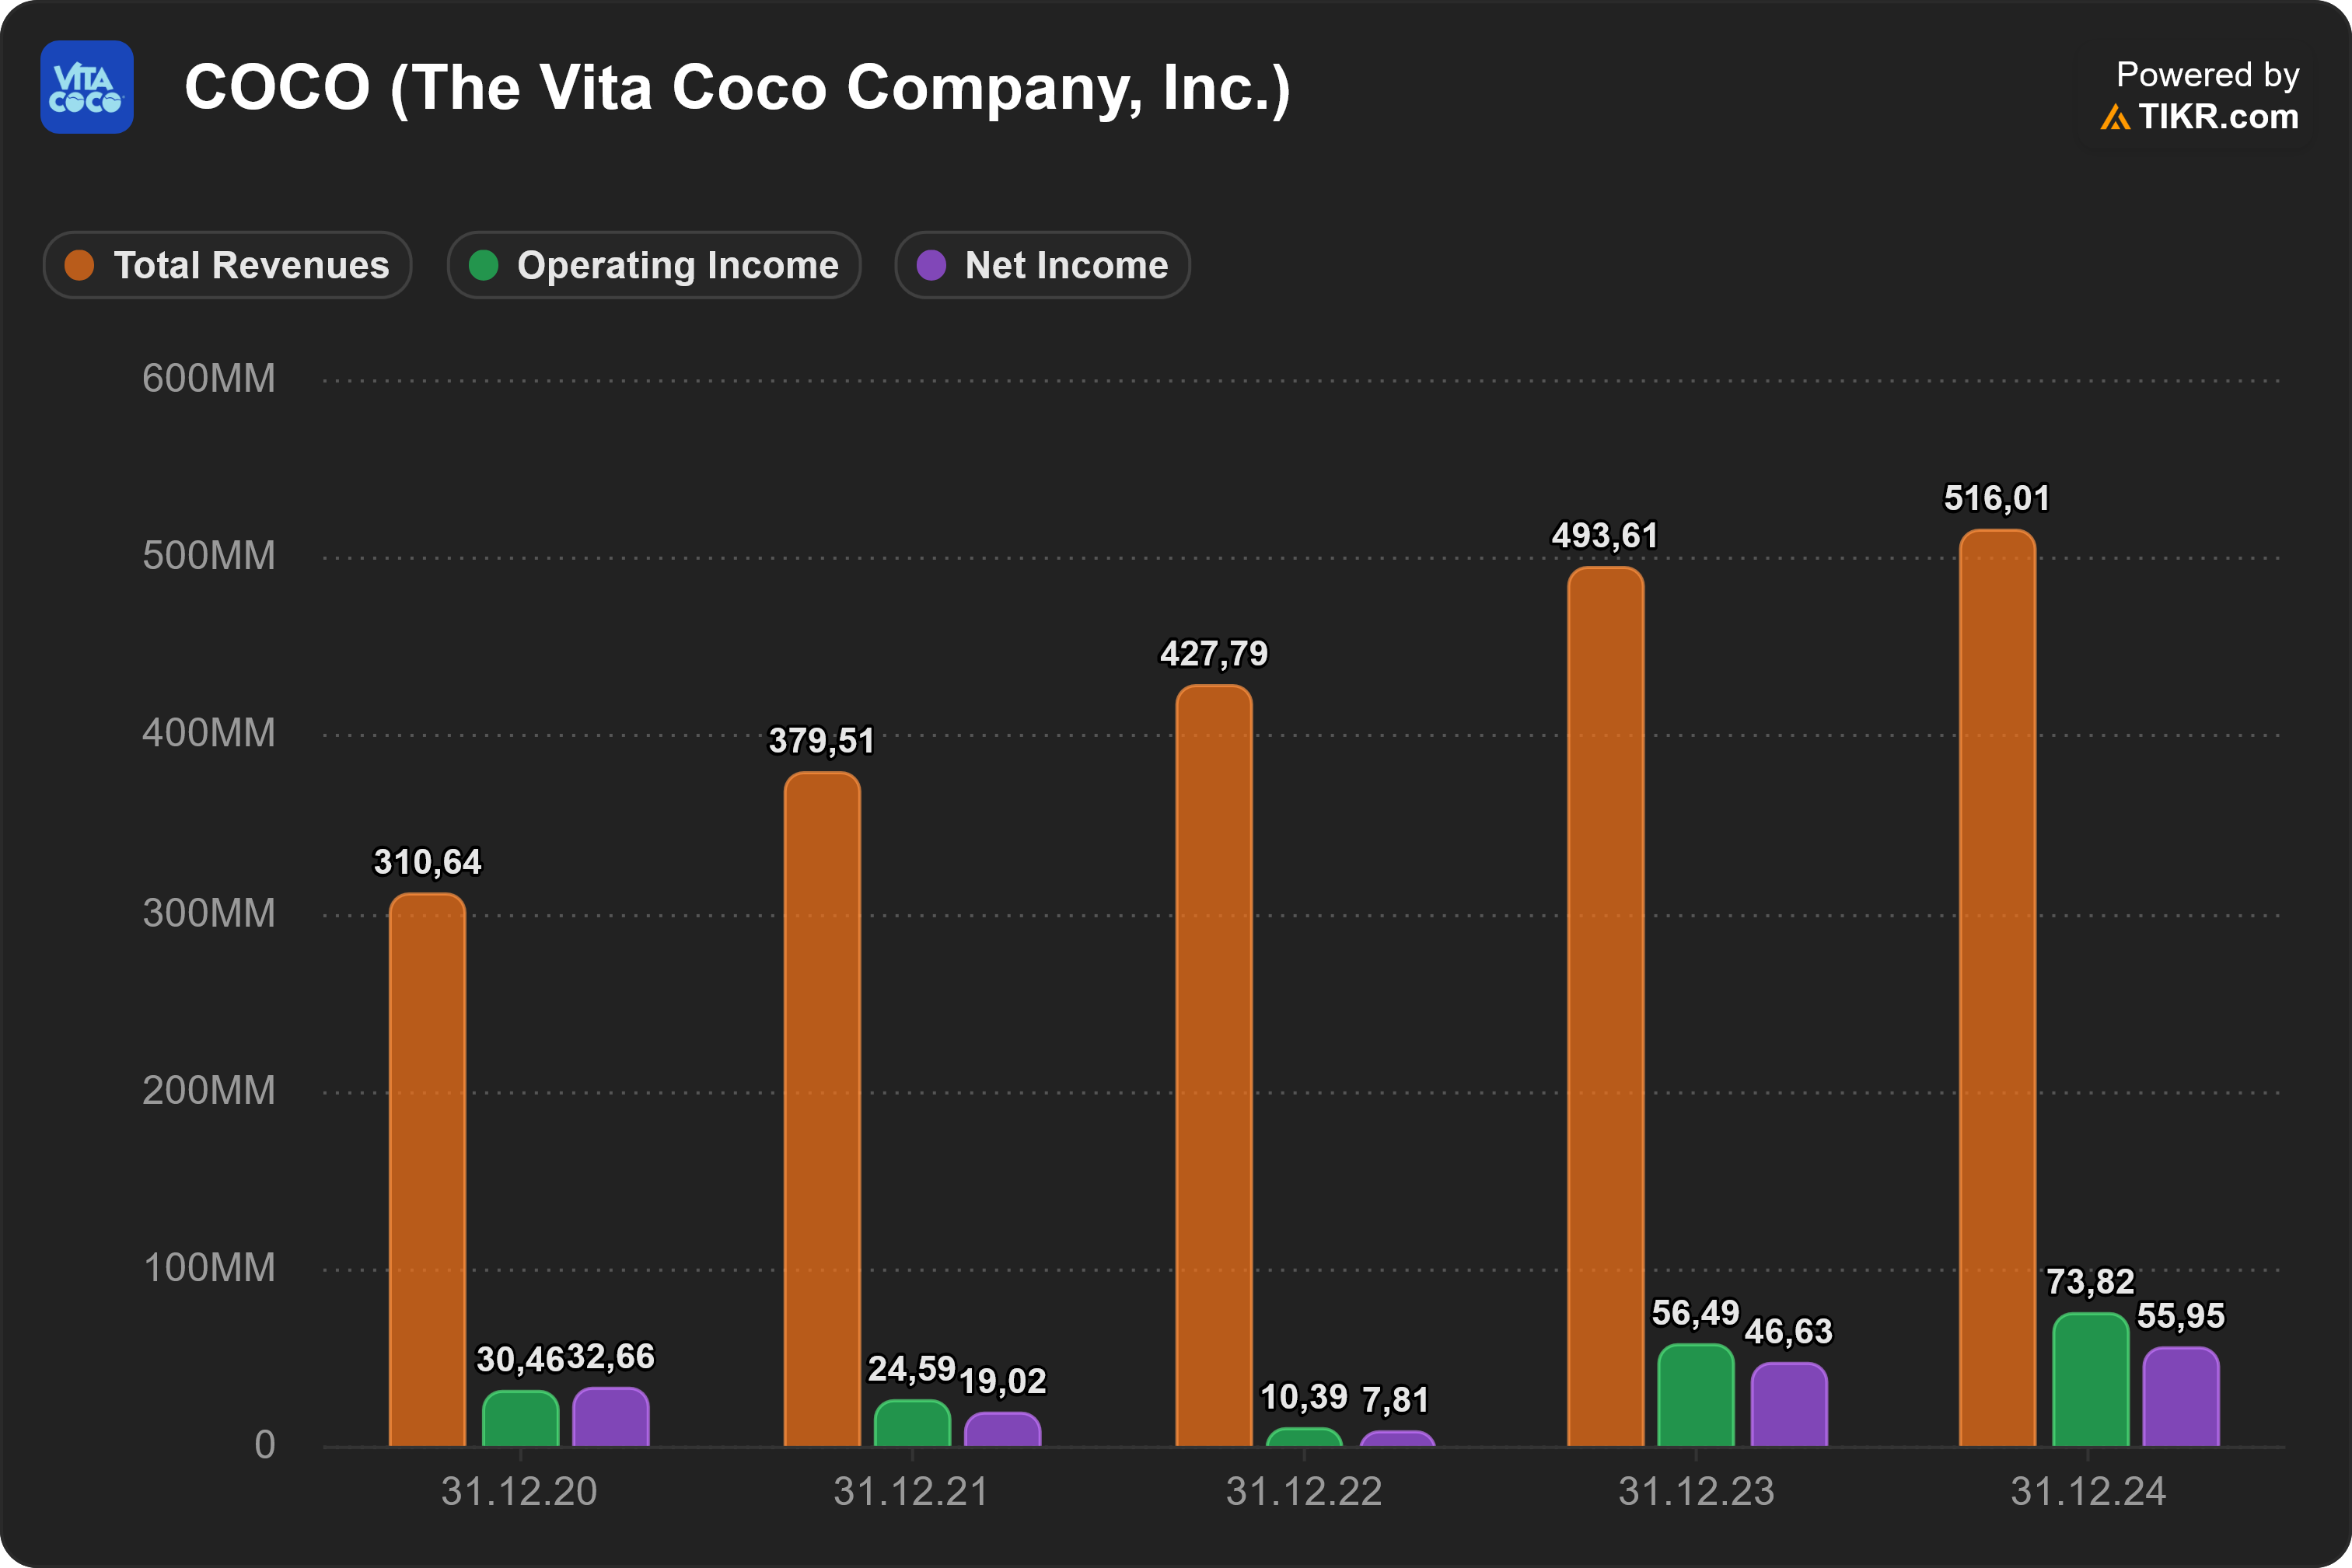
The profit lines, however, show that the path was anything but smooth.
In 2020, profitability was unusually strong. Operating income and net income benefited not just from healthy demand, but also from one-off items that boosted reported results. As a result, margins in that year look especially high relative to what the business would later sustain on a normalized basis.
In 2021, revenue growth remained strong, but profitability cooled. Operating income and net income both declined versus 2020 — not because the business deteriorated, but because costs normalized and the prior year’s tailwinds faded. Still, Vita Coco remained solidly profitable.
Then came 2022, the stress test. Revenues continued to rise, but operating income and net income collapsed. Operating profitability fell to very low single digits, and net income margins briefly dropped below 2%. This wasn’t a demand issue — it was a cost and execution issue. Inflation in freight, packaging, and coconut sourcing, combined with supply-chain inefficiencies, compressed margins hard. Importantly, management chose to protect shelf space and volumes, rather than pull back aggressively to defend margins.
What followed is the most important part of the story.
In 2023 and 2024, profitability snapped back decisively. Operating income rose to roughly $56 million in 2023 and $74 million in 2024, while net income climbed to about $46 million and $56 million, respectively. These weren’t just recoveries to prior levels — 2024 profitability exceeded every pre-2021 year. That tells us the business didn’t merely survive the cost shock; it reasserted its operating leverage once conditions stabilized.
Margins and Returns: From Compression to Best-in-Class
The margin and return chart confirms this progression.
Operating (EBIT) margins fell steadily from 2020 through 2022, bottoming out in the low single digits during the worst of the cost inflation period. But in 2023, EBIT margins rebounded sharply into double digits — and in 2024, they expanded further into the mid-teens. Net income margins followed the same trajectory, reaching ~11% in 2024, a very strong level for a branded beverage company.
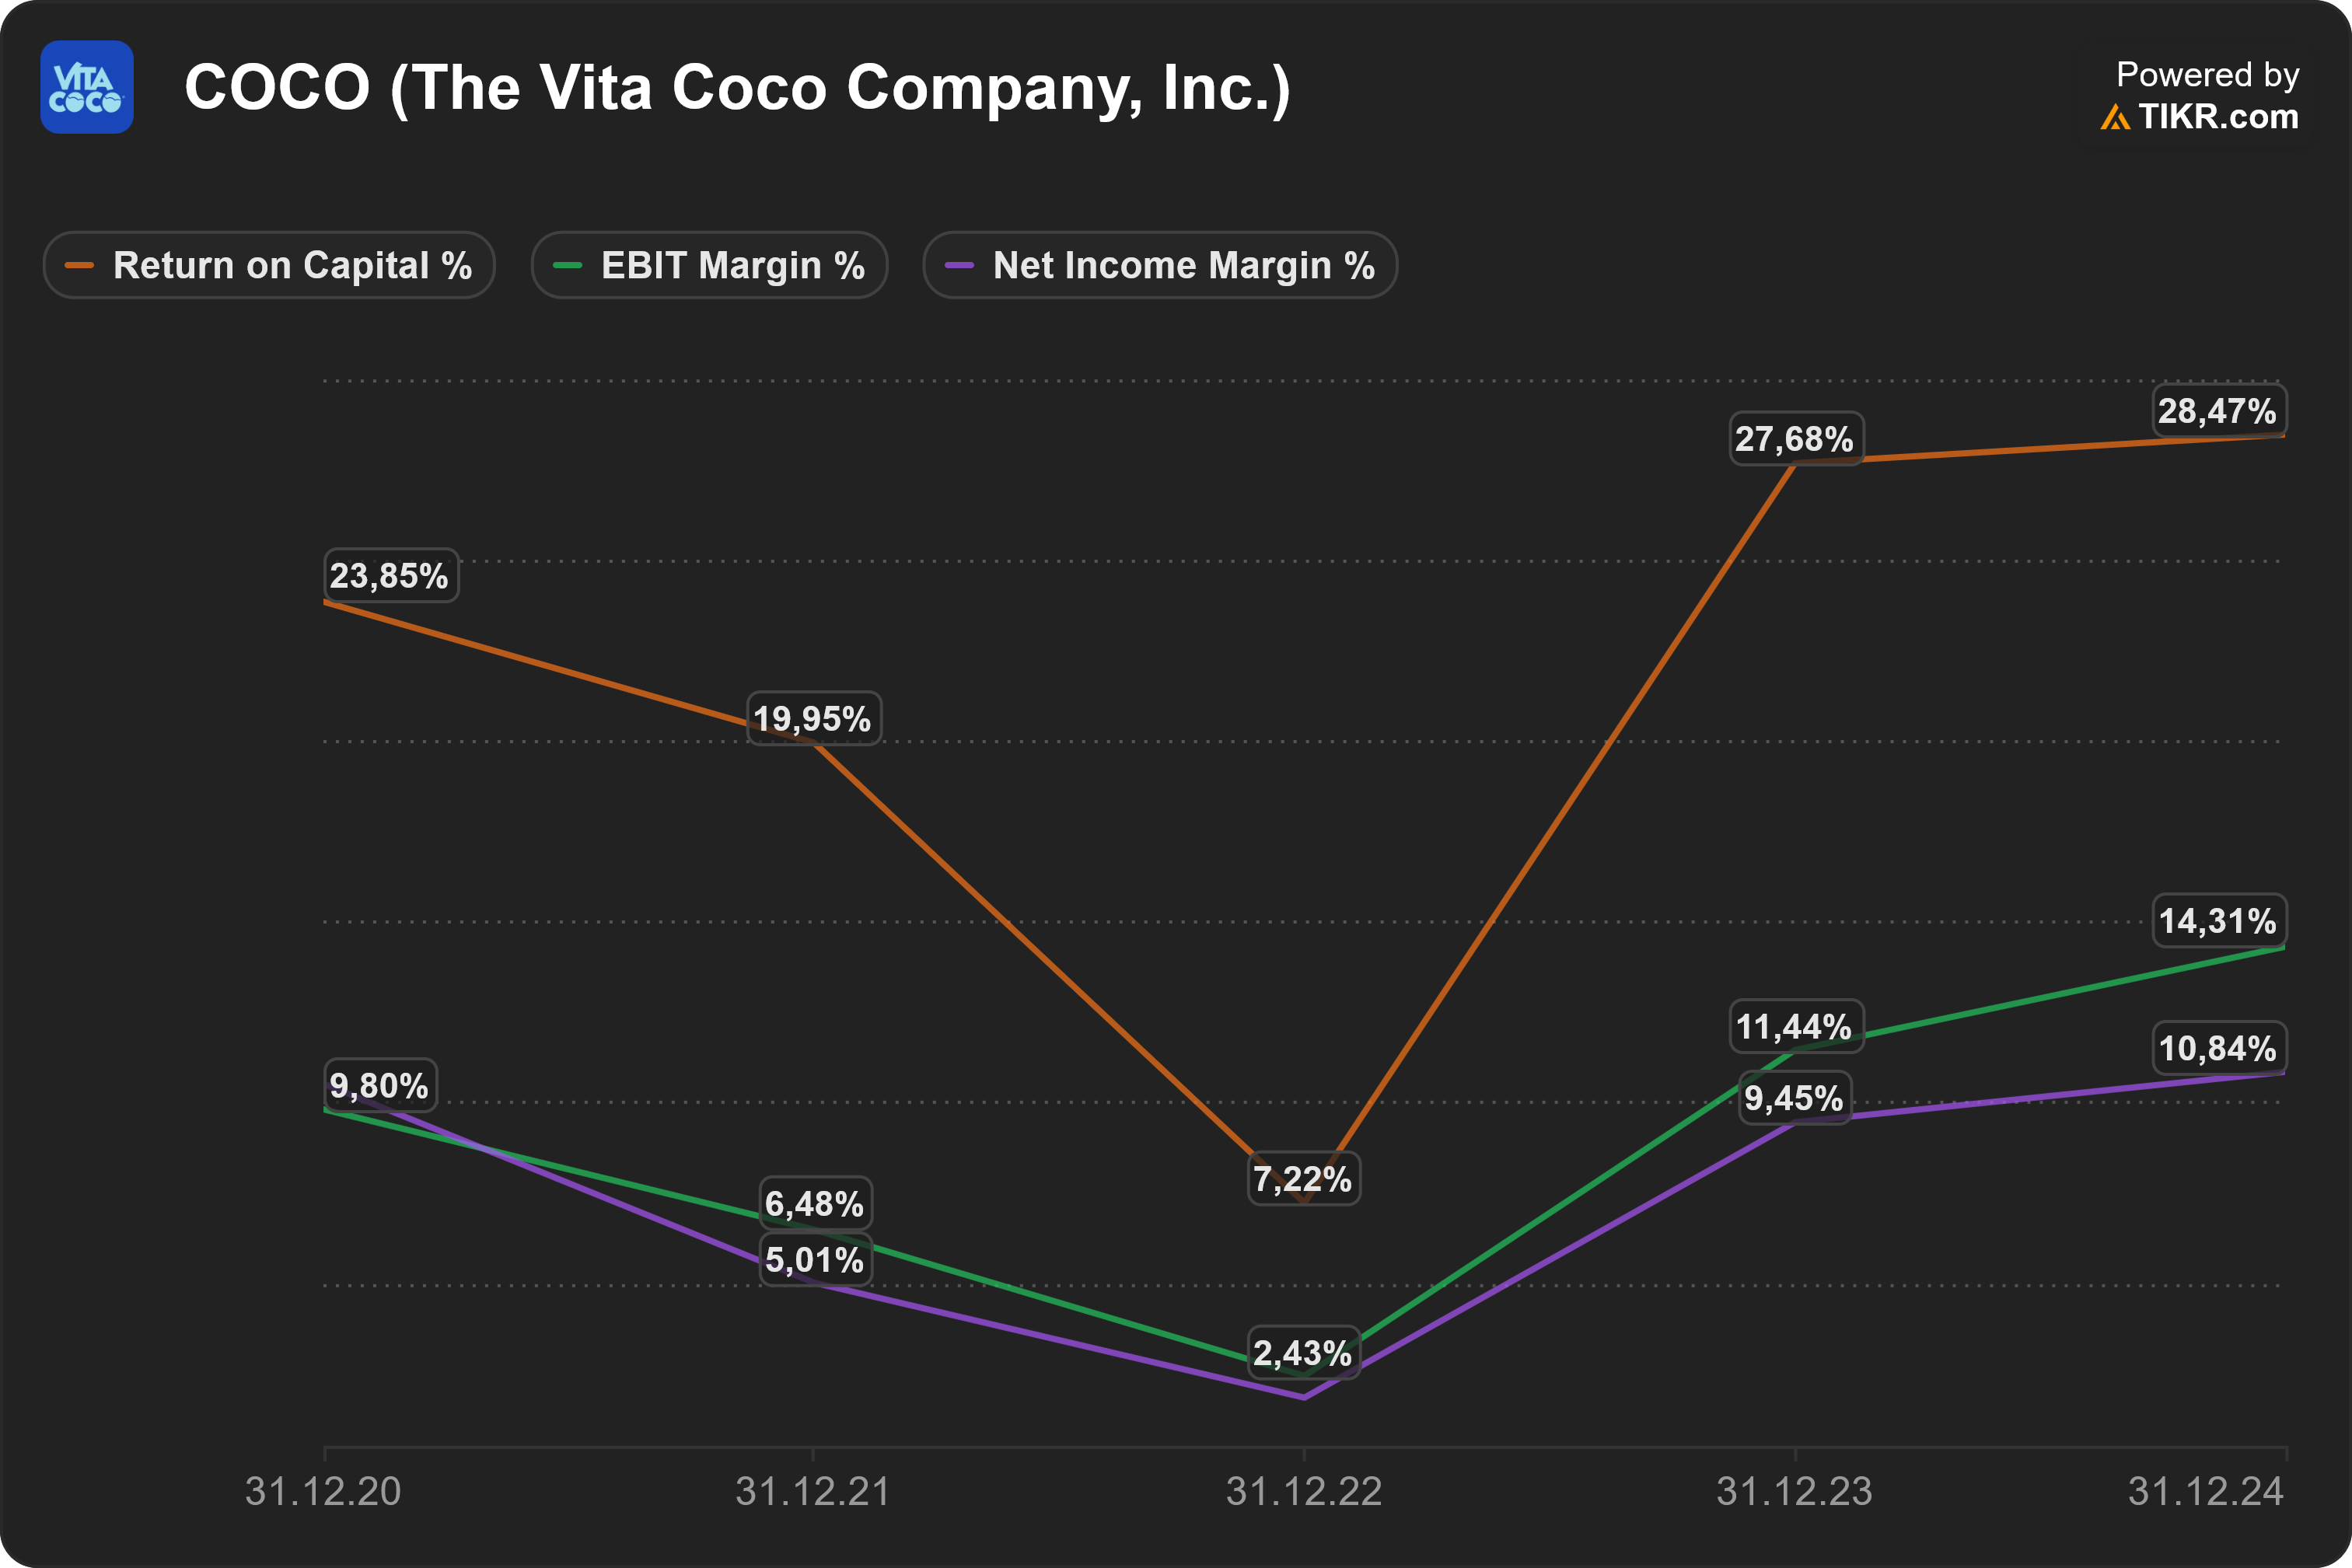
Return on capital tells the same story even more cleanly. After declining materially into 2022, returns surged back to the high-20% range in 2023 and 2024. That’s not just a recovery — it’s evidence that Vita Coco’s asset-light, brand-driven model scales extremely well once costs normalize. Few consumer companies at this size generate returns like that without leverage.
The takeaway here is quality. By 2024, Vita Coco wasn’t just growing again — it was doing so with efficiency, pricing power, and real economic strength.
Free Cash Flow: Volatile by Design, Powerful in Practice
The free cash flow chart is volatile. In 2021 and 2022, free cash flow was negative. But this wasn’t because the business was structurally unprofitable. It was driven primarily by working capital movements, especially inventory and receivables, during a period of supply disruption and cost inflation.
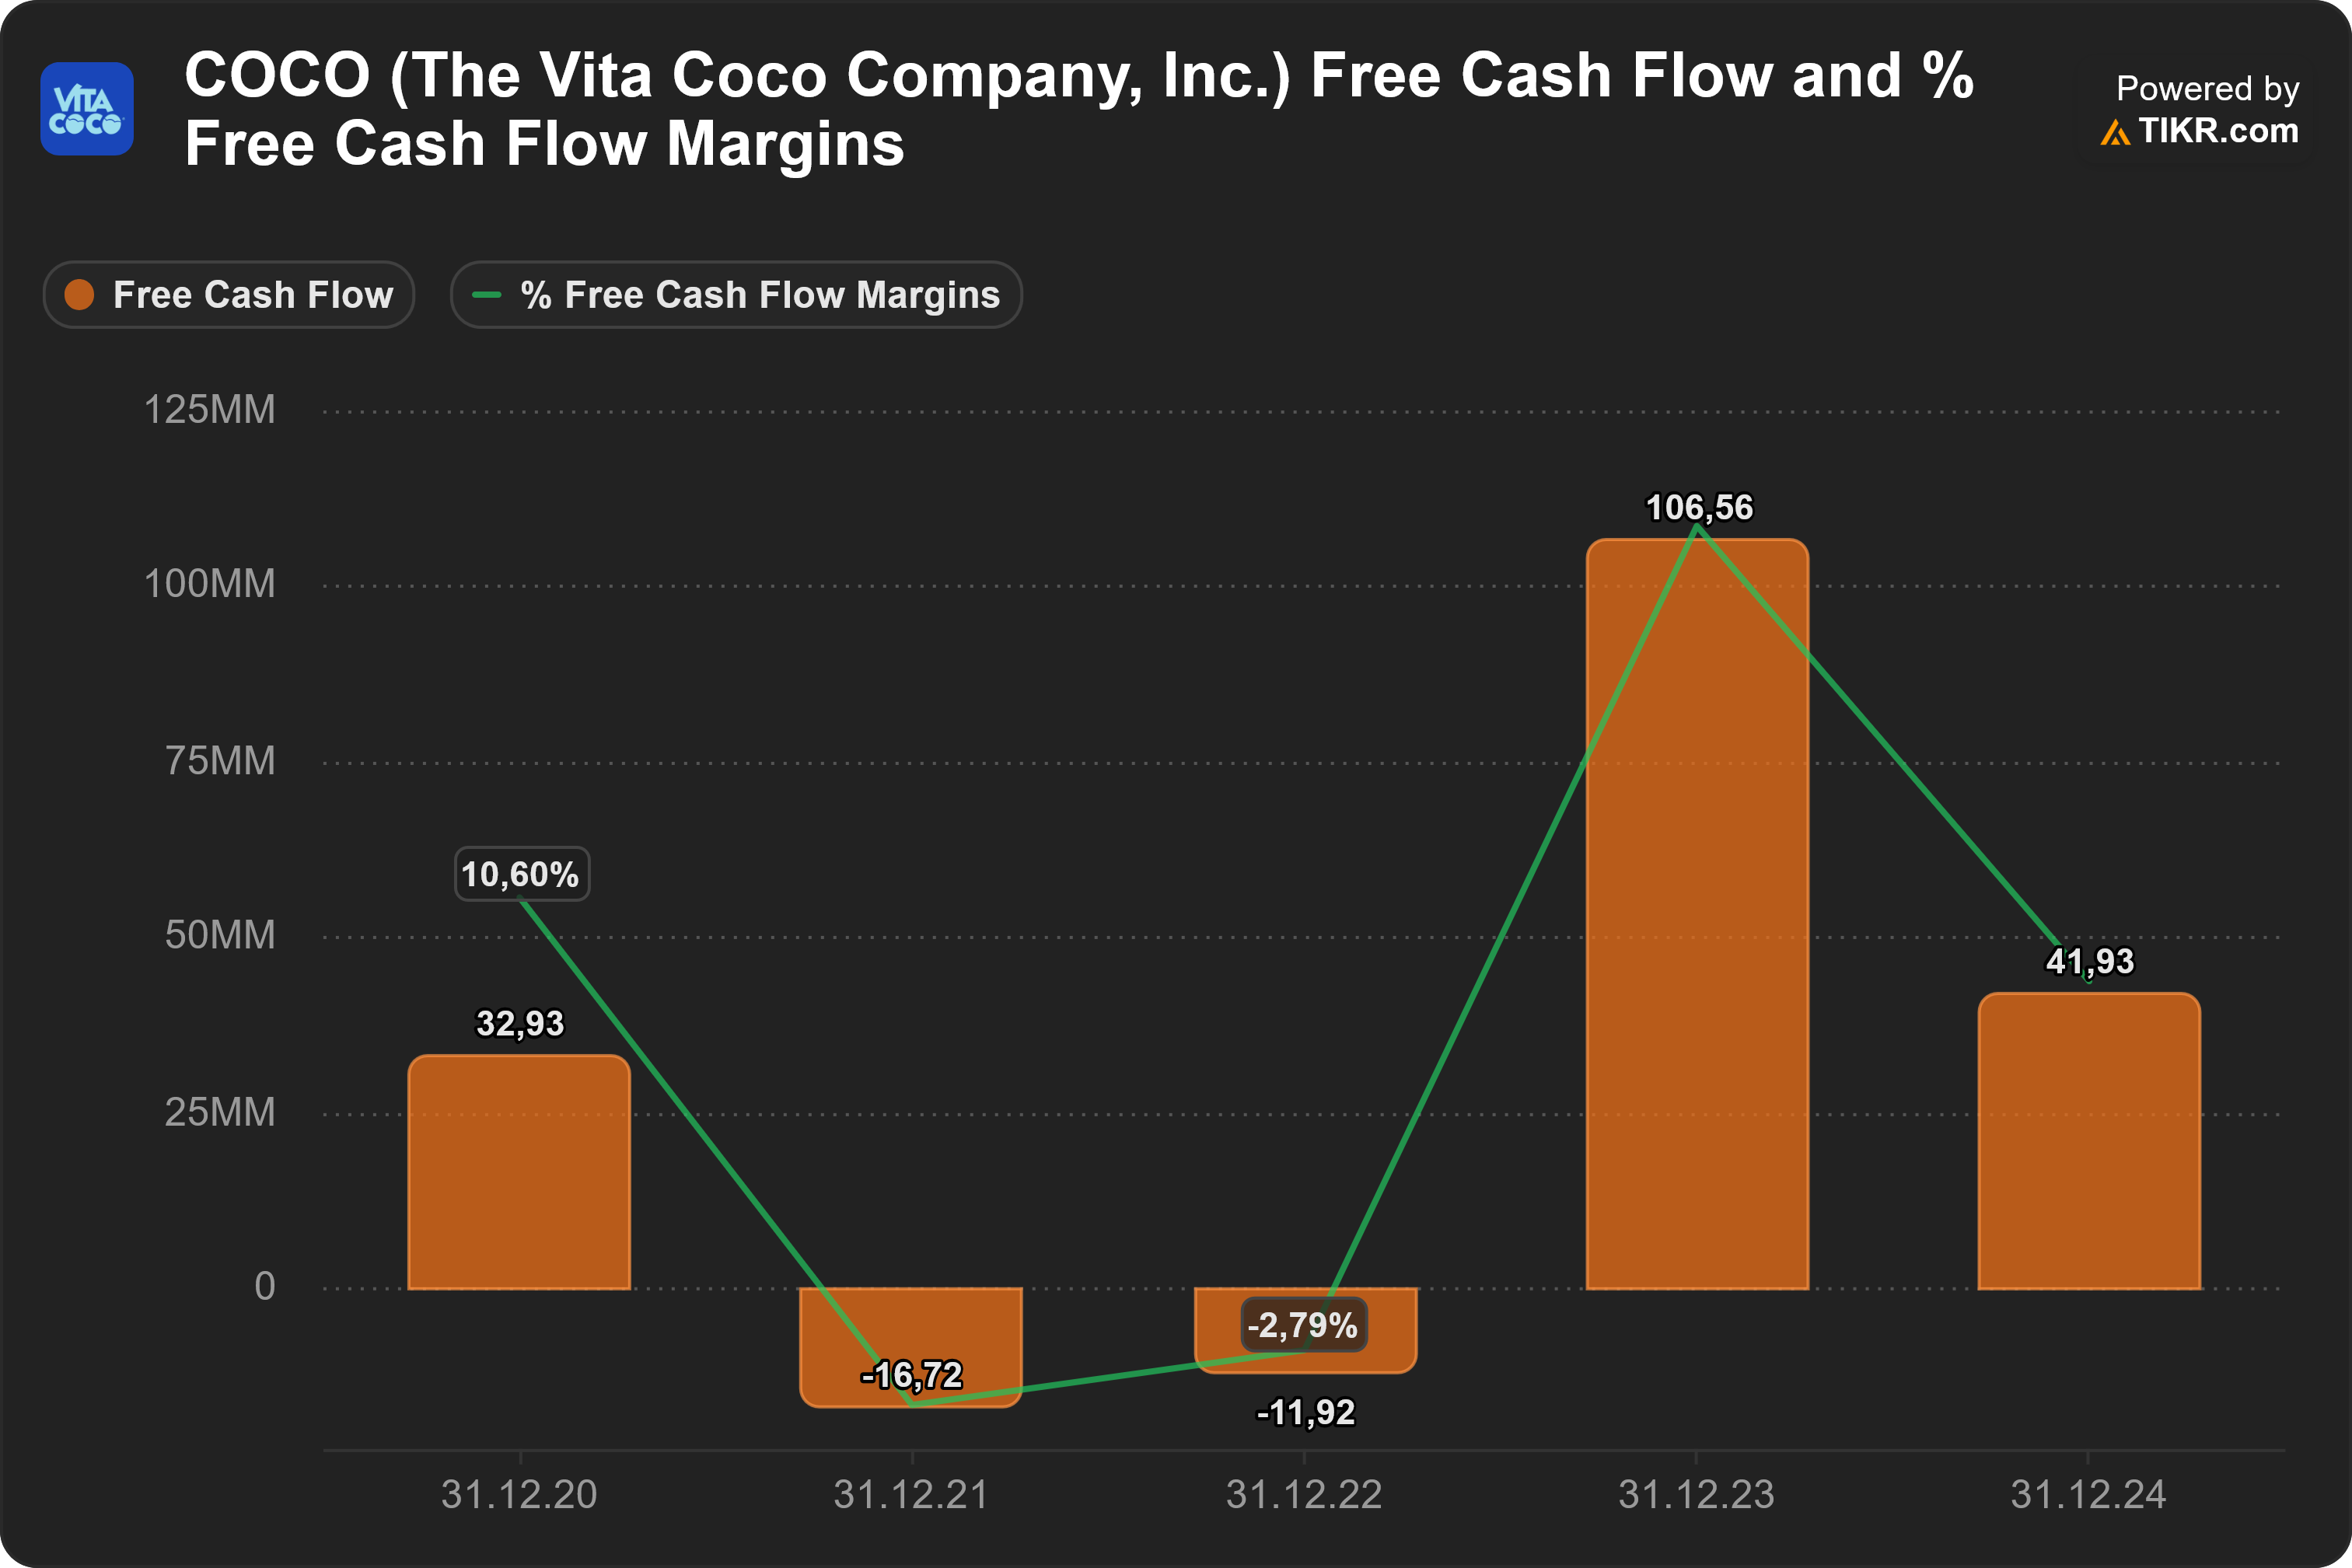
Then in 2023, everything swung the other way. Operating cash flow surged, and free cash flow exploded to over $100 million. That wasn’t financial engineering — it was the release of working capital combined with sharply improved profitability.
In 2024, free cash flow normalized to about $42 million. Importantly, this wasn’t a deterioration. Management explicitly notes that operating cash flow declined because the company rebuilt inventory to support future growth and improve service levels. In other words, Vita Coco deliberately reinvested cash back into the system after a year of extreme inflows.
What matters most is this: across cycles, the business has proven it can generate real cash, not just accounting profits — and it can do so without heavy capital expenditure.
Balance Sheet and Debt: Quiet Strength
The final chart — net debt to EBITDA — is almost boring, and that’s a compliment.
Vita Coco has maintained net cash in every year shown. By the end of 2024, the company held a large cash balance and virtually no meaningful debt, with only minor vehicle loans outstanding and no drawn revolver.
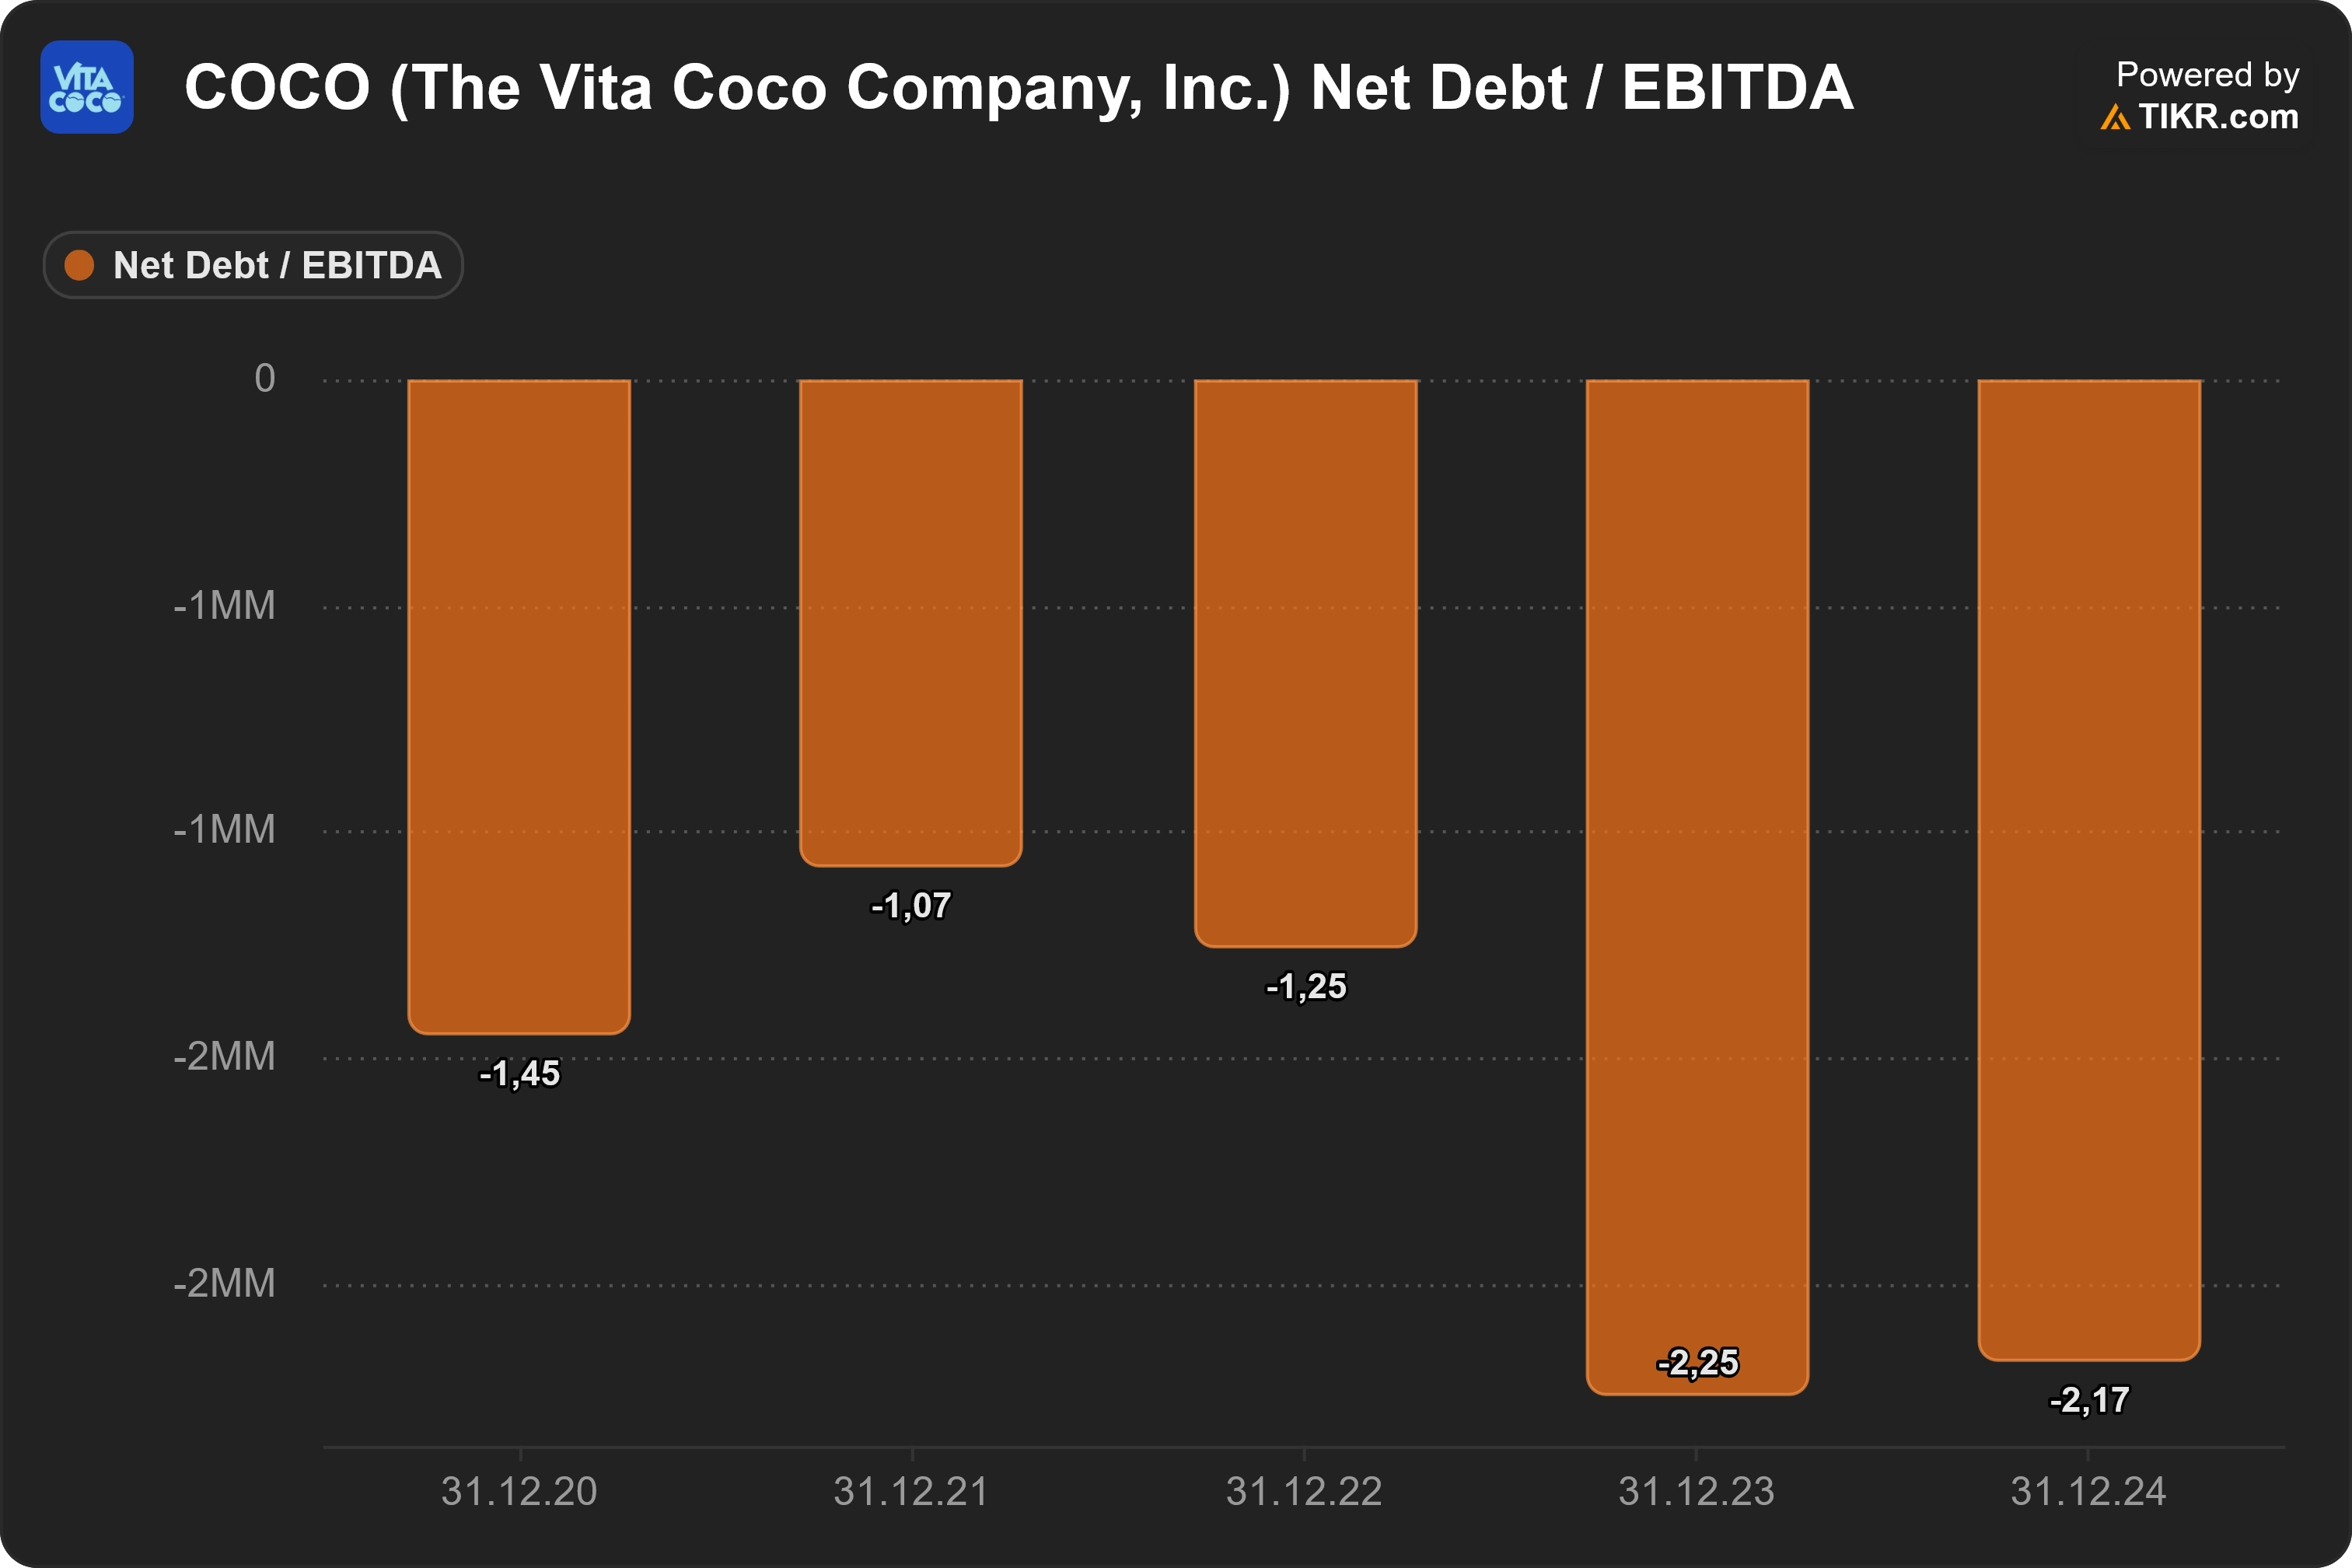
This matters more than it might seem. In a category exposed to agricultural inputs, freight costs, and retailer concentration, financial flexibility is a competitive advantage. Vita Coco doesn’t need leverage to grow. It can absorb shocks, fund inventory, buy back shares, or pursue small acquisitions from a position of strength.
The Big Picture
Put all four charts together, and the message is clear:
Vita Coco is no longer just a fast-growing brand — it is now a profitable, high-return, cash-generative category leader that has already been through a real operating stress test. The margin collapse of 2022 wasn’t a warning sign; it was a proving ground. The rebound in 2023 and 2024 shows a business whose economics improve meaningfully with scale.
That doesn’t make the stock cheap. But it does mean the fundamentals beneath it are real, resilient, and materially better than they were a few years ago.
For long-term investors, that distinction matters.
Business Model
Vita Coco’s business model is simple, focused, and brand-led. Revenue comes from two sources: Branded products (dominated by the Vita Coco label) and Private Label products supplied to retailers. In practice, this is overwhelmingly a branded business—as of 2024, 96% of revenue came from coconut water, primarily under the Vita Coco name. This heavy concentration means the company is deeply tied to the coconut water category, but it also makes Vita Coco synonymous with the trend it created.
Operationally, Vita Coco runs a fully asset-light supply chain. It sources coconut water from 17 partner facilities across 7 countries and outsources production and packaging, owning no farms or factories. This keeps capital needs low, reduces risk, and allows the company to scale quickly without fixed-cost drag. Vita Coco focuses its resources where it matters most: branding, marketing, and distribution.
Distribution is a major competitive advantage. Vita Coco has built a broad omni-channel footprint, selling through grocery chains, club stores, convenience stores, e-commerce, foodservice, gyms, offices, and campuses. Whether it’s a bulk pack at Costco, a chilled bottle at 7-Eleven, or an online order, the goal is ubiquity—to be present wherever beverages are sold.
Geographically, the business is split between the Americas and International markets. The U.S. dominates, accounting for roughly 85% of net sales, while the U.K. stands out as the strongest international market, where Vita Coco clearly leads its category. This setup highlights a double-edged sword: strong exposure to the world’s largest beverage market, but also heavy reliance on U.S. consumer demand, with plenty of runway still available internationally.
A distinctive feature of the model is Vita Coco’s private label strategy. Instead of fighting store-brand coconut water, the company supplies it, working with major retailers like Costco and Walmart. This helps fill capacity, strengthen retailer relationships, and monetize the value segment without diluting the premium Vita Coco brand. The downside: private label contracts can be lumpy and volatile. In 2025, the loss of some service regions caused private label sales to decline, though one major customer has already asked Vita Coco to resume supply in 2026. Additionally, two customers account for ~45% of total net sales, making key retail relationships critical.
On the product side, Vita Coco is gradually broadening its portfolio. The core remains classic Vita Coco coconut water, positioned as a healthier alternative to sugary sports drinks and sodas. Around that core, the company has added Pressed, Coconut Juice, Coconut MLK, and the newer Vita Coco Treats chocolate coconut milk. These extensions expand usage occasions and attract adjacent consumers without straying far from the brand’s health halo.
Beyond coconut water, Vita Coco is experimenting with small, optionality-driven brands like PWR LIFT (protein water) and Ever & Ever (sustainably packaged water). These remain immaterial today, and not every bet succeeds (the Runa energy drink was discontinued). Still, the strategy is clear: stay anchored in coconut water while testing future growth paths in the broader functional beverage space.
Strengths and Competitive Advantages
Category Leader with a Powerful Brand
Vita Coco is the clear #1 coconut water brand in the U.S. (~40% market share) and, in many consumers’ minds, is the category. The same dominance shows up internationally—most notably in the U.K., where it holds ~82% market share. This first-mover advantage and brand recognition translate into pricing power, prime shelf space, and marketing scale that competitors struggle to match.
Strong Tailwinds from Health & Wellness Trends
Coconut water sits at the crossroads of functional beverages and clean, natural hydration—two of the fastest-growing segments in drinks. As consumers move away from sugary sodas toward plant-based electrolytes for sports, recovery, and everyday hydration, Vita Coco continues to ride a long-term wellness wave it helped create.
Asset-Light, Highly Scalable Supply Chain
By owning no farms or factories, Vita Coco keeps fixed costs low and can scale production quickly without heavy capital investment. Sourcing from 17 partner facilities across 7 countries also reduces supply risk and adds flexibility. This model has proven resilient through supply-chain disruptions and supports healthy margins.
Strong Financials and Cash Generation
Unlike many beverage growth stories, Vita Coco is consistently profitable and cash-flow positive. It carries minimal debt, holds a solid cash position, and generated free cash flow margins near 20% in Q3 2025. Over the past three years, EPS growth has been exceptional, reflecting improving operating leverage. This financial strength enables marketing investment, innovation, and share buybacks without stretching the balance sheet.
Wide and Hard-to-Replicate Distribution
Vita Coco has built an extensive omni-channel distribution network, spanning big-box retailers, grocery chains, convenience stores, e-commerce, and foodservice. For a beverage brand, this reach is a major moat—shelf space and distributor relationships take years to build. Deep ties with major retailers further cement Vita Coco’s position.
Disciplined Innovation and Brand Extensions
The company innovates close to its core, expanding into adjacent products like Vita Coco Pressed, flavored coconut water, and Vita Coco Treats. These extensions refresh the brand, broaden use cases, and leverage existing consumer trust. Management also emphasizes consumer education to drive higher usage of the core product—boosting volume without reinventing the wheel.
Experienced, Founder-Led Management
Co-founder Michael Kirban remains actively involved as Executive Chairman, supported by a seasoned leadership team with deep beverage-industry experience. They’ve successfully competed against global giants and scaled Vita Coco from a startup into a global leader—while staying profitable. Founder involvement and insider ownership help align management with long-term shareholders.
Weaknesses and Key Risk Factors
Heavy Reliance on a Single Product Category
Despite its brand strength, Vita Coco remains highly concentrated in coconut water, which accounted for ~96% of revenue in 2024. This makes the company’s performance tightly linked to the health of one category. While management aims to build a broader beverage platform, today there is no true second growth engine. If consumer preferences shift or coconut water falls out of favor, Vita Coco has limited insulation.
Customer Concentration & Private Label Volatility
Vita Coco depends heavily on a small number of large retail customers, with two accounts representing ~45% of net sales in 2025 YTD. This creates negotiating leverage for retailers and exposes the company to sudden volume losses. The risk is evident: private label sales fell ~12% in 2025 after several retailers reduced or shifted sourcing. While some business may return, private label remains structurally volatile and less predictable than branded demand.
Competitive Pressure from Beverage Giants
The beverage market is crowded and fiercely competitive. Vita Coco faces not only coconut water peers, but also functional drinks, sports beverages, and emerging hydration trends. Global players like Coca-Cola, Pepsi, and Nestlé have far deeper pockets and broader distribution. Although Vita Coco has defended its niche so far, a renewed push by a major player—or a fast-rising alternative like aloe or hydration mixes—could pressure shelf space, pricing, and marketing effectiveness.
Exposure to Commodity and Supply Chain Risks
Coconuts are an agricultural commodity, making Vita Coco vulnerable to weather disruptions, crop yields, input cost inflation, and global logistics issues. Past supply shortages led to missed sales, and rising costs (packaging, freight, tariffs) have historically compressed margins. While pricing actions helped restore margins in 2024, future shocks—such as tariffs or poor harvests—could again hit profitability in the short term.
Limited Pricing Power in the Value Segment
While the Vita Coco brand commands premium pricing, the private label business is low-margin and price-sensitive. Retailers expect competitive pricing, making it harder to pass through cost increases. As a result, private label can dilute margins and increase exposure to input volatility. The loss of a private label coconut oil customer in 2025 underscores how quickly this revenue can disappear.
Unproven Diversification Efforts
Vita Coco’s track record outside coconut water is mixed. The shutdown of Runa highlights the difficulty of replicating its core success. Newer bets like PWR LIFT, Ever & Ever, and Vita Coco Treats are still early-stage and unproven in highly competitive categories. Until a second meaningful brand emerges, the growth story remains narrowly focused.
Insider Selling Signals to Monitor
Founders and early investors hold significant stakes, which can align interests—but recent insider selling raises some caution. While sales don’t necessarily imply pessimism, continued selling during price strength may suggest insiders view current valuation as fair. For long-term investors, insider activity is a yellow flag worth monitoring, even if not a decisive negative on its own.
Premium Positioning in a Price-Sensitive Environment
Coconut water is a premium, discretionary beverage. In periods of inflation or economic stress, consumers may trade down to cheaper hydration options. Vita Coco must continuously justify its price through health benefits, taste, and brand appeal. A prolonged consumer slowdown could weigh on volume growth, especially among more price-sensitive shoppers.
Dividends and Share Buybacks
Vita Coco is firmly in growth mode, and that shows in its capital allocation. The company does not pay a dividend and has no plans to initiate one in the foreseeable future. Management has been explicit that all earnings are being reinvested into the business—funding new products, marketing, and strategic opportunities. For investors, returns are therefore expected to come from share price appreciation, not income, which is typical for a still-scaling consumer brand.
While there’s no dividend, Vita Coco has been actively returning capital through share buybacks. In October 2023, the Board authorized a $40 million repurchase program, and the company moved quickly to use it. By the end of 2024, Vita Coco had already repurchased ~6.7 million shares (about $71.7 million at cost, including prior activity). Buybacks continued opportunistically in 2025, with ~338,000 shares repurchased for $10.2 million in the first nine months.
As of Q3 2025, Vita Coco held 7.08 million shares in treasury—over 10% of outstanding shares. That’s a meaningful reduction in share count, increasing ownership for remaining shareholders and helping offset dilution from employee equity compensation.
The buybacks signal management confidence in the company’s intrinsic value and reflect strong cash generation and balance-sheet flexibility. That said, repurchases are opportunistic, not guaranteed. With the stock price higher in 2025, the pace of buybacks has already slowed, and the remaining authorization may or may not be fully used.
Stock Valuation
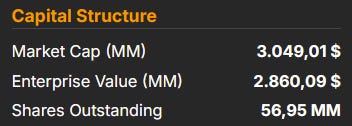
Vita Coco’s stock has had a strong run, and the valuation makes it clear that the market is treating it as a growth compounder, not a typical consumer staples name. As of early 2026, shares trade in the mid-$50s, implying a market cap of roughly $3 billion.
On forward-looking metrics, the stock is decidedly expensive. Based on the chart, Vita Coco currently trades at about 36.8× NTM price-to-normalized earnings, well above its long-term average of ~31× and close to the upper end of its historical range (low ~23×, high ~43×). On an enterprise basis, the stock trades around 28.3× NTM EV/EBIT, again significantly above the historical mean of ~23× and near cycle highs.
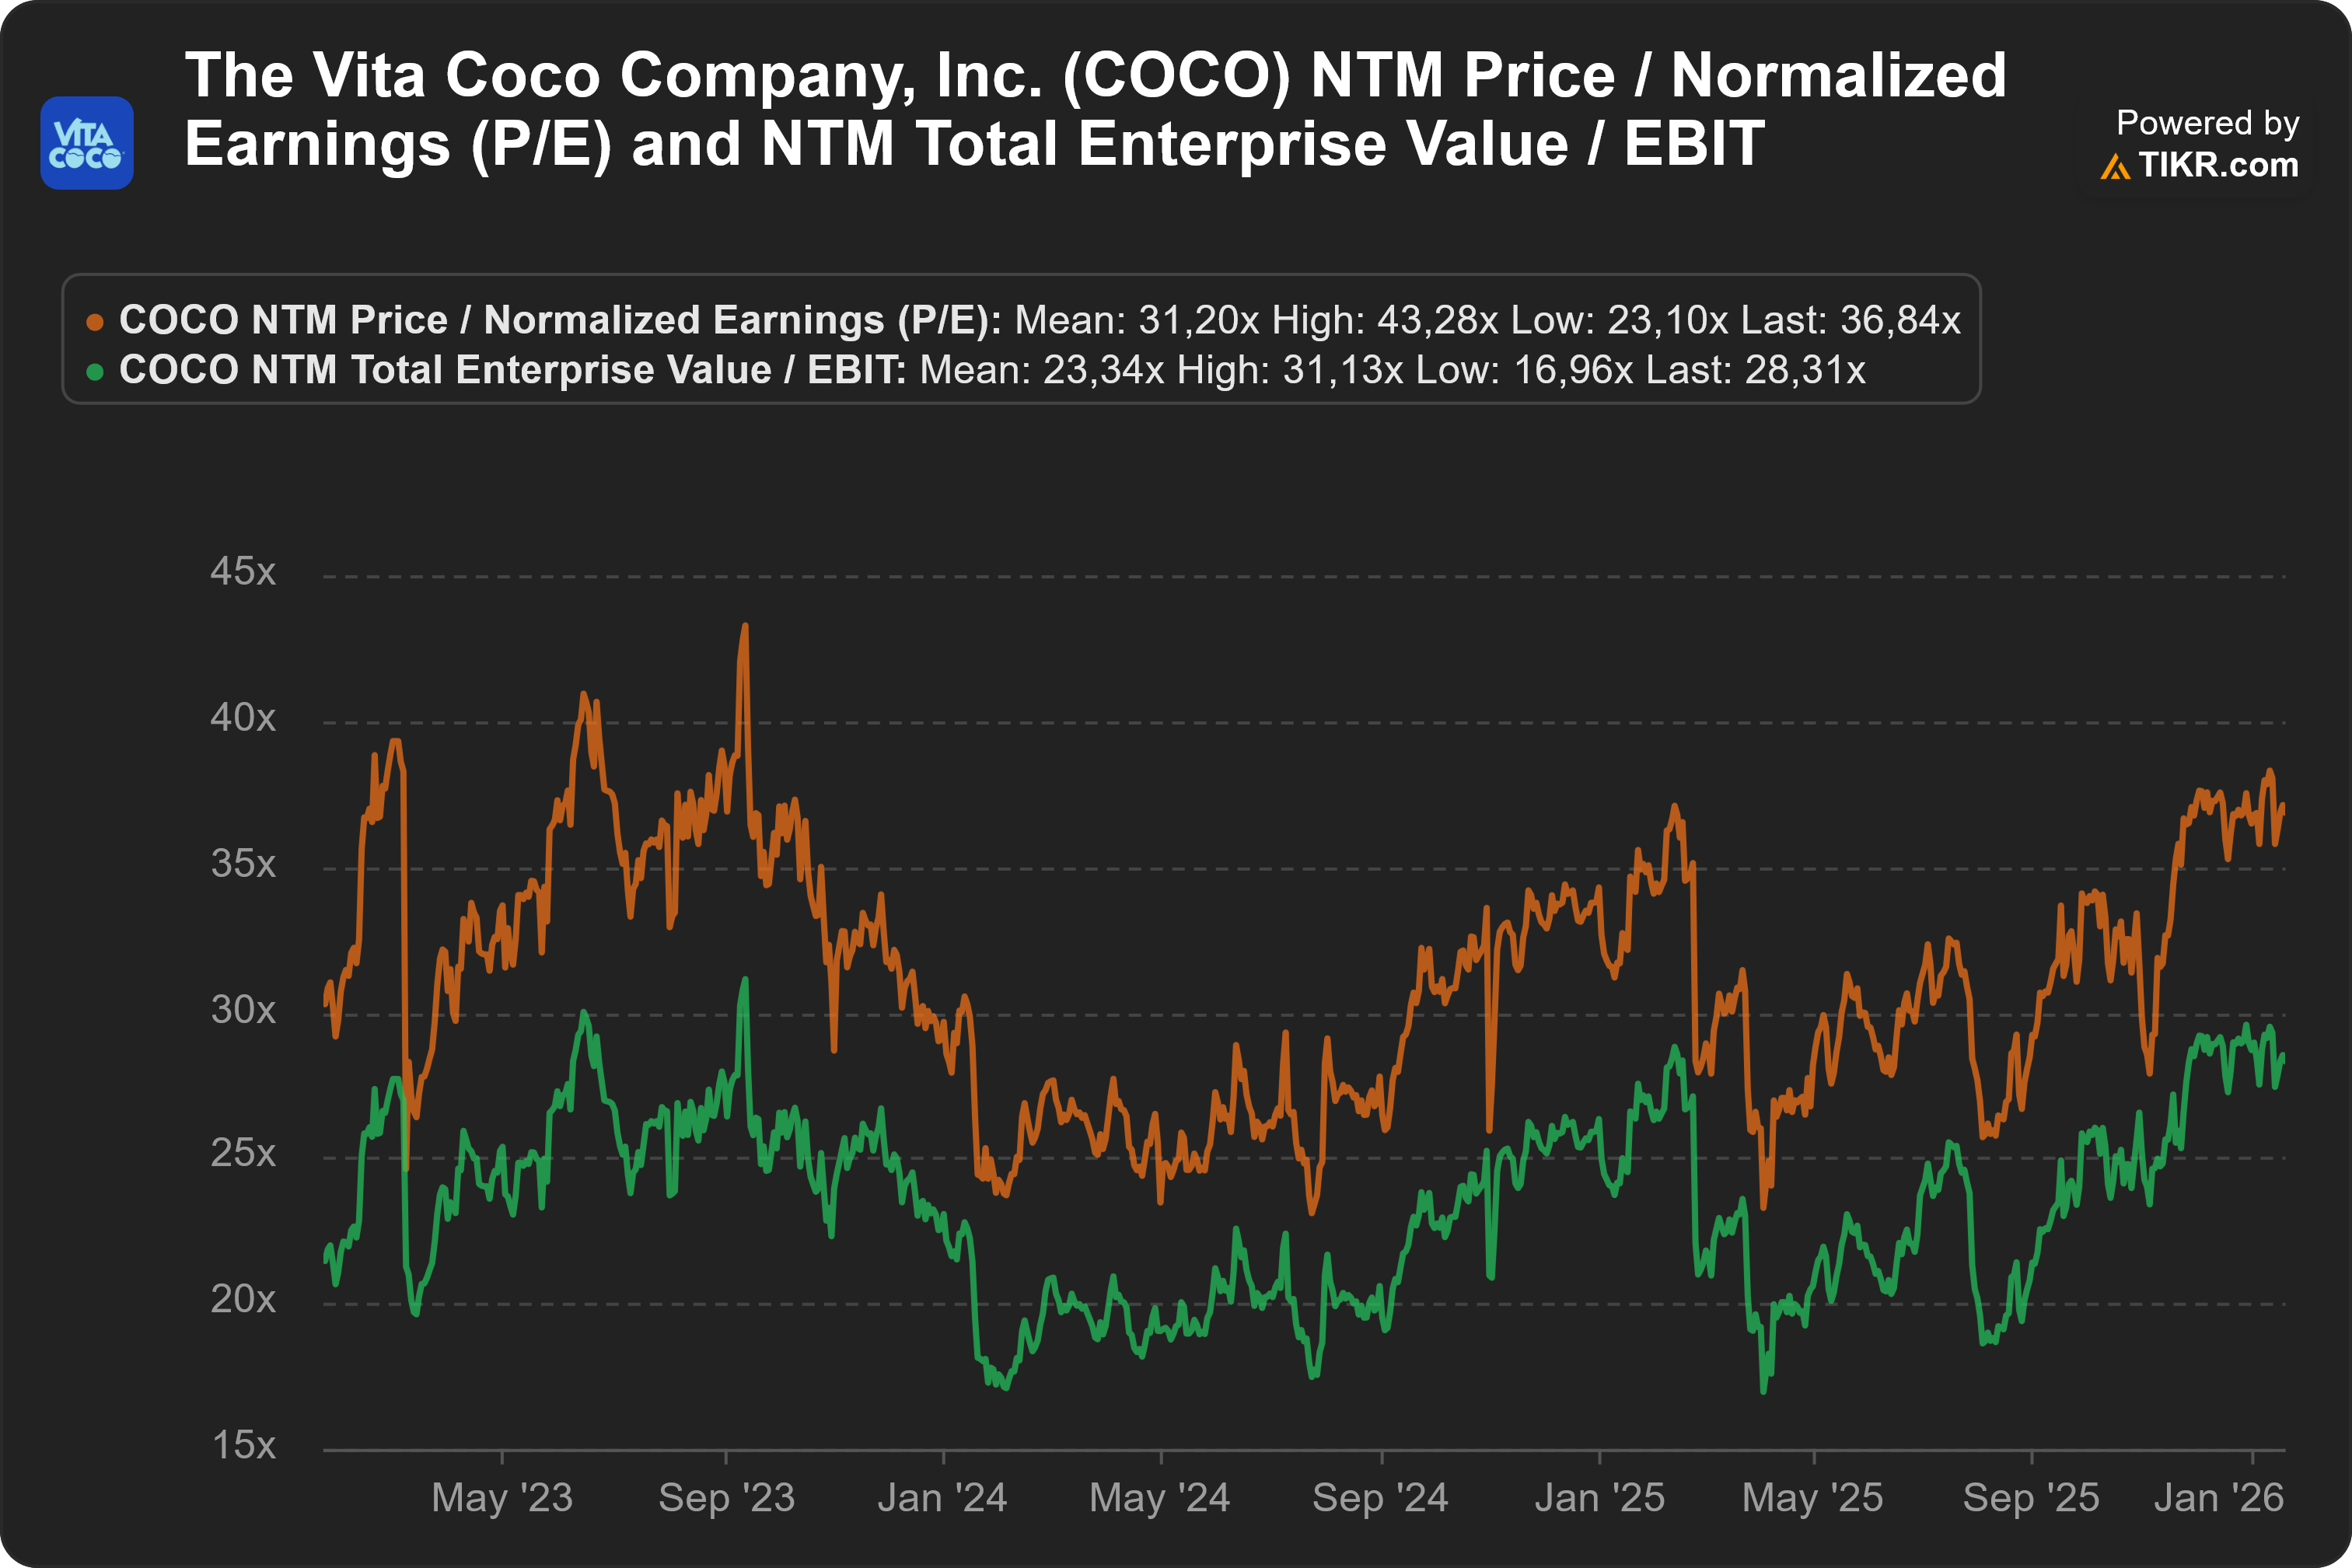
This premium reflects strong recent fundamentals. Sales re-accelerated in 2025, margins recovered sharply from the 2022 trough, and cash generation improved materially. Investors are clearly pricing Vita Coco as a high-quality niche beverage platform with durable brand power, not as a slow-growing staple. Its relatively small size also adds strategic optionality, which can further support elevated multiples.
That said, the valuation leaves little room for disappointment. At nearly 37× forward earnings and ~28× EV/EBIT, the stock assumes continued double-digit growth and solid execution. Any slowdown in volume growth, margin pressure, or guidance misstep could lead to multiple compression, which has historically been swift when expectations reset. The chart itself shows this clearly: periods of weaker sentiment have pushed the stock back toward the low-20s multiples in the past.
Bullish Investment Case
Long-term bulls view The Vita Coco Company as a rare growth story in beverages—a brand-led compounder benefiting from powerful consumer and financial tailwinds. The bullish case rests on several key pillars:
Riding a Long-Term Health & Wellness Wave
The global shift toward healthier, functional beverages is a durable tailwind, not a passing fad. Coconut water fits perfectly into this trend as a natural source of hydration and electrolytes. As the category creator and leader, Vita Coco is positioned to capture an outsized share of category growth. Bulls believe per-capita consumption can keep rising for years as awareness grows and usage occasions expand—from sports recovery to everyday hydration. In short, Vita Coco isn’t chasing a trend—it is the face of one.
Category-Leading Brand with a Defensible Moat
Vita Coco’s brand strength is a major competitive advantage. With 15+ years of category credibility, dominant market share, and deep retailer relationships, it’s difficult for new entrants to replicate its position. Even global giants failed to dislodge Vita Coco in coconut water—a strong signal of brand loyalty and shelf dominance. For investors, this suggests a durable franchise with pricing power and protection against copycats.
High Growth + Margin Expansion = Powerful Earnings Leverage
Bulls are encouraged by Vita Coco’s operating leverage. As the company scales, margins have expanded—gross margin reached ~39% in 2024, and EBITDA margins continue to improve. Operating costs don’t rise in lockstep with revenue, allowing profits to grow faster than sales. Management expects record EBITDA in 2025 (~$90–95M), and bulls see upside if mix and scale push margins back toward 40%+ over time. Combined with share buybacks, this creates a credible path to outsized EPS growth, potentially validating today’s premium valuation.
Significant International Runway
Outside the U.S. and U.K., Vita Coco remains underpenetrated, which bulls view as a major opportunity. Large beverage markets like continental Europe and Asia are still in early stages of coconut water adoption. By replicating its proven playbook—retail expansion, consumer education, influencer-driven awareness—Vita Coco could unlock years of incremental growth. Successful international scaling would extend the growth runway well beyond U.S. maturity.
Product Innovation and Portfolio Optionality
Beyond geography, bulls see upside from adjacent product expansion. Launches like Vita Coco Treats open the door to the plant-based milk category, while other coconut-based or functional beverages could broaden the addressable market. Importantly, management has shown capital discipline, shutting down underperformers like Runa rather than chasing sunk costs. Each successful extension adds incremental revenue and gradually reduces reliance on a single product.
Takeover or Strategic Optionality
While not central to the thesis, Vita Coco’s strong brand and category leadership make it a plausible acquisition or partnership target. Larger beverage players may eventually decide it’s more efficient to buy rather than compete. This optionality provides a potential valuation backstop or upside kicker if strategic interest materializes.
Proven, Founder-Led Management with Shareholder Alignment
Co-founder Michael Kirban’s continued involvement and meaningful ownership align management with long-term shareholders. The leadership team has successfully navigated rapid growth, intense competition, and a public listing—while remaining profitable. Capital allocation has been disciplined, combining reinvestment with accretive buybacks. Bulls trust this team to balance growth, margins, and shareholder value.
In summary: Bulls believe Vita Coco is far more than a coconut water fad. It’s a profitable, brand-driven growth company riding a global shift toward healthier consumption. If execution continues and growth vectors play out, today’s valuation could look reasonable in hindsight—with Vita Coco compounding value for years to come.
Bearish Investment Case
Skeptics argue that Vita Coco is a good company priced like a great one. At today’s valuation, even small disappointments could have outsized consequences. The bear case centers on the following concerns:
Valuation Leaves No Room for Error
At roughly ~45× earnings and ~5× sales, Vita Coco is priced for near-perfect execution. With the stock up ~55% over the past year, much of the upside may already be reflected. Any slowdown in growth, margin pressure, or guidance miss could trigger multiple compression and a sharp pullback. Bears argue the current valuation assumes continued acceleration, which is risky for a small company in a competitive industry.
Overdependence on Coconut Water
Vita Coco remains heavily reliant on a single category, with no proven second growth engine. Beverage history is littered with once-hot trends that eventually plateaued—Vitaminwater, kombucha, cold brew, and others. If coconut water demand flattens or consumer attention shifts to the next trend (aloe, cactus water, hydration powders), Vita Coco has limited fallback options. Its newer brands are small and unproven, reinforcing the risk of being a one-trick pony.
Risk of U.S. Saturation and Slowing Growth
In the U.S., coconut water is no longer novel. Vita Coco is already widely distributed after nearly two decades on shelves. Bears question how much further household penetration can realistically rise. Recent growth spikes—such as Q3 2025’s +37% revenue jump—were partly driven by inventory restocking and easy comparisons, not purely organic demand. Management’s own guidance implies moderating growth, and if U.S. growth settles into single digits, today’s valuation looks difficult to justify.
Execution Risk as the Business Scales
Sustaining growth may require higher marketing spend, especially to reach less trend-driven consumers. Historically, Vita Coco benefited from earned media and influencer buzz, but that may not scale indefinitely. On the innovation front, Runa’s failure shows that success outside coconut water is far from guaranteed. New launches like Vita Coco Treats add complexity and risk—if they fail to gain traction, they could drain resources and management focus.
Competition Is Intensifying, Not Fading
Despite its lead, Vita Coco faces persistent competitive pressure. Large incumbents can outspend it, niche players can target premium segments, and retailers may push private label alternatives more aggressively as the category matures. Even modest share loss or heavier promotional activity could pressure both growth and margins. Bears argue Vita Coco’s moat is real but not unbreakable.
Margin Vulnerability
The margin gains of 2024 may prove hard to sustain. Management has already guided to lower gross margins (~36%) in 2025, citing higher input costs, tariffs, and mix effects. Rising private label volumes, increased marketing spend, or international expansion costs could further weigh on profitability. If operating leverage turns negative—even temporarily—the stock’s premium multiple becomes hard to defend.
Supply Chain and Agricultural Risk
Vita Coco’s business depends on a globally dispersed agricultural supply chain, exposing it to weather events, political risk, trade disruptions, and climate volatility. Past coconut shortages caused missed sales, and similar events could recur. While the asset-light model adds flexibility, it also means less direct control over suppliers and co-packers.
Insider Selling and Share Overhang
Recent insider and large shareholder selling raises questions about sentiment at current price levels. While not inherently negative, continued selling could create a share overhang, limiting upside and weighing on investor confidence—especially in a stock already trading at elevated multiples.
Outlook and Future Prospects
Looking ahead, The Vita Coco Company enters the next phase with strong momentum—but measured expectations. For FY 2025, management raised guidance to net sales of $580–$595 million, implying roughly ~14% growth versus 2024. This outlook assumes high-teens growth in Vita Coco coconut water, supported by distribution gains, rising household penetration, and early traction from the Vita Coco Treats launch.
On profitability, management is taking a conservative stance. Gross margin is expected to normalize to around ~36% in 2025 (down from 39% in 2024), reflecting higher input costs and tariffs, partly offset by pricing actions and easing logistics. Operating expenses are projected to rise high-single digits as the company continues to invest in growth. Even so, Adjusted EBITDA is guided to a record $90–95 million, implying stable-to-slightly improving profitability and an EBITDA margin in the mid-teens. In short, Vita Coco expects to grow without sacrificing earnings quality.
Q3 2025 Call: “…we believe that we will be able to mitigate the potential tariff impact long-term and remain very competitive in our markets. We are confident in our team's ability to execute and deliver our plans for the balance of 2025 and 2026, and our confidence in the category and Vita Coco brand trends remains very high.”
Beyond 2025, management hasn’t issued formal targets—but the strategic direction is clear. The core focus remains deepening penetration of coconut water, both by converting new consumers and increasing usage among existing ones. Key initiatives include expanding usage occasions (daily hydration, mixers, foodservice) and pushing further into convenience, on-premise, and institutional channels. Internationally, markets outside the U.S. and U.K. remain underdeveloped, offering longer-term growth optionality, particularly in Europe and parts of Asia.
Product innovation is another swing factor. Vita Coco Treats will be in its first full year of national rollout in 2025 and is a major watch item—success could open a meaningful foothold in plant-based dairy alternatives, while underperformance would likely prompt a pivot. Smaller brands like PWR LIFT remain optionality plays. With a strong balance sheet, Vita Coco also has flexibility for small bolt-on acquisitions, though management has so far remained disciplined.
On the operational side, scaling the asset-light supply chain remains both a strength and a responsibility. As volumes grow, the company must ensure consistent coconut supply, quality control, and partner capacity, potentially through deeper supplier relationships and sustainability investments. Macro conditions will also matter: persistent inflation or an economic slowdown could pressure volumes or margins, while stable consumer spending would support continued growth.
Capital allocation remains growth-first. No dividend is expected in the near term, but selective share buybacks may continue as cash generation improves. Over time, if reinvestment needs decline, a more explicit capital return story could emerge.
Conclusion
In a coconut shell, The Vita Coco Company is a rare beast in the beverage world: a premium coconut water pure-play that has grown from scrappy startup to undisputed category leader. For long-term investors, the appeal is obvious—a powerful brand moat, exposure to durable health and wellness trends, consistent profitability, and a debt-free balance sheet. Vita Coco has proven it can build a category, fend off global giants, and adapt through operational challenges, all while staying financially disciplined.
That said, the story isn’t flawless. Valuation is demanding, leaving little margin for missteps, and the company’s heavy reliance on coconut water cuts both ways. Focus and expertise have fueled success—but they also mean the entire thesis rests on coconut water’s continued global relevance and Vita Coco’s ability to defend share while expanding the market. That’s a bet investors must actively monitor, not passively assume.
Looking ahead, execution is everything. Can Vita Coco sustain double-digit growth as it scales? Will margins hold up amid cost pressure and competition? Can new products and international markets meaningfully diversify the business without diluting the brand? The answers to these questions will determine whether today’s optimism translates into tomorrow’s returns.
For now, the narrative is one of measured confidence. Management sees strong momentum carrying into 2025, while remaining clear-eyed about the work required—educating consumers, expanding usage occasions, and protecting shelf space. Investors should watch the fundamentals closely: volume-driven growth vs. pricing, market share trends, traction in new products, and competitive responses from larger players.